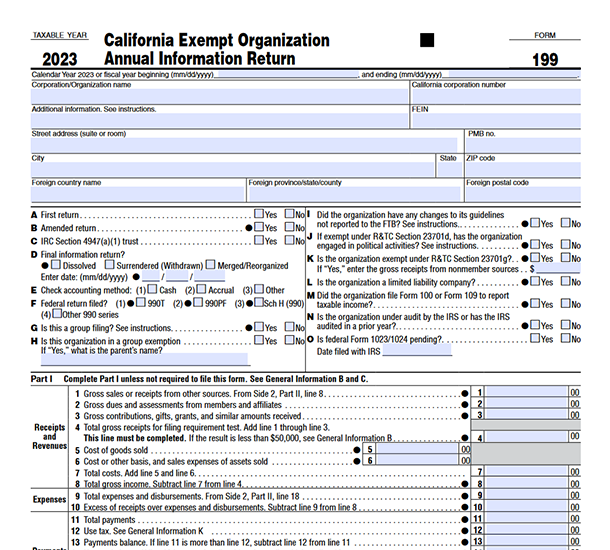
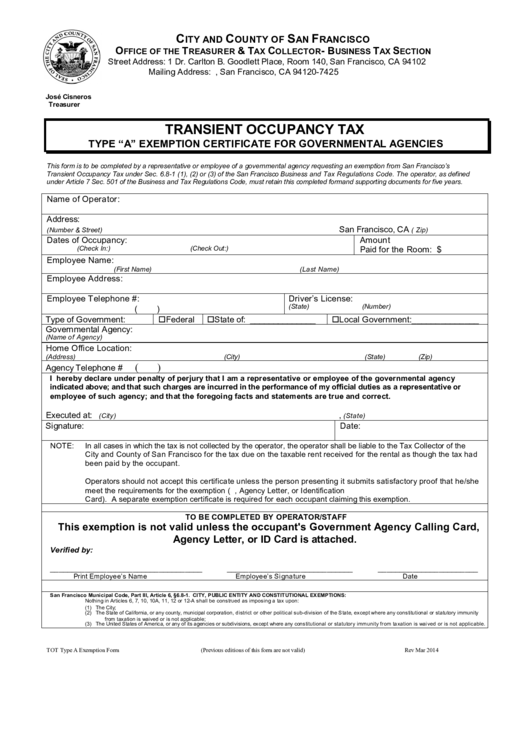
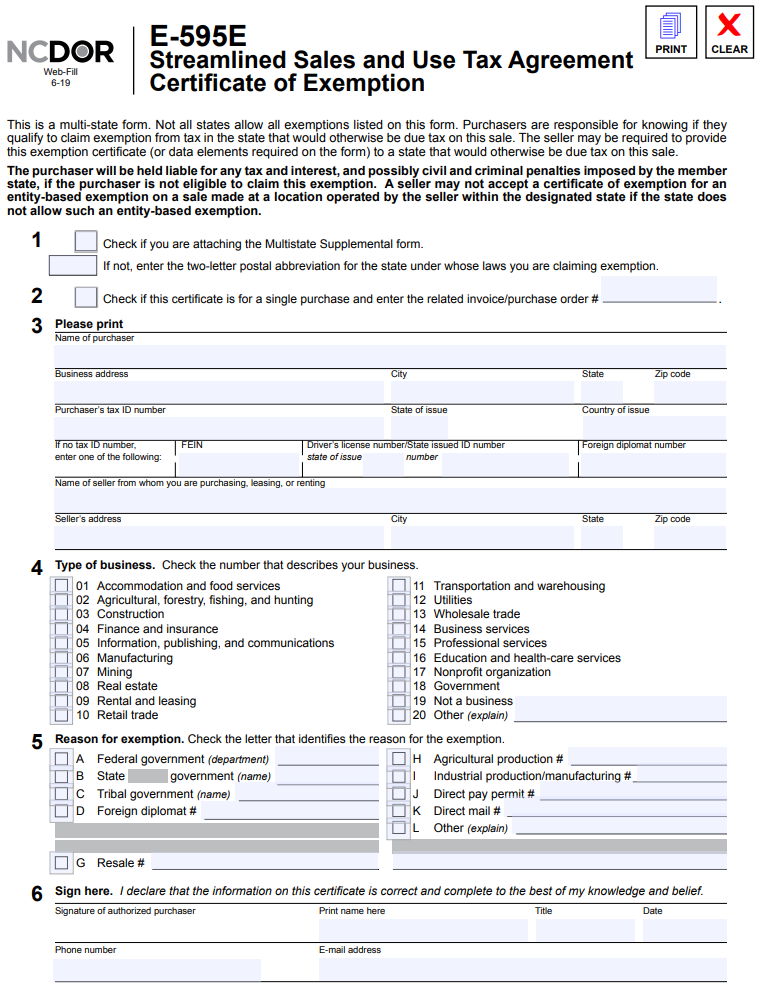
In California, tax-exempt status isn’t just a badge for nonprofits—it’s a compliance requirement with real financial consequences. Whether you're a startup claiming resale exemptions or a 501(c)(3) organization making purchases on behalf of your mission, validating your exemption isn’t optional. Failing to properly document or verify tax-exempt status during a transaction can trigger audits, penalties, and back-taxes from the California Department of Tax and Fee Administration (CDTFA).
What Exactly Is California Tax-Exempt Verification?
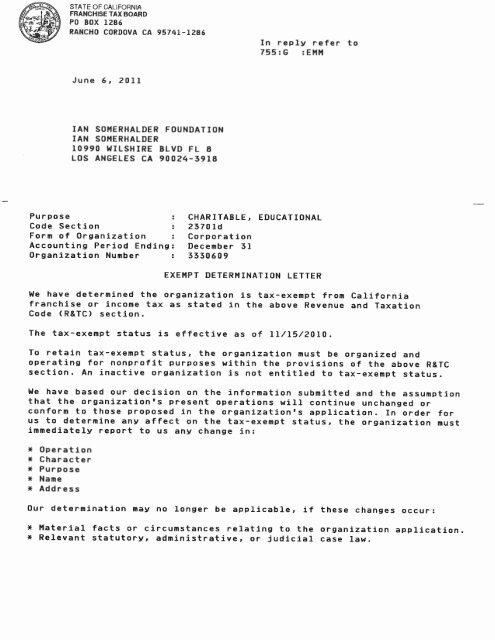
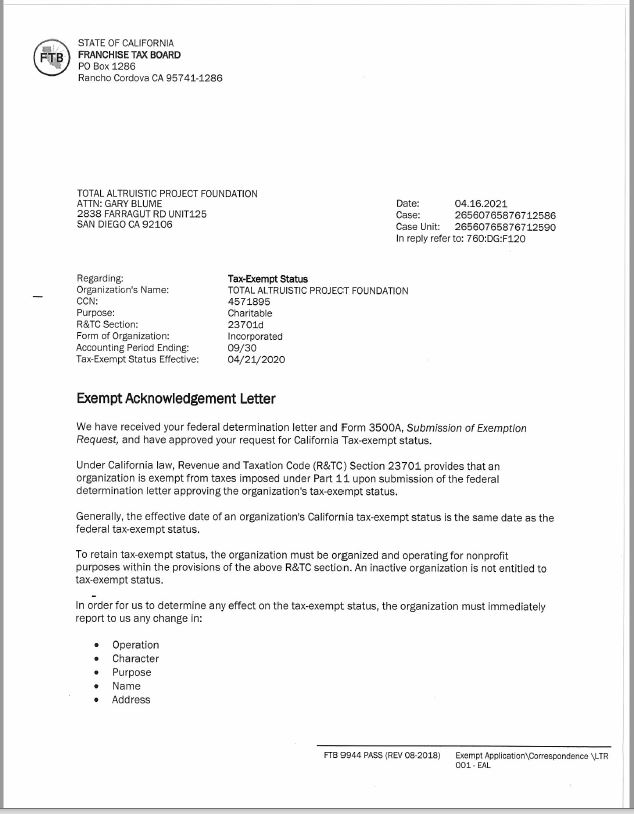
California tax-exempt verification is the process by which businesses or organizations confirm their eligibility to make purchases or sales without paying state sales and use tax. It hinges on two main pillars: holding valid federal 501(c)(3) or similar tax-exempt status, and possessing a current California seller’s permit (unless operating under specific reseller rules). But—and this is critical—simply having an IRS determination letter doesn’t automatically grant exemption in California. The CDTFA requires active registration and proper documentation at the point of sale.
Who Needs to Verify Tax-Exempt Status?
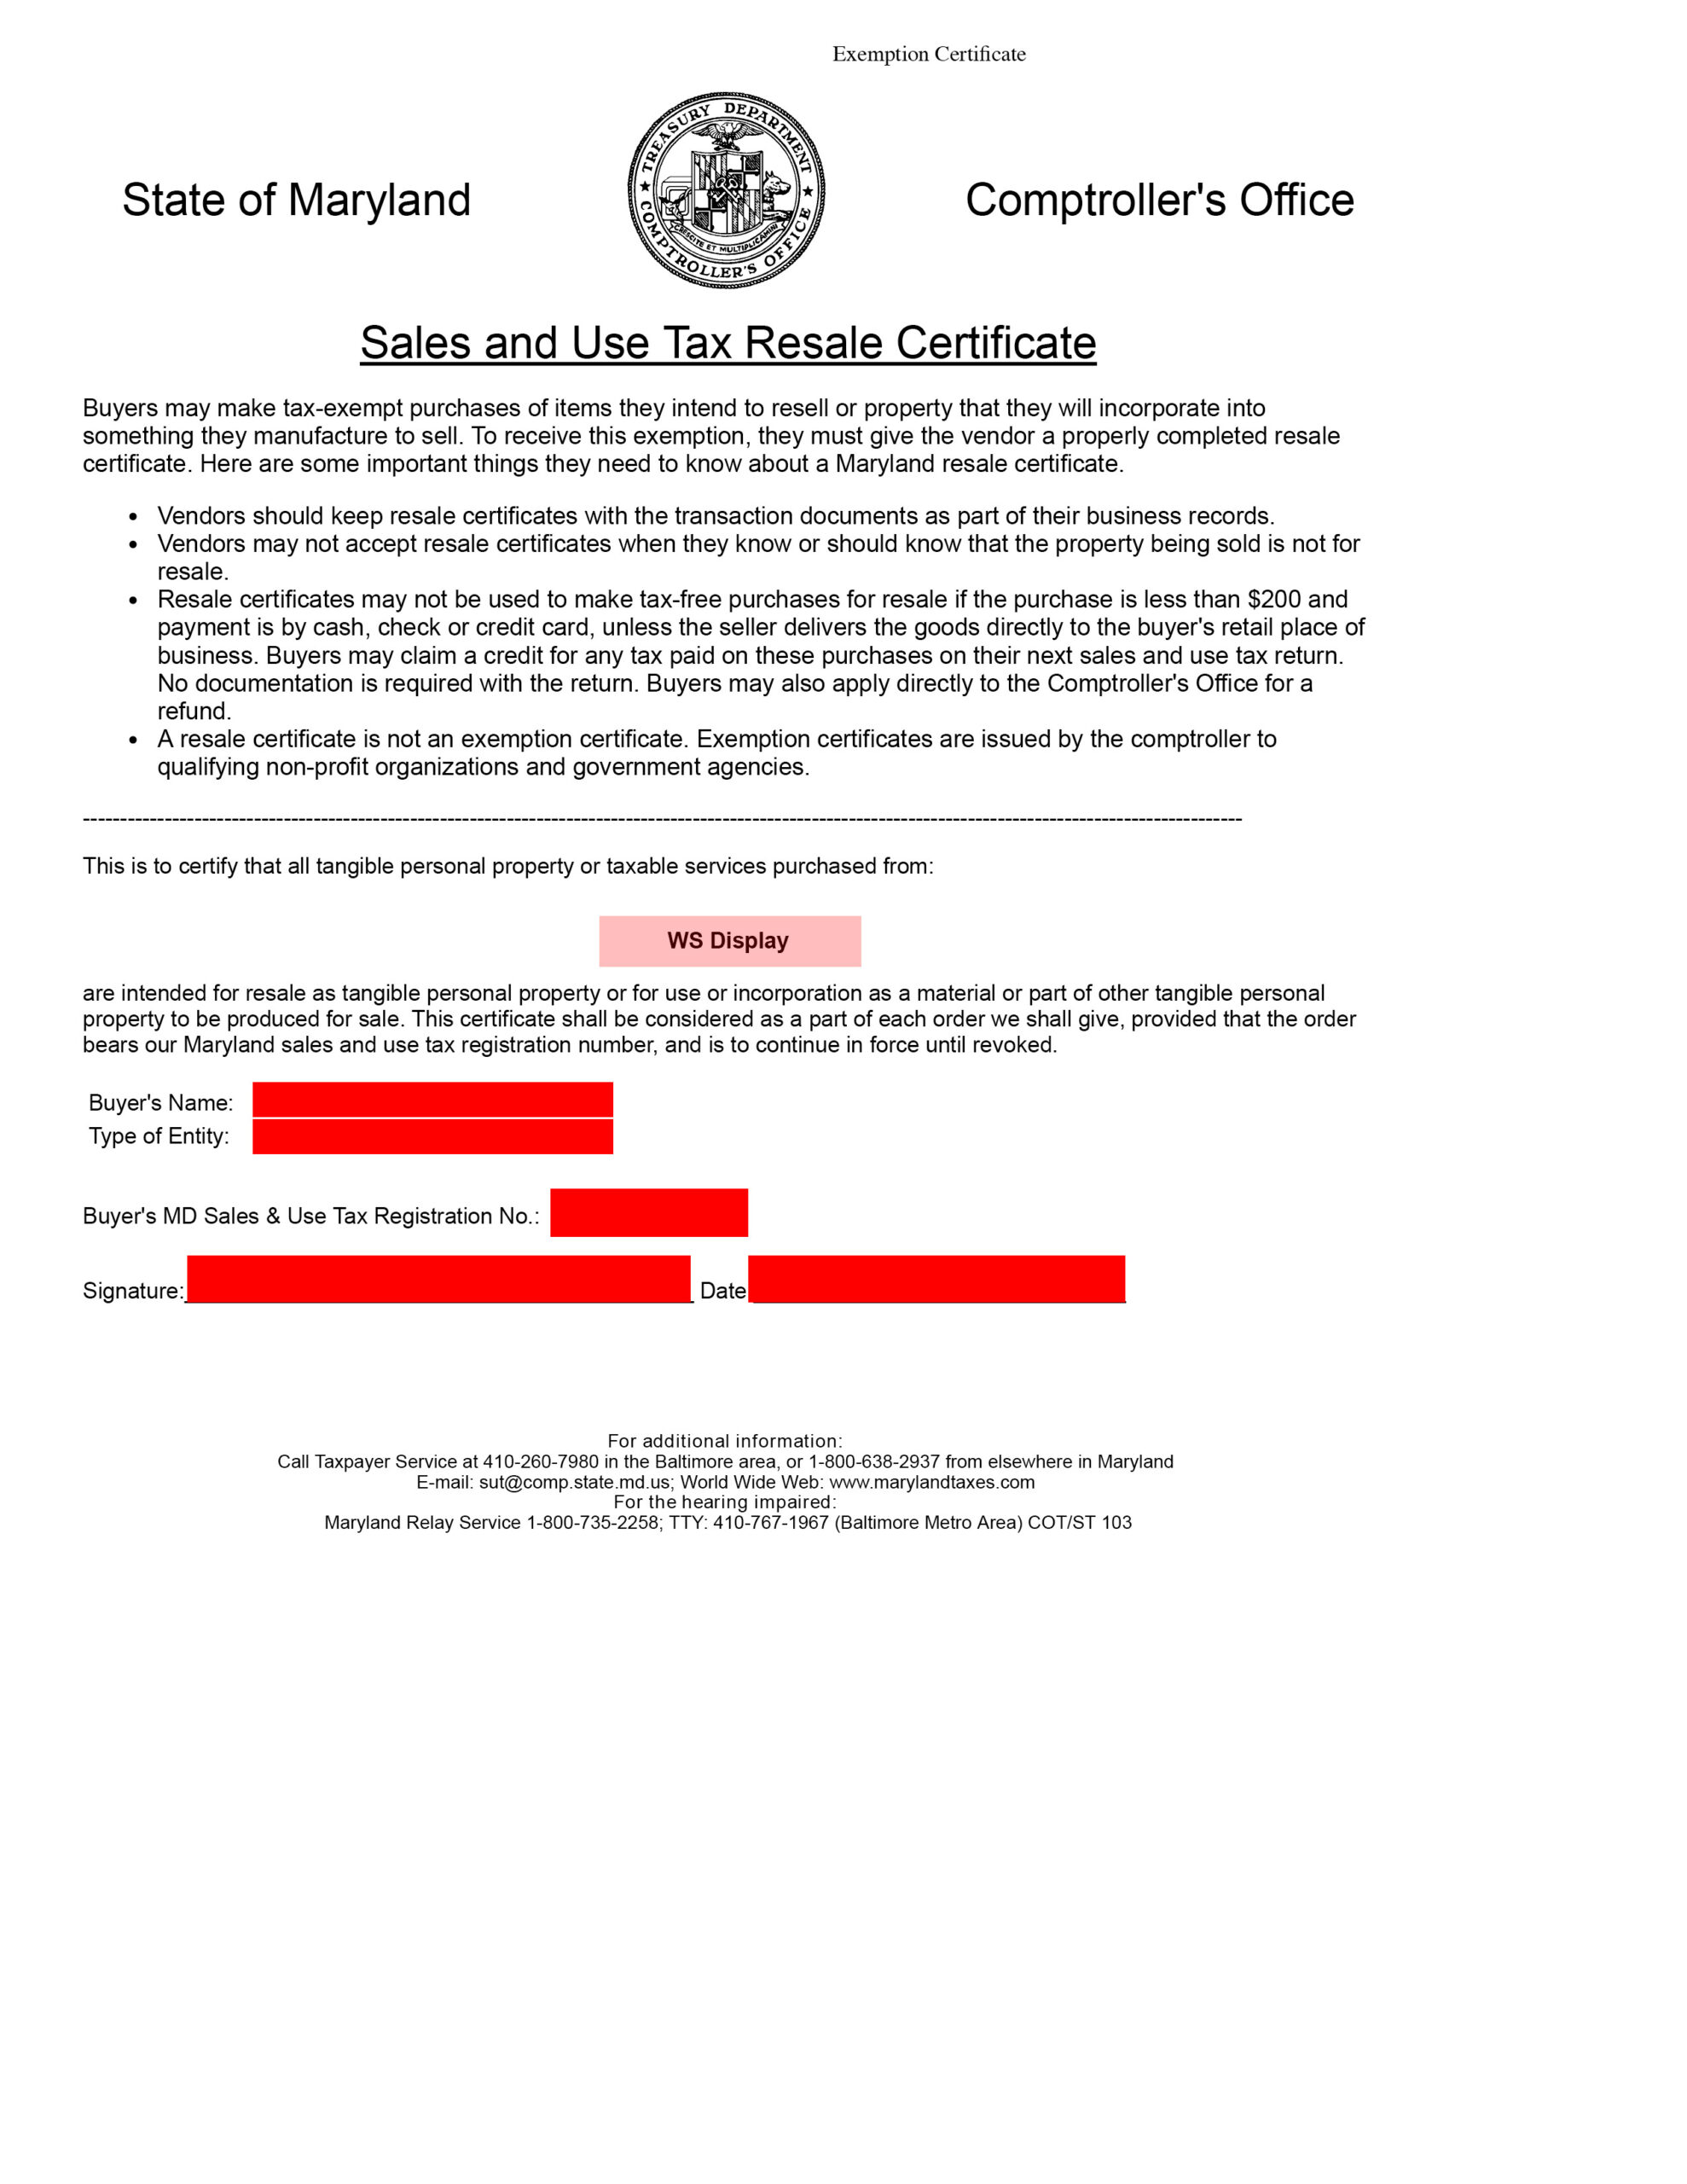
Not all exempt entities are treated equally under California law. Charitable organizations recognized by the IRS under Section 501(c)(3) must still register with the CDTFA to claim exemption on taxable sales they make. Additionally, certain government agencies, educational institutions, and religious organizations may qualify—but only if they follow the correct procedures. On the flip side, resellers buying inventory for resale use a different exemption form (BOE-230) and must maintain accurate records showing subsequent taxable sales.
Common Misconceptions That Lead to Liability
One frequent mistake is assuming that federal exemption equals state exemption. Another is thinking that once registered, no further action is needed. In reality, CDTFA periodically audits exempt organizations to ensure compliance. If your charitable org sells merchandise but doesn’t collect tax—and can’t prove its election—it owes that tax regardless of intent. Keep your BOE-230 form or federal exemption documentation readily available at every transaction point.
How to Properly Claim Exemption on Purchases
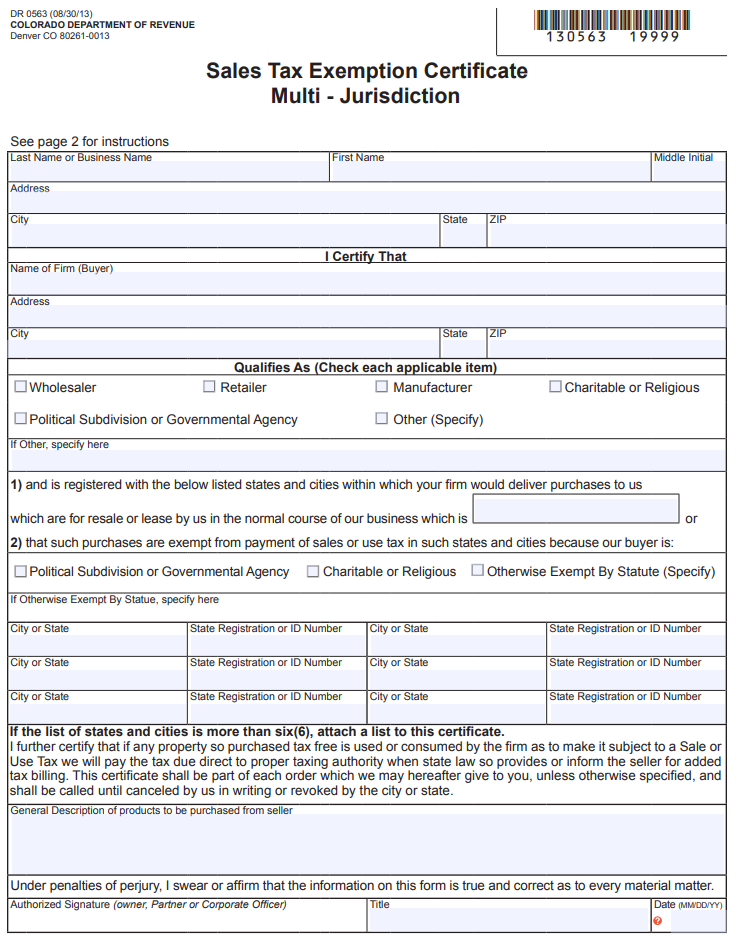
When making an exempt purchase, California requires you to provide the seller with a valid resale certificate (Form BOE-230) or a letter confirming your 501(c)(3) status if you're buying for nontaxable purposes. The certificate must include your California seller’s permit number (even if you’re buying for resale), a description of the items, and a statement asserting the exemption reason. Sellers who accept incomplete or outdated certificates share liability—so both parties have skin in the game.
Penalties for Noncompliance
The CDTFA doesn’t hand out warnings—it issues assessments. Unverified exemptions can result in full tax due plus interest, and in cases of negligence or fraud, penalty rates jump to 25% or even 75%. For nonprofits operating on thin margins, a single audit adjustment can derail programs. Maintaining clean records, updating registrations, and training staff on documentation requirements isn’t bureaucratic busywork—it’s essential risk management.

Best Practices for Maintaining Exempt Status
First, renew your seller’s permit on time through the CDTFA’s online portal. Second, store copies of all exemption certificates for at least four years—the standard audit lookback period. Third, designate a compliance point person who understands the difference between exempt sales and nontaxable purchases. Finally, review your sales channels annually: e-commerce platforms and third-party marketplaces often bypass traditional exemption flows, creating hidden exposure.California’s tax-exempt landscape rewards diligence and punishes assumption. Whether you're running a food bank procuring supplies or a retailer buying wholesale inventory, verified exemption protects your bottom line and preserves your organization’s credibility. Treat documentation not as paperwork, but as proof of your right to operate without undue tax burden.