Unraveling Microeconomics: Unit 1 Basic Economic Concepts Packet Answers
Welcome to the fascinating world of microeconomics! In this guide, we'll delve into the fundamental concepts that form the bedrock of this branch of economics. We'll explore these ideas in a clear, engaging manner, ensuring you grasp the basics with ease. So, let's embark on this learning journey together!
Understanding the Basics: What is Microeconomics?
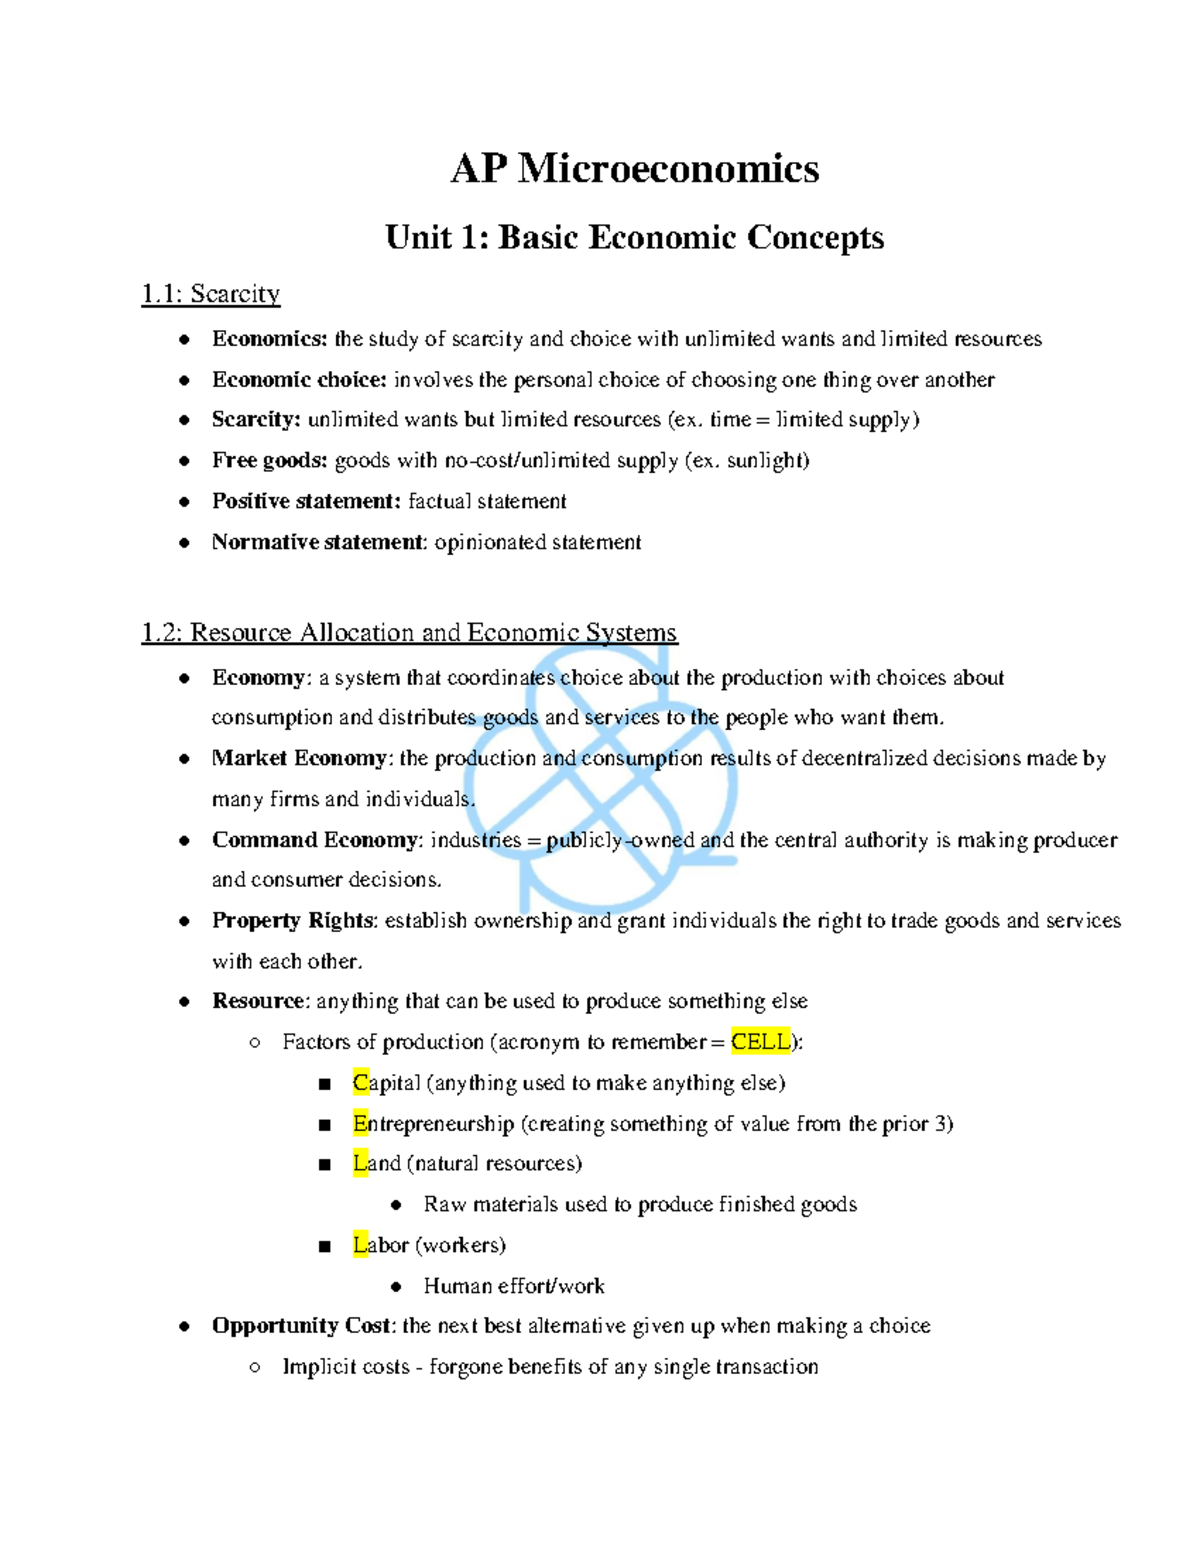
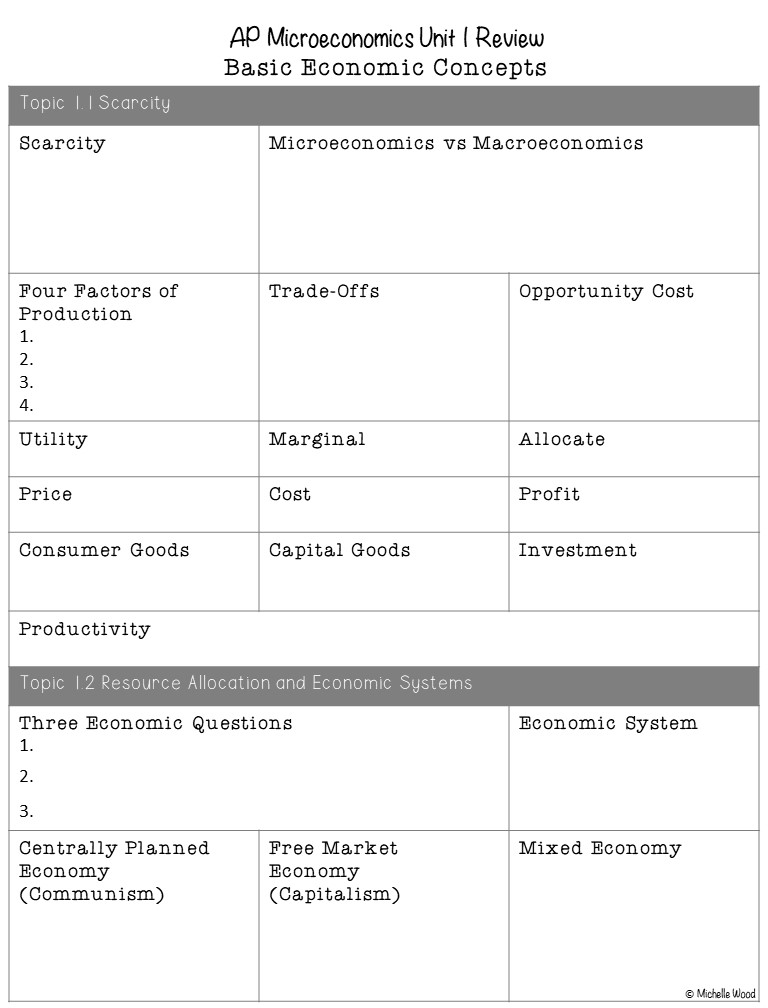
Microeconomics is the study of individual economic units, such as households and firms, and their interactions in specific markets. It focuses on the decisions made by these units and how they affect the allocation of scarce resources. In essence, microeconomics is about understanding how individuals and businesses make choices and how these choices impact the economy.
Key Concepts in Microeconomics: A Comprehensive Overview
Scarcity and Choice
Scarcity is the fundamental problem of economics. It refers to the situation where human wants exceed the available resources. This scarcity forces us to make choices about how to allocate these resources. Every decision we make involves an opportunity cost - the value of the best alternative given up.

Supply and Demand
Supply and demand are the two most basic forces that determine the price and quantity of goods and services in an economy. The law of demand states that, all else being equal, as the price of a good increases, the quantity demanded decreases. Conversely, the law of supply states that, all else being equal, as the price of a good increases, the quantity supplied increases.
Markets and Market Equilibrium
A market is a mechanism that brings together buyers and sellers to facilitate the exchange of goods and services. The interaction of supply and demand in a market determines the market equilibrium - the point where the quantity supplied equals the quantity demanded. At this point, the market clears, meaning there are no shortages or surpluses.
Graphing Supply and Demand: A Visual Guide
Graphing supply and demand is a powerful tool that helps us visualize the interactions between buyers and sellers. Here's a simple breakdown:
- The horizontal axis represents the quantity of a good.
- The vertical axis represents the price of the good.
- The supply curve slopes upward from left to right, indicating that as the price increases, so does the quantity supplied.
- The demand curve slopes downward from left to right, indicating that as the price increases, the quantity demanded decreases.
| Price | Quantity Supplied | Quantity Demanded |
|---|---|---|
| $5 | 100 | 200 |
| $10 | 150 | 150 |
| $15 | 200 | 100 |
In this table, the equilibrium price and quantity are $10 and 150 units, respectively.
Shifts in Supply and Demand: Understanding Changes in Markets
Markets don't always stay in equilibrium. Changes in various factors can shift the supply and demand curves, leading to new equilibriums. For example, an increase in demand (like a sudden popularity of a product) shifts the demand curve to the right, leading to a higher equilibrium price and quantity.
Conclusion: Building a Strong Foundation in Microeconomics
Mastering the basic concepts in microeconomics is the first step towards understanding the complex world of economics. From scarcity and choice to supply and demand, these concepts provide a solid foundation upon which to build your economic knowledge. So, keep exploring, keep learning, and most importantly, keep asking questions!