The scoring system has also been critiqued as a form of classification to shape an individual's life-chancesa form of economic inequality.[10] Since the 1980s, neoliberal economic policy has created a correlation between the expansion of credit and a decline in social...
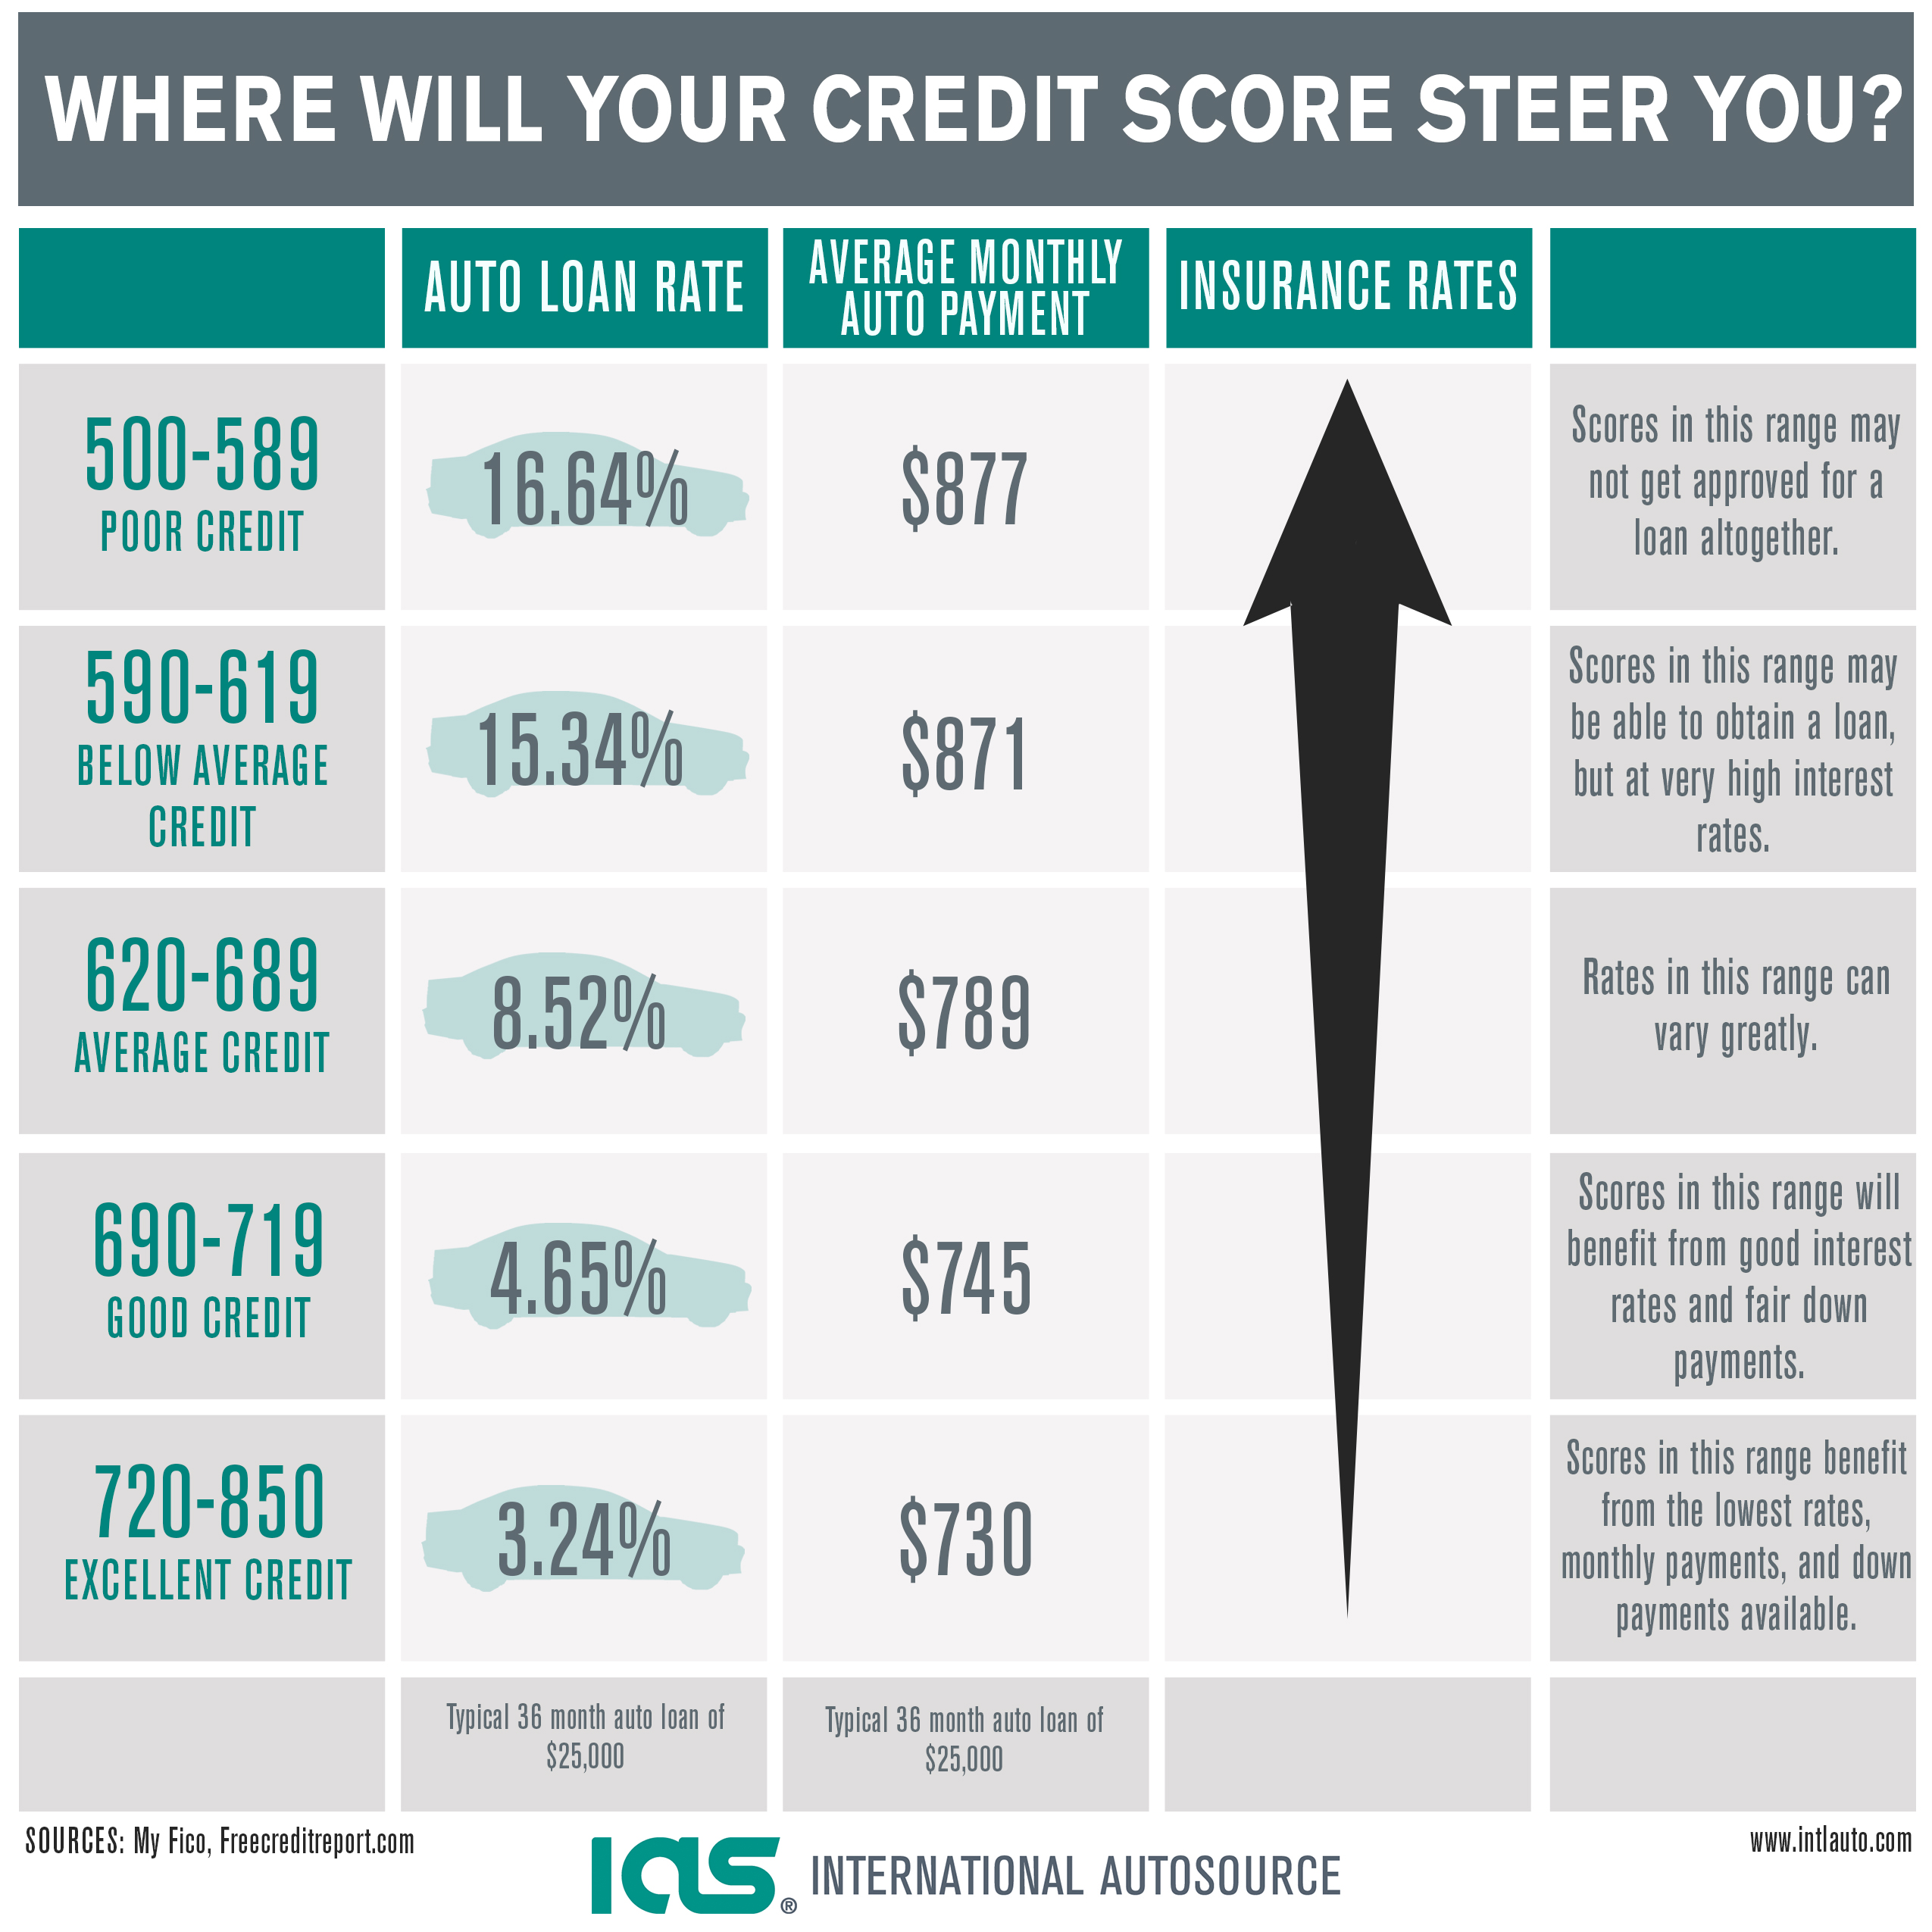
A credit score is a 3-digit number that reflects the likelihood that a consumer will repay his debts. With so many scoring models used to determine your credit score, your score can vary several points, depending on whose model is used and what type of business (department store? car dealership? bank?) is asking for it. The most recognized credit s... See full list on debt.org Credit scoring models are statistical analyses used by credit bureaus that evaluate your worthiness to receive credit. The agencies select statistical characteristics found in a persons credit payment patterns, analyze them and come up with a credit score. Scoring calculations are based on payment record, frequency of payments, amount of debts, cr... See full list on debt.org The FICO scoring model is an algorithm that produces what is considered the most reliable credit scores. About 90% of lenders use FICOs model to evaluate candidates for credit. FICO has been around since 1989 and there have been numerous revisions over the last three decades to take into account the changing factors that determine an accurate cred... See full list on debt.org While FICO tweaks the weight of various factors based on evolving economic realities, there remain five base factors in every credit score model. See full list on debt.org The VantageScore model was introduced in 2006 when the three major credit reporting bureaus Experian, Equifax and TransUnion decided to offer FICO some competition in the credit score business. The VantageScore model looks at familiar data things like paying on time, keeping credit card balances low, avoiding new credit obligations, bank acco... See full list on debt.org Outside of the conventional and well-known outlets, there are several other credit scoring models. TransRisk Its based on data from TransUnion and determines an individuals risk on new accounts, instead of existing accounts. Because of that specialized nature, theres not much information available about the TransRisk score. Accordingly, it isn... See full list on debt.org FICO drills deeper into financial data and helps lenders predict how you will do with specific types of loans, such as a mortgage or auto loan or credit cards. The three major credit bureaus that provide data to FICO all want industry-specific scores as well. Experian and Equifax provide 16 different FICO credit scores to lenders, while TransUnion ... See full list on debt.org Companies that develop scoring models prefer to keep details of the models behind closed doors because they consider them privately held and because they make money by selling results of the models. However, given the information that banks and credit card companies ask on their applications, it is not difficult to interpret some factors that weigh... See full list on debt.org Credit scoring models were first utilized in the credit industry more than 50 years ago. They were developed as a way to determine a repeatable, workable methodology in administering and underwriting credit debt, residential mortgages, credit cards and indirect and direct consumer installment loans. Early models were based on a greater degree of su... See full list on debt.org Speed is the major benefit to consumers of having credit scoring models. Lenders can evaluate thousands of applications quickly and impartially. Decisions on mortgages, car loans or extended limits on credit cards can be handled in days or even minutes. In fact, the consistency of data in scoring models allows for financial statements, credit ratin... See full list on debt.org CreditVision Score leverages the power of trended data, such as change in slope of consumer balances, revolving transacting history on Card trades, behavior of excess payment, part payment on all trades, velocity of new loan uptake and payment ratios, as a continuous concept rather than discrete attributes over the last three years. This, in addition to the traditional credit attributes ... Mortgage Basics Credit Scoring Model Your credit score plays a key role in your financial life, influencing everything from mortgage rates to loan approvals. But how is that score calculated? Credit scoring models are created using specific data points and statistical methods to determine how likely you are to repay your debts. In the world of finance, credit scoring models play a crucial role in assessing the creditworthiness of individuals and businesses. These models are designed to evaluate the risk associated with extending credit to borrowers, enabling lenders to make informed decisions about granting loans or... What is CreditVision score? CreditVision Score leverages the power of trended data, such as change in slope of consumer balances, revolving transacting history on Card trades, behavior of excess payment, part payment on all trades, velocity of new loan uptake and payment ratios, as a continuous concept rather than discrete attributes over the last three years. What is a CreditVision account management score? Designed with enriched consumer credit data elements, the CreditVision Account Management Score gives financial institutions an expanded view of consumers. The score leverages new insights through CreditVision data including payment What is a credit scoring model? By including these elements in someones credit history, a subjective judgment is given more weight in determining the credit score rating scale. Credit scoring models are used to help evaluate the creditworthiness of consumers. Learn about FICO, VantageScore and other scoring models. What is a CreditVision risk score? The score leverages new insights through CreditVision data including payment ratios, duration of balances, directional changes in balances and shifts in utilization levelsdata not incorporated into traditional risk scores. As a result, its a risk score thats better at predicting future consumer performance. Learn about credit scoring models, including FICO, VantageScore, and more. Discover how these credit scoring models impact your financial health.

This particular example perfectly highlights why Vision Credit Scoring Systems is so captivating.
Implementing these recommendations will enhance fairness, security, and transparency in AI-driven financial decision-making, ensuring compliance with evolving regulatory frameworks and fostering trust in automated credit scoring systems.


.png?itok=1Zi6jLnN "Credit Score | Visions Federal Credit Union")