Prepaid Cards vs Credit Cards: Which is Best for You?
Read about Prepaid Cards vs Credit Cards: Which is Best for You? on Laight Ideas.
When evaluating payment solutions for everyday expenses or project expenses, the choice between a p card and a credit card often creates confusion. While both tools facilitate transactions without immediate cash outflow, their underlying mechanics, target users, and fiscal oversight differ significantly. Understanding these distinctions is vital for finance teams, department managers, and individual cardholders who need to manage expenses effectively without compromising operational agility.
Defining the Purchase Card (P‑Card)
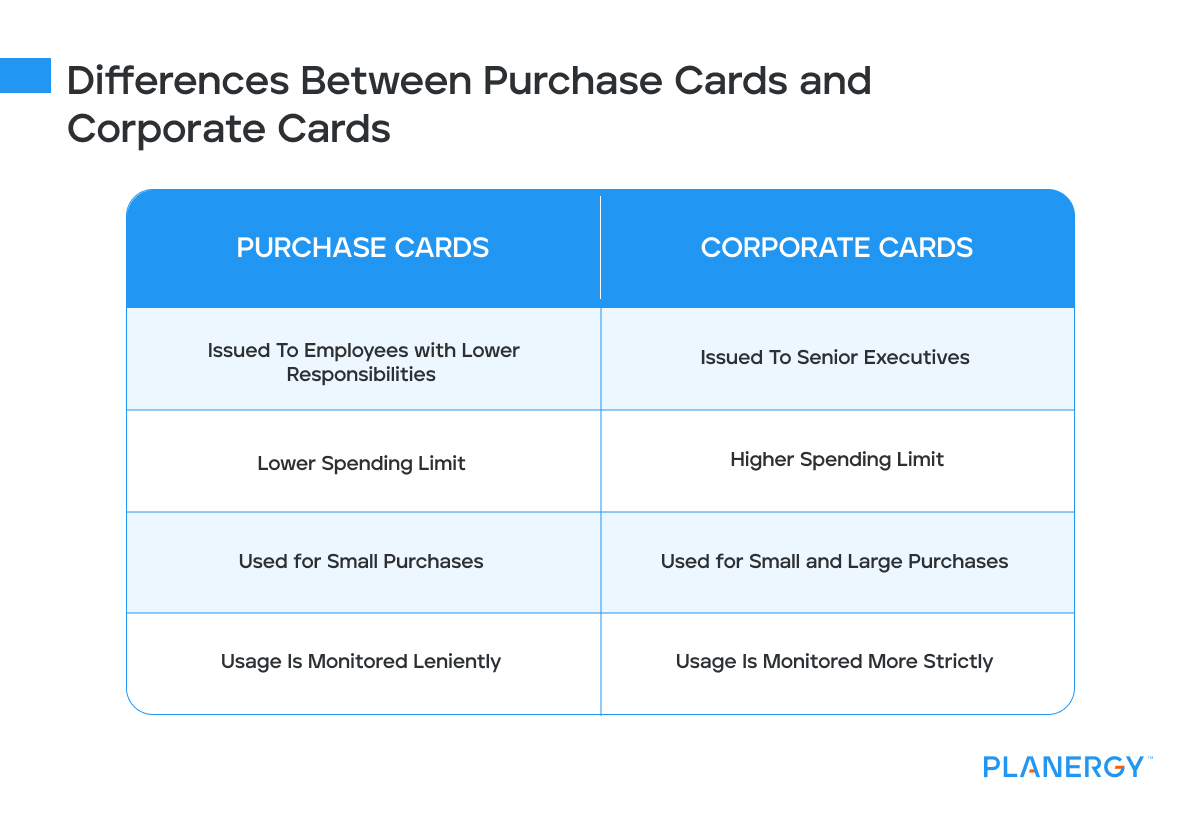
A purchase card, frequently abbreviated as a p card, is a specialized subset of corporate card designed primarily for streamlined, low‑value procurement. Unlike a general corporate card, which might be used for travel or client entertainment, a p card is typically restricted to purchases of goods and services necessary for the operation of a specific department or project. The defining characteristic is the emphasis on streamlined reconciliation, allowing finance teams to bypass traditional, invoice‑based payment cycles for small, routine acquisitions.
Core Functional Differences
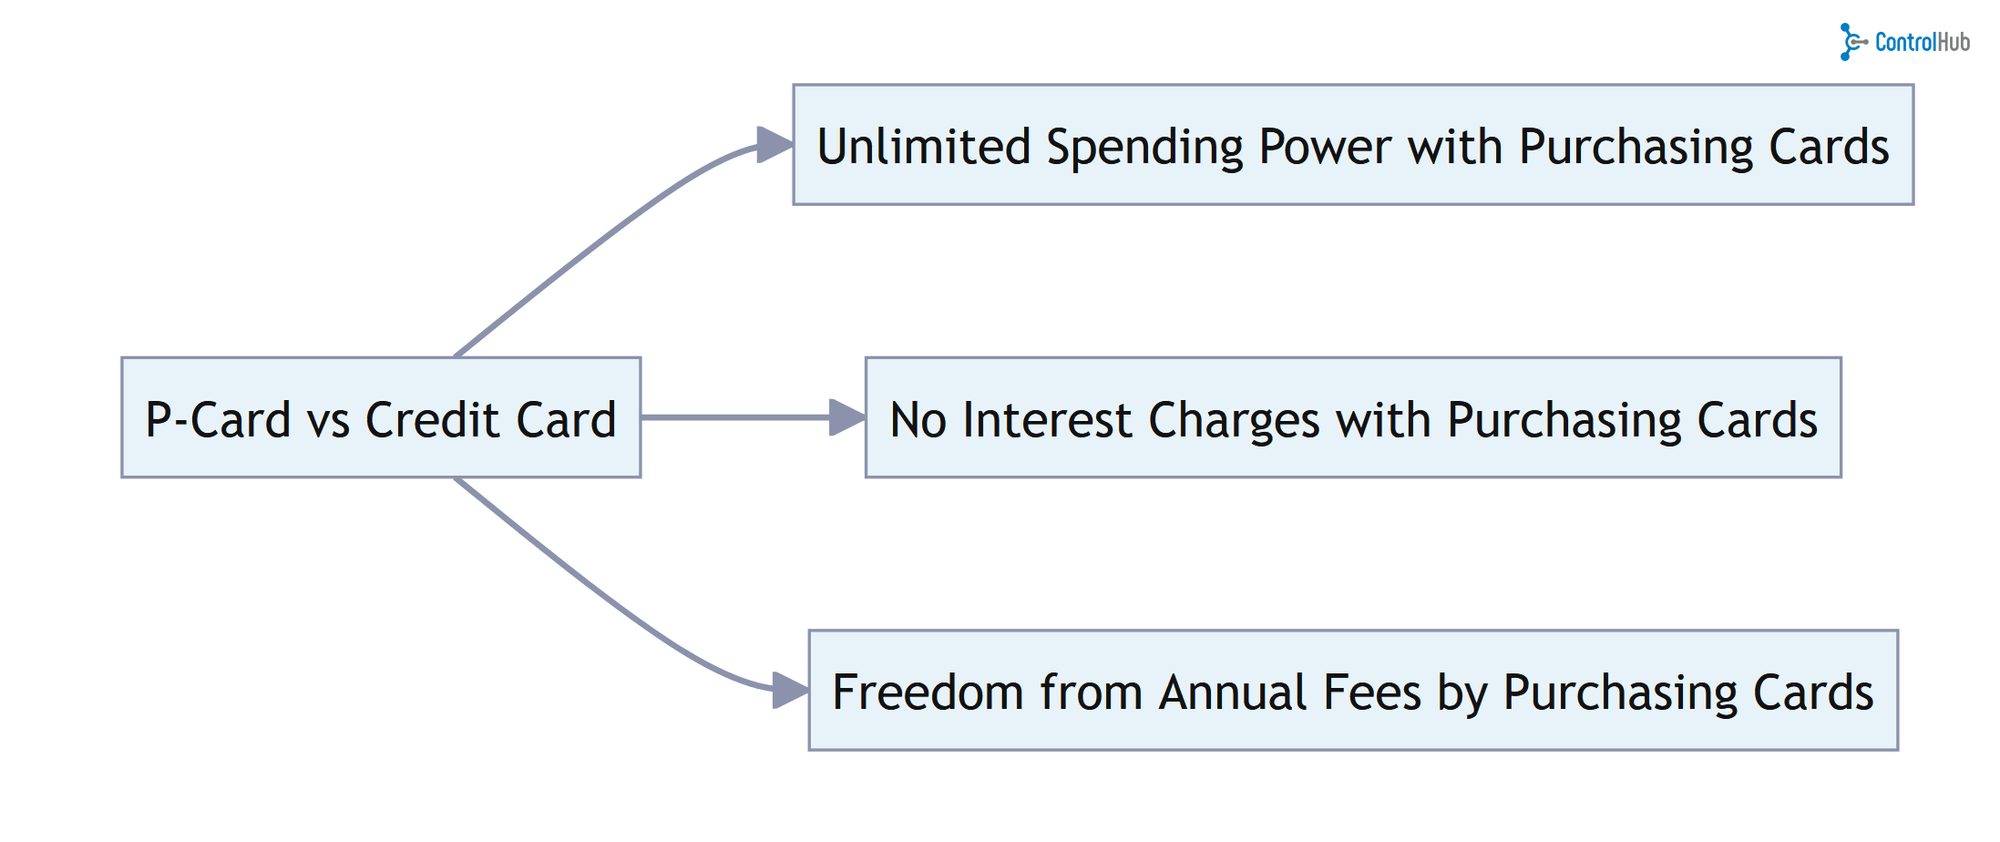
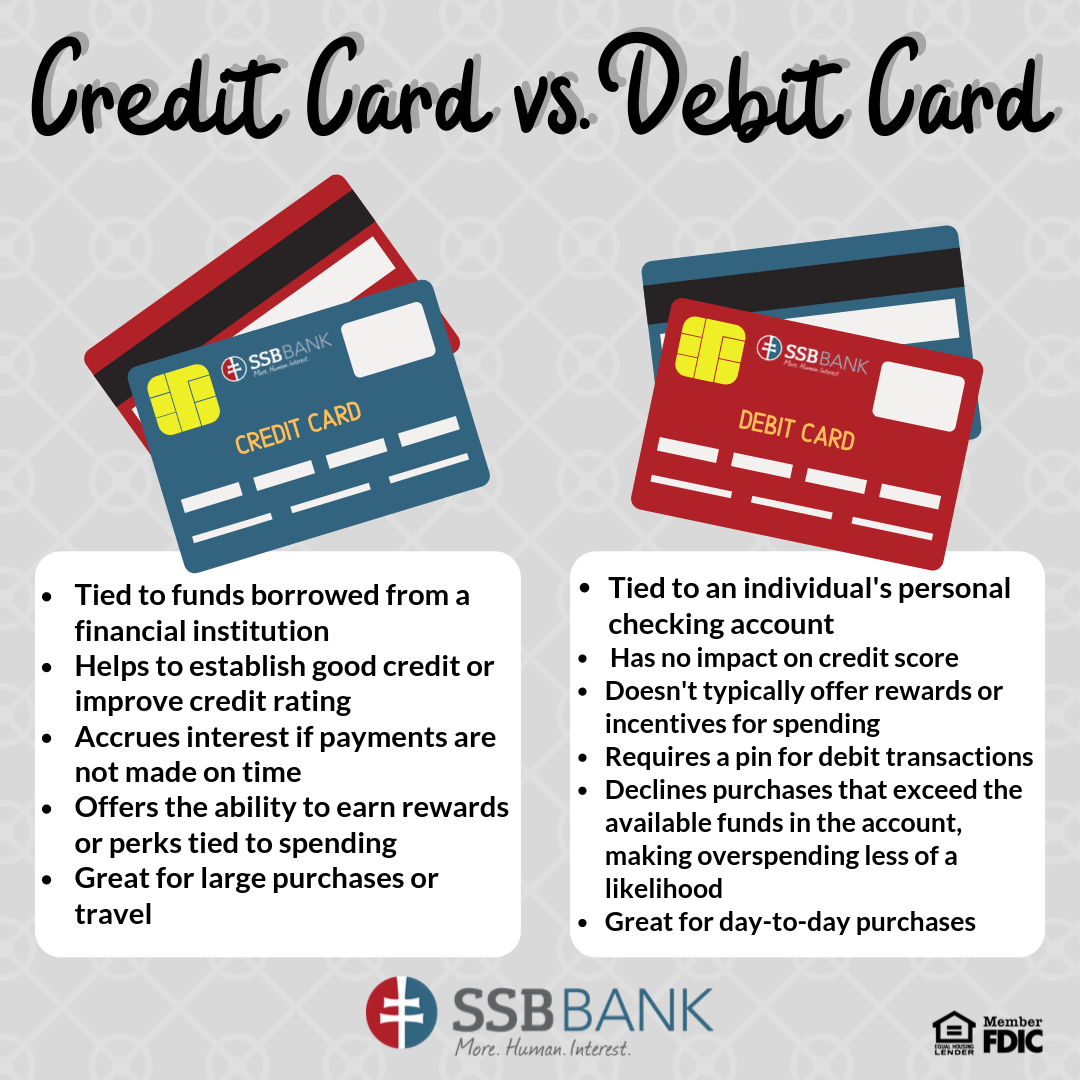
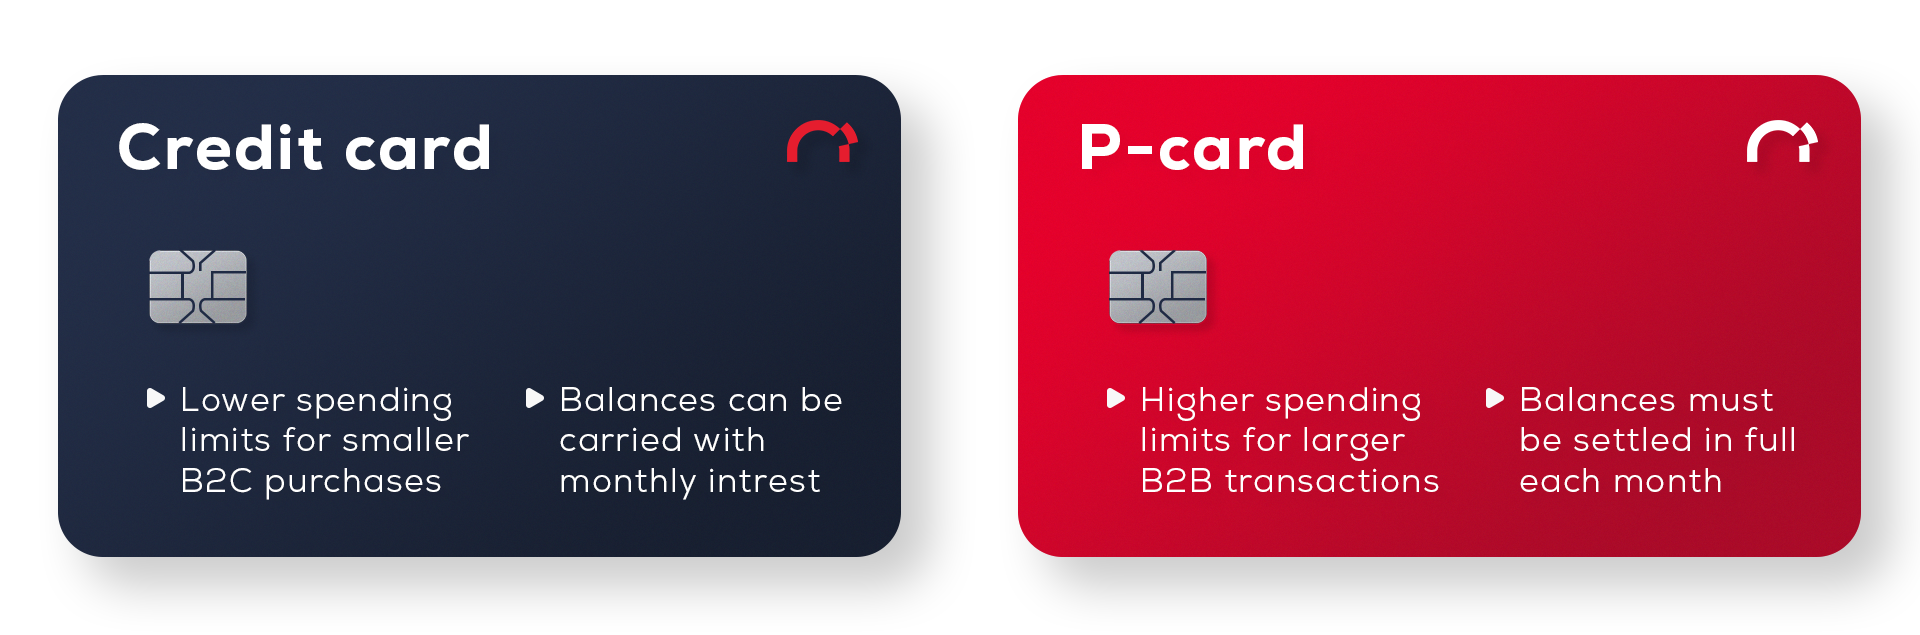
The fundamental divergence lies in their payment structure and credit extension. A credit card extends a line of credit from a bank, allowing the holder to carry a balance from month to month, often at interest if the statement is not paid in full. Conversely, a p card is usually tied to a specific bank account or a predetermined budget limit set by the company. This means the p card functions more like a digital check or a debit instrument, where the available funds must cover the transaction, thus inherently limiting the risk of revolving debt accumulation.
Credit Cards: Consumer Focus
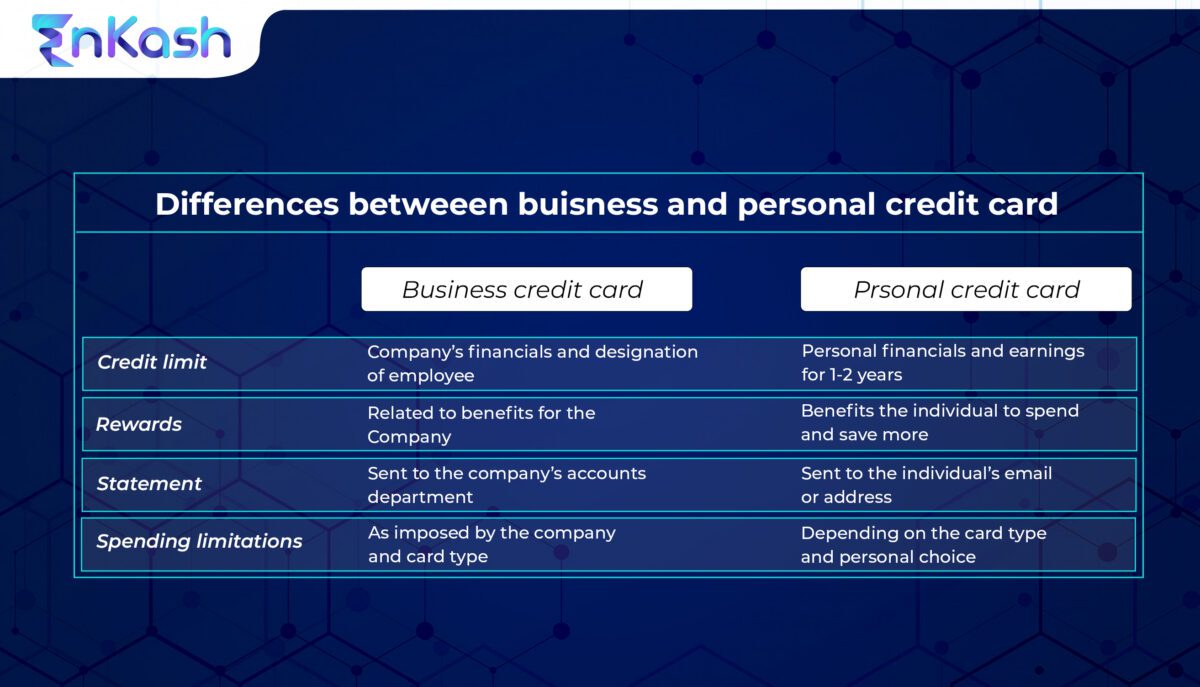
Credit cards are engineered for consumer flexibility and consumer credit building. They offer rewards programs, extended warranties, and robust fraud protection that target individual spending habits. The grace period on a credit card allows users to enjoy a interest‑free period if the balance is cleared promptly, making them financially advantageous for personal use when managed responsibly. However, this flexibility can lead to high‑interest debt if the balance is not managed with discipline.
P Cards: Enterprise Efficiency
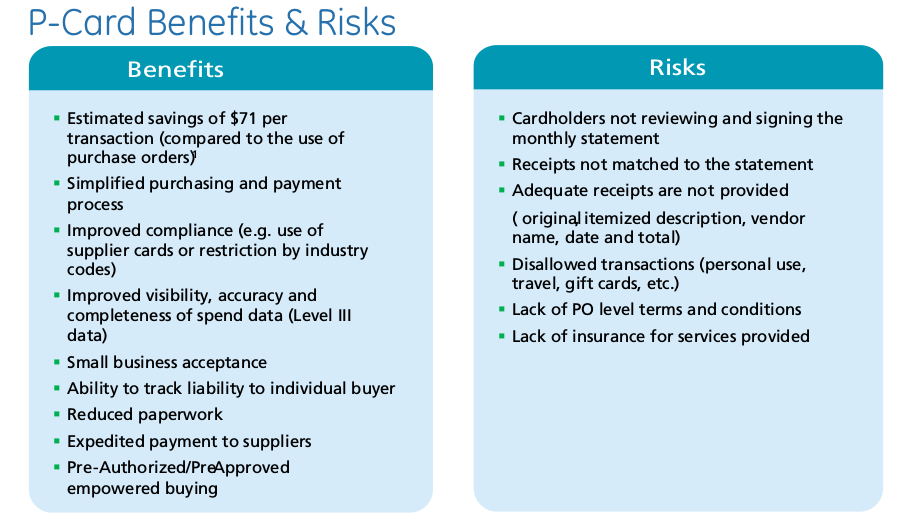
P cards are engineered for enterprise efficiency and strict financial governance. They are predominantly used by organizations to automate the payment of goods and services that do not warrant the overhead of a traditional purchasing order. Because a p card transaction often eliminates the need for manual invoicing, it reduces the administrative burden on accounts payable. This results in faster processing times, lower transaction costs, and improved visibility into departmental spending through detailed, real‑time reporting.
Security and Control Mechanisms
Security considerations vary significantly between the two instruments. Credit cards generally offer strong consumer-level fraud protection, with zero liability policies that protect the cardholder from unauthorized charges. P cards, however, provide institutional controls that are essential for corporate finance. Features such as purchase limits, single‑use virtual card numbers, and restrictions on merchant categories (e.g., blocking gambling or entertainment sites) ensure that spending aligns strictly with company policy. This granular control minimizes the risk of maverick spending and duplicate payments.
Tax Implications and Reconciliation
Another critical area where p cards outperform standard credit cards is in the tax reconciliation process. Because p cards are designed to integrate directly with ERP systems like SAP or Oracle, every transaction is automatically matched to a cost center or project code. This simplifies the audit trail at the end of the fiscal year and ensures that expenses are correctly attributed to the responsible department. Credit cards, while useful, often require manual categorization and reconciliation, increasing the likelihood of errors during the close books process.
Choosing the Right Tool for the Job
The decision to issue a p card or rely on a credit card should be based on the specific need at hand. Organizations seeking to optimize operational expenditures and enforce strict budget adherence will find the p card to be an indispensable tool. Conversely, individuals looking to build credit history, access consumer protections, or manage personal cash flow will find the versatility of a credit card to be the superior option. Understanding the unique strengths of each ensures that the payment method aligns with the financial strategy and compliance requirements of the user.