Creating an amortization schedule is a fundamental step for anyone managing a loan, whether they are a homeowner with a mortgage, a business owner with commercial debt, or an individual planning personal finances. This structured table provides a clear breakdown of each payment, showing exactly how much goes toward reducing the principal balance versus paying interest. By understanding how to build and read this schedule, you gain transparency into the true cost of borrowing and the path to becoming debt-free.
At its core, an amortization schedule is a timeline of payments that details the periodic installments required to pay off a loan by its maturity date. Unlike a simple interest calculation, this schedule accounts for the declining balance of the loan, meaning the interest portion of each payment decreases over time while the principal portion increases. This dynamic creates a predictable pattern that allows borrowers to see the exact financial trajectory of their debt from the first payment to the final one.
Understanding the Mechanics of Amortization
The foundation of any schedule lies in the mathematical process of amortization itself, which distributes loan payments over a specific period. Each payment is calculated to cover the interest accrued during the period plus a portion of the outstanding principal. In the early stages of the loan term, a significant portion of the payment is allocated to interest because the principal balance is at its highest. As the principal decreases with every payment, the interest charge shrinks, allowing a larger share of the subsequent payments to directly reduce the loan balance.
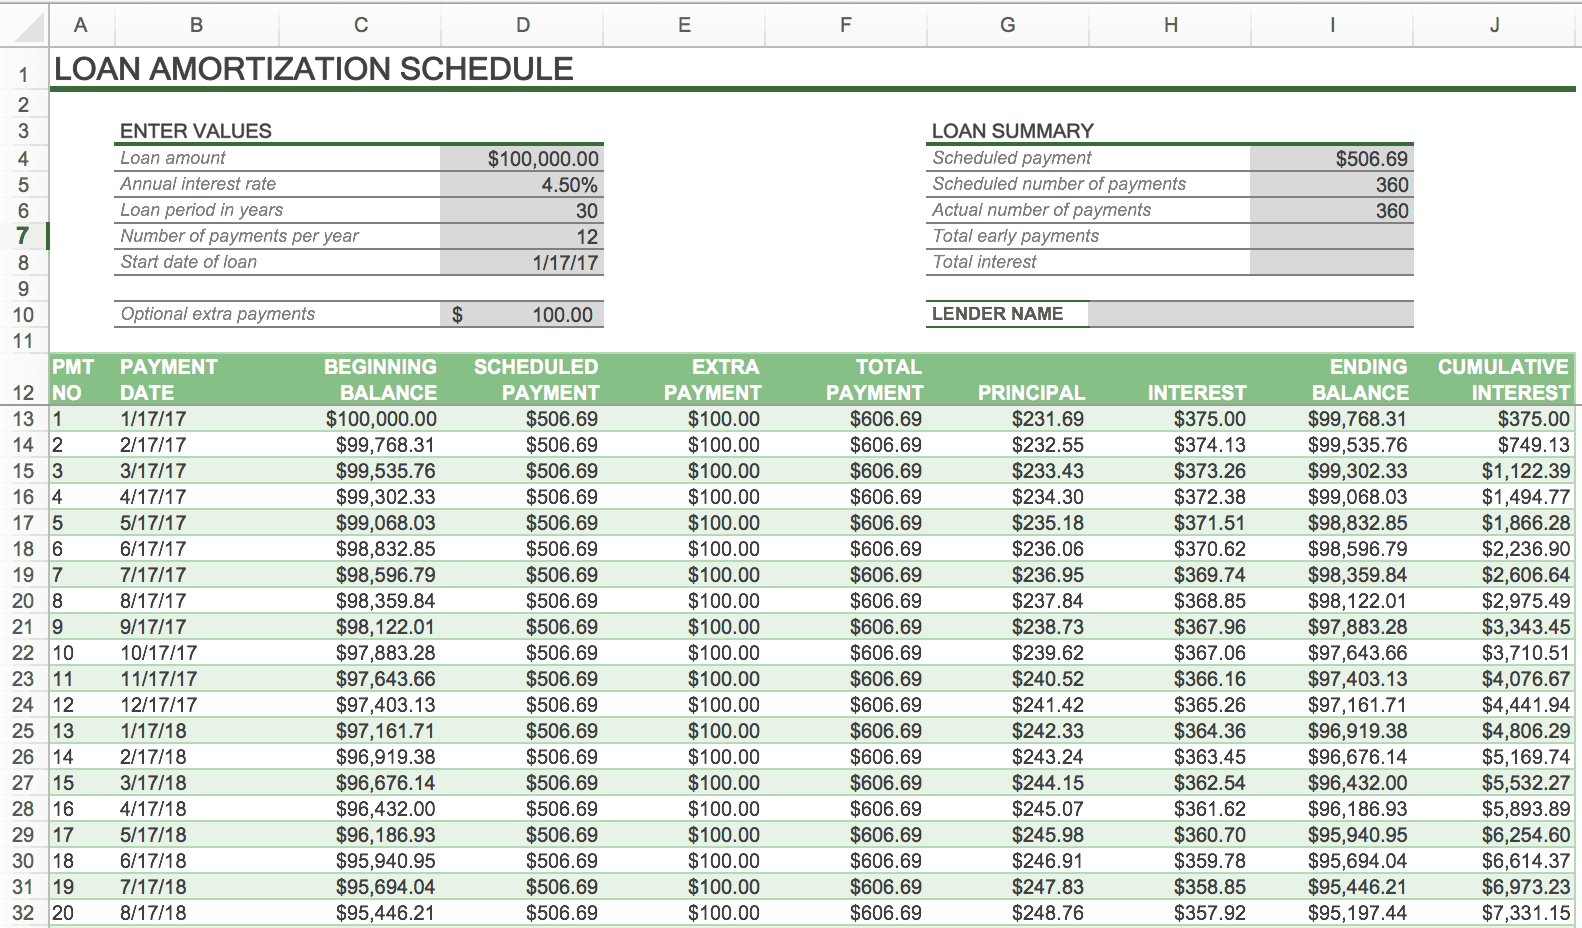
Key Components of a Payment
To construct the schedule accurately, you must identify the core variables of the loan. These elements dictate the structure of the entire repayment plan and determine the financial burden on the borrower. The interaction between these components creates the amortizing effect that defines the schedule.
- Principal: The original sum of money borrowed.
- Interest Rate: The annual percentage rate (APR) charged on the principal.
- Term: The total duration of the loan, usually expressed in years or months.
- Payment Frequency: How often payments are made, such as monthly, bi-weekly, or quarterly.
Step-by-Step Creation Process
Building the schedule manually involves a systematic calculation for every period of the loan. While modern software and online calculators perform this instantly, doing it by hand provides a deep insight into the financial mechanics. The process transforms static loan data into a dynamic map of repayment.
Start by determining the periodic payment amount using the standard amortization formula. Once the payment is fixed, calculate the interest for the first period by multiplying the beginning balance by the periodic interest rate. Subtract the interest from the total payment to determine the principal reduction. Finally, subtract the principal reduction from the starting balance to find the new ending balance, which becomes the starting point for the next period.
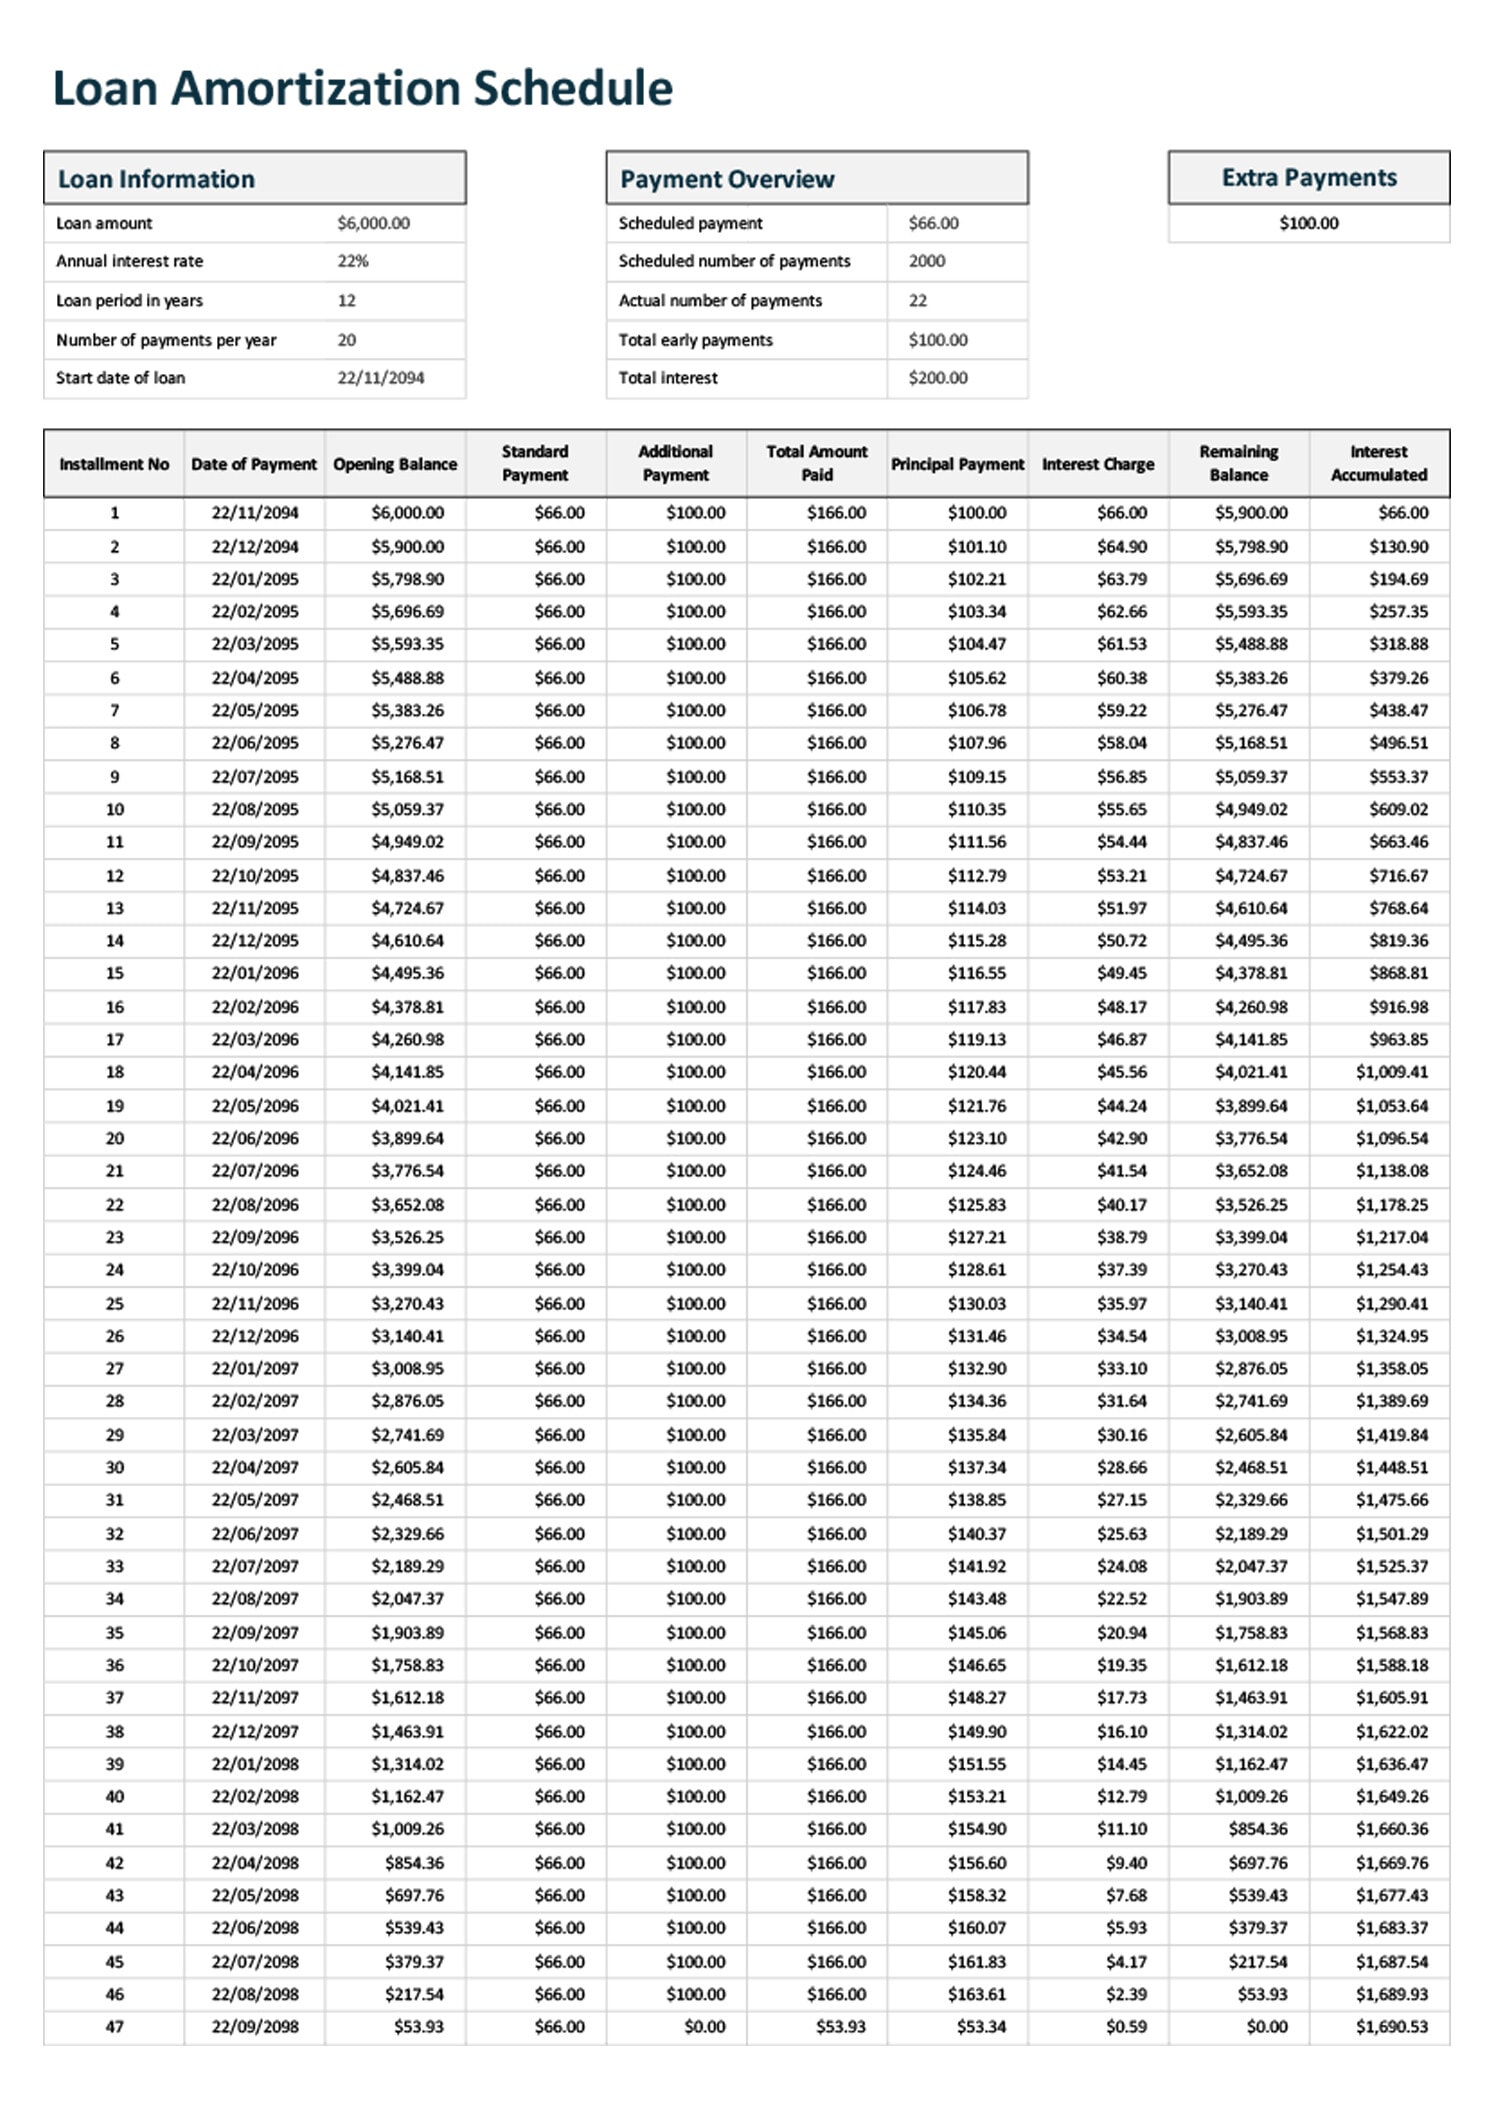
Structuring the Data in a Table
To visualize the progression effectively, the data is usually organized in a tabular format. A well-structured table transforms complex numbers into an easily digestible format, allowing for quick analysis of the loan's progression. This structure typically spans the entire duration of the loan, row by row.
| Payment # | Beginning Balance | Payment | Interest | Principal | Ending Balance |
|---|---|---|---|---|---|
| 1 | $100,000.00 | $536.82 | $500.00 | $36.82 | $99,963.18 |
| 2 | $99,963.18 | $536.82 | $499.82 | $37.00 | $99,926.18 |
Strategic Benefits and Financial Insights
Beyond satisfying the requirement of making a payment, analyzing the schedule offers strategic advantages that can save significant money. Borrowers can identify the optimal point where refinancing becomes beneficial or determine the impact of making extra payments toward the principal. These adjustments shorten the loan term and reduce the total interest paid, turning a rigid contract into a flexible financial tool.
Furthermore, the schedule serves as a powerful communication tool between the borrower and the lender. It provides concrete evidence of how payments are being applied and helps to quickly identify any potential errors in interest calculation. By taking control of this document, individuals move from passive payers to active managers of their financial obligations, ensuring they retain every dollar of equity build-up.
Mortgage Amortization Schedule Excel Template
How to Make an Amortization Schedule in Excel: 7 Steps (with Templates ...
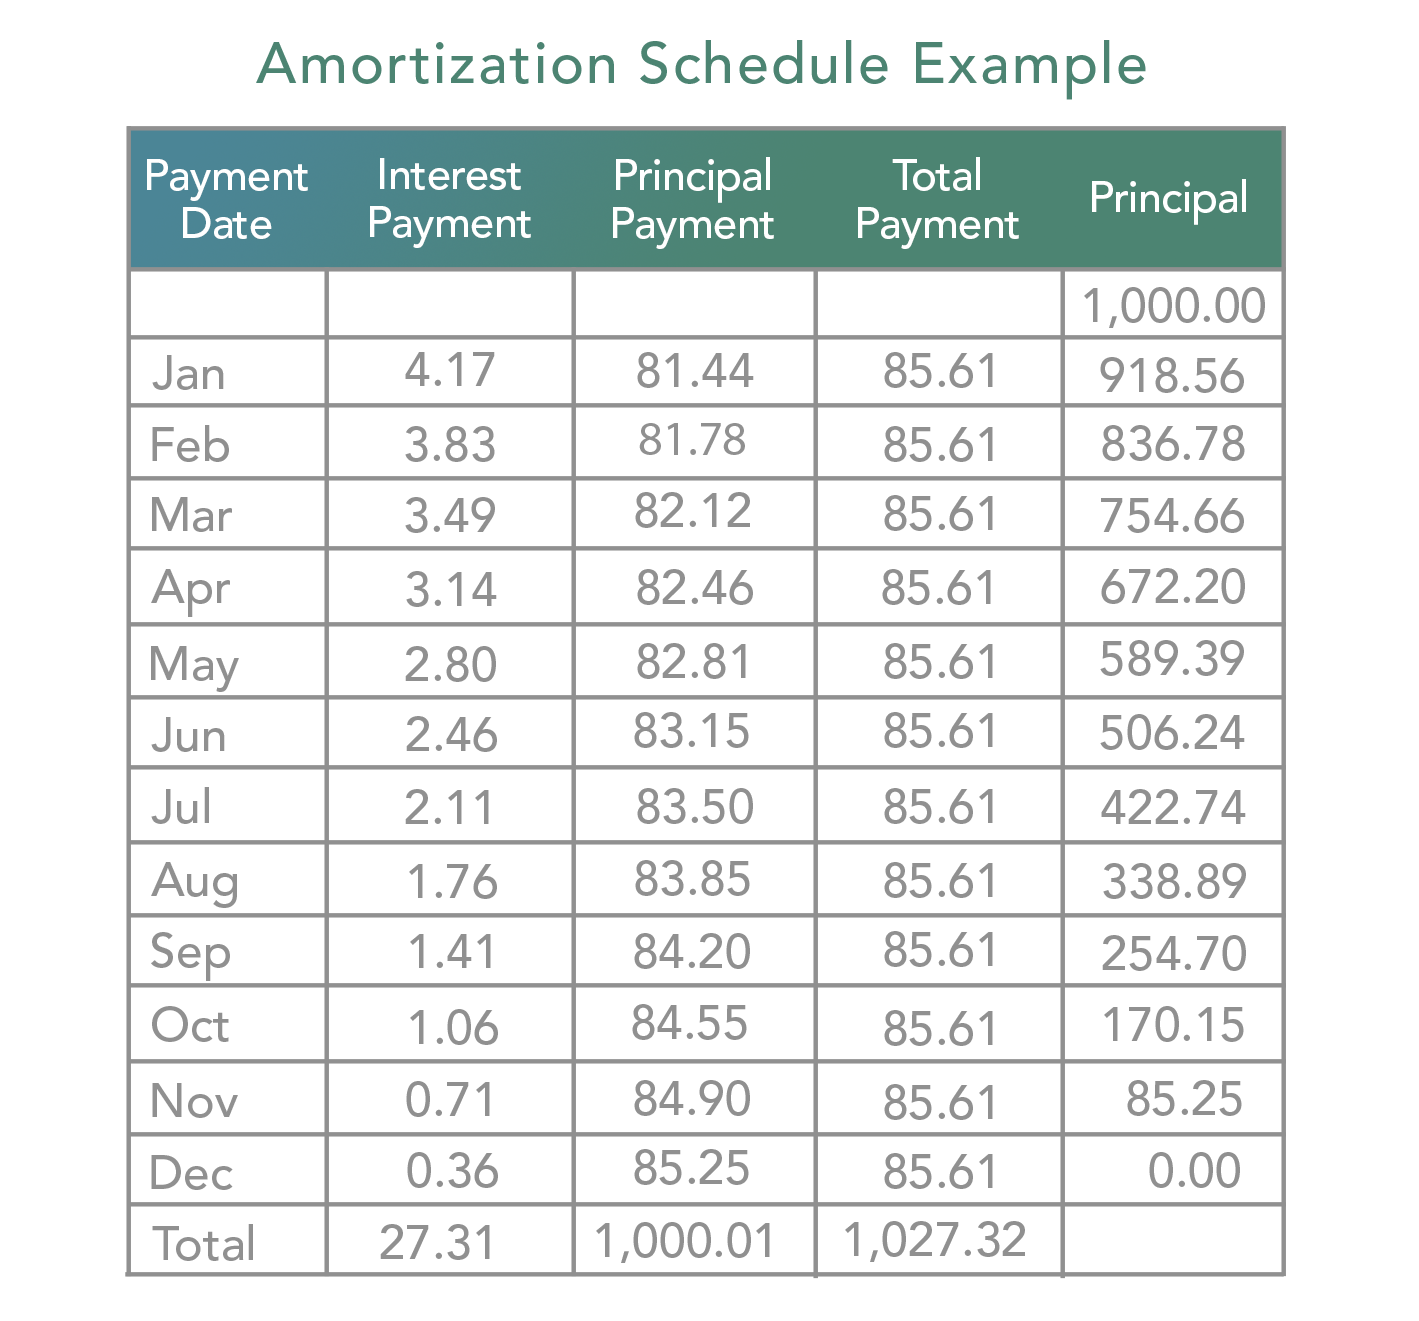
Amortization Schedule Definition & Example | InvestingAnswers

Weekly Amortization Schedule Excel at taruriahblog Blog
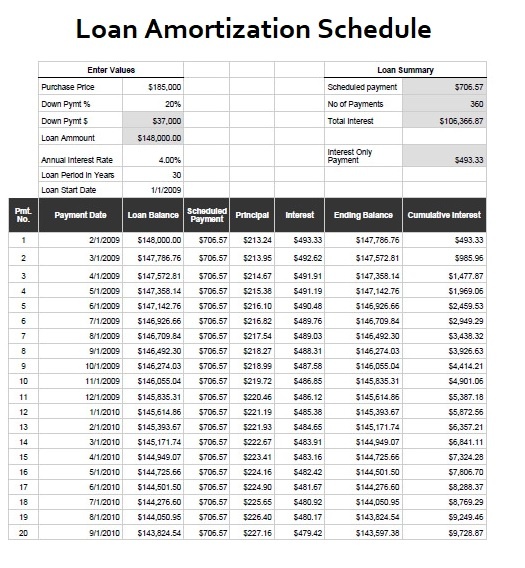
Amortization Schedule Template | Free Word Templates
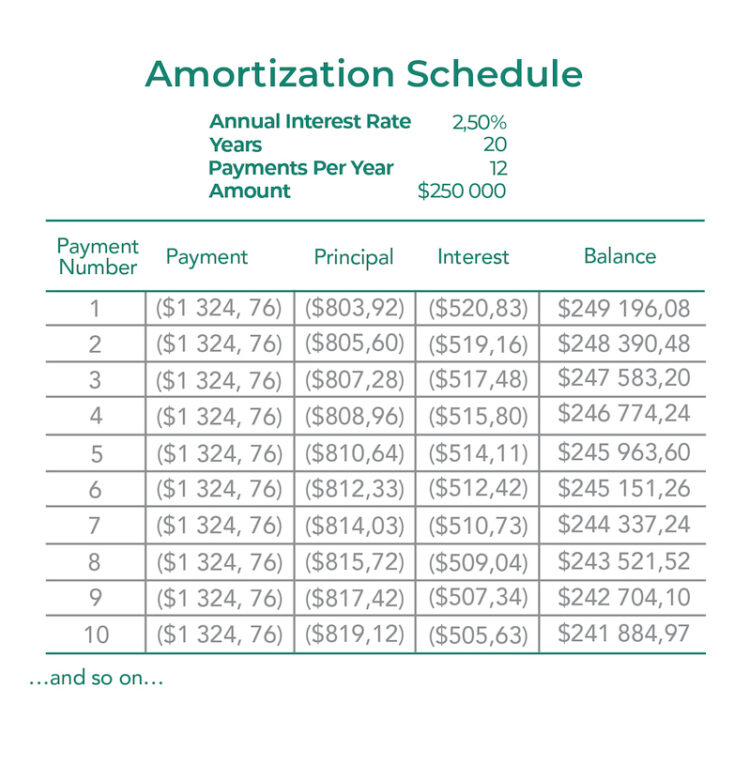
How To Create A Monthly Amortization Schedule In Excel - Design Talk

10 Free Amortization Schedule Templates in MS Word and MS Excel
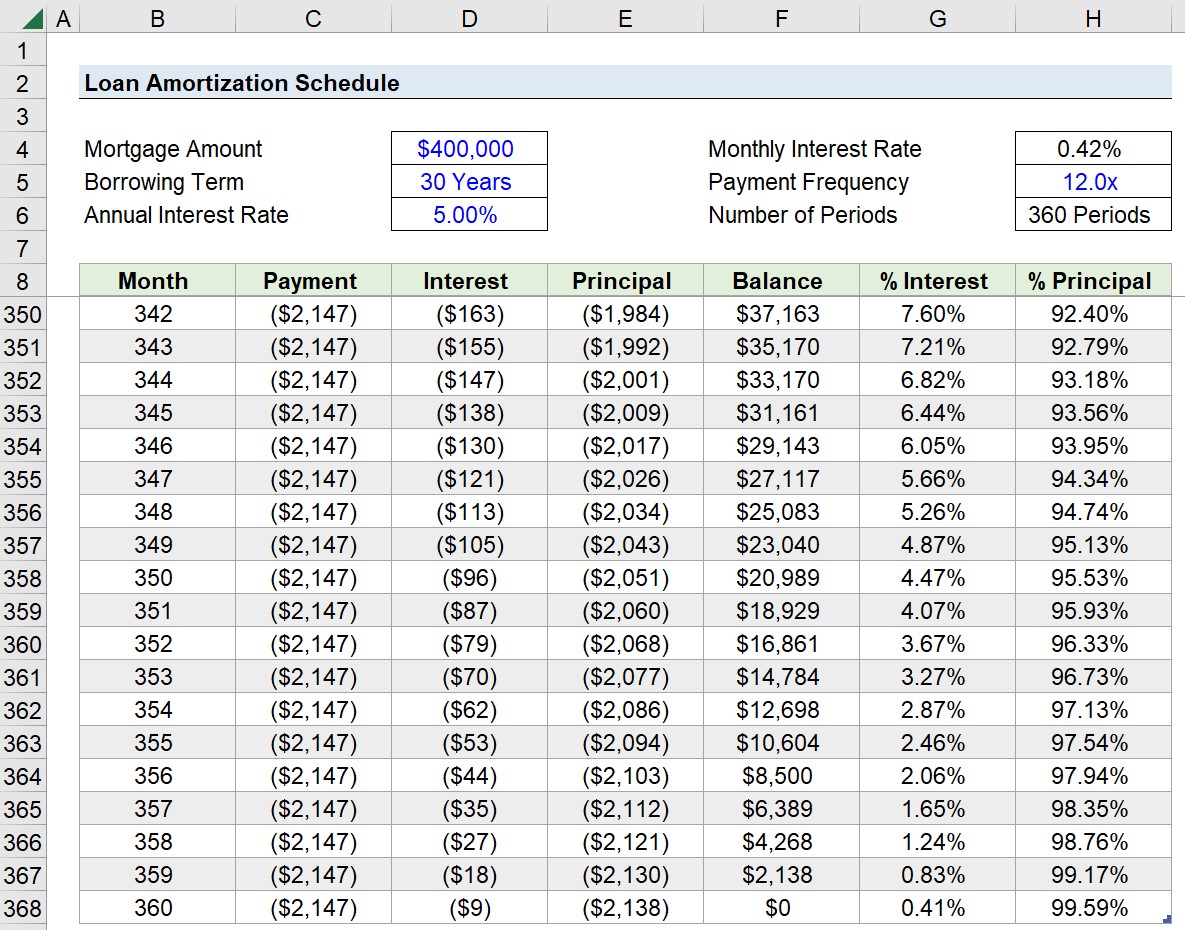
Loan Amortization Schedule | Excel Tutorial

How to make amortization schedule in excel - jakja

Creating Amortization Schedule - Excel Template And Google Sheets File ...
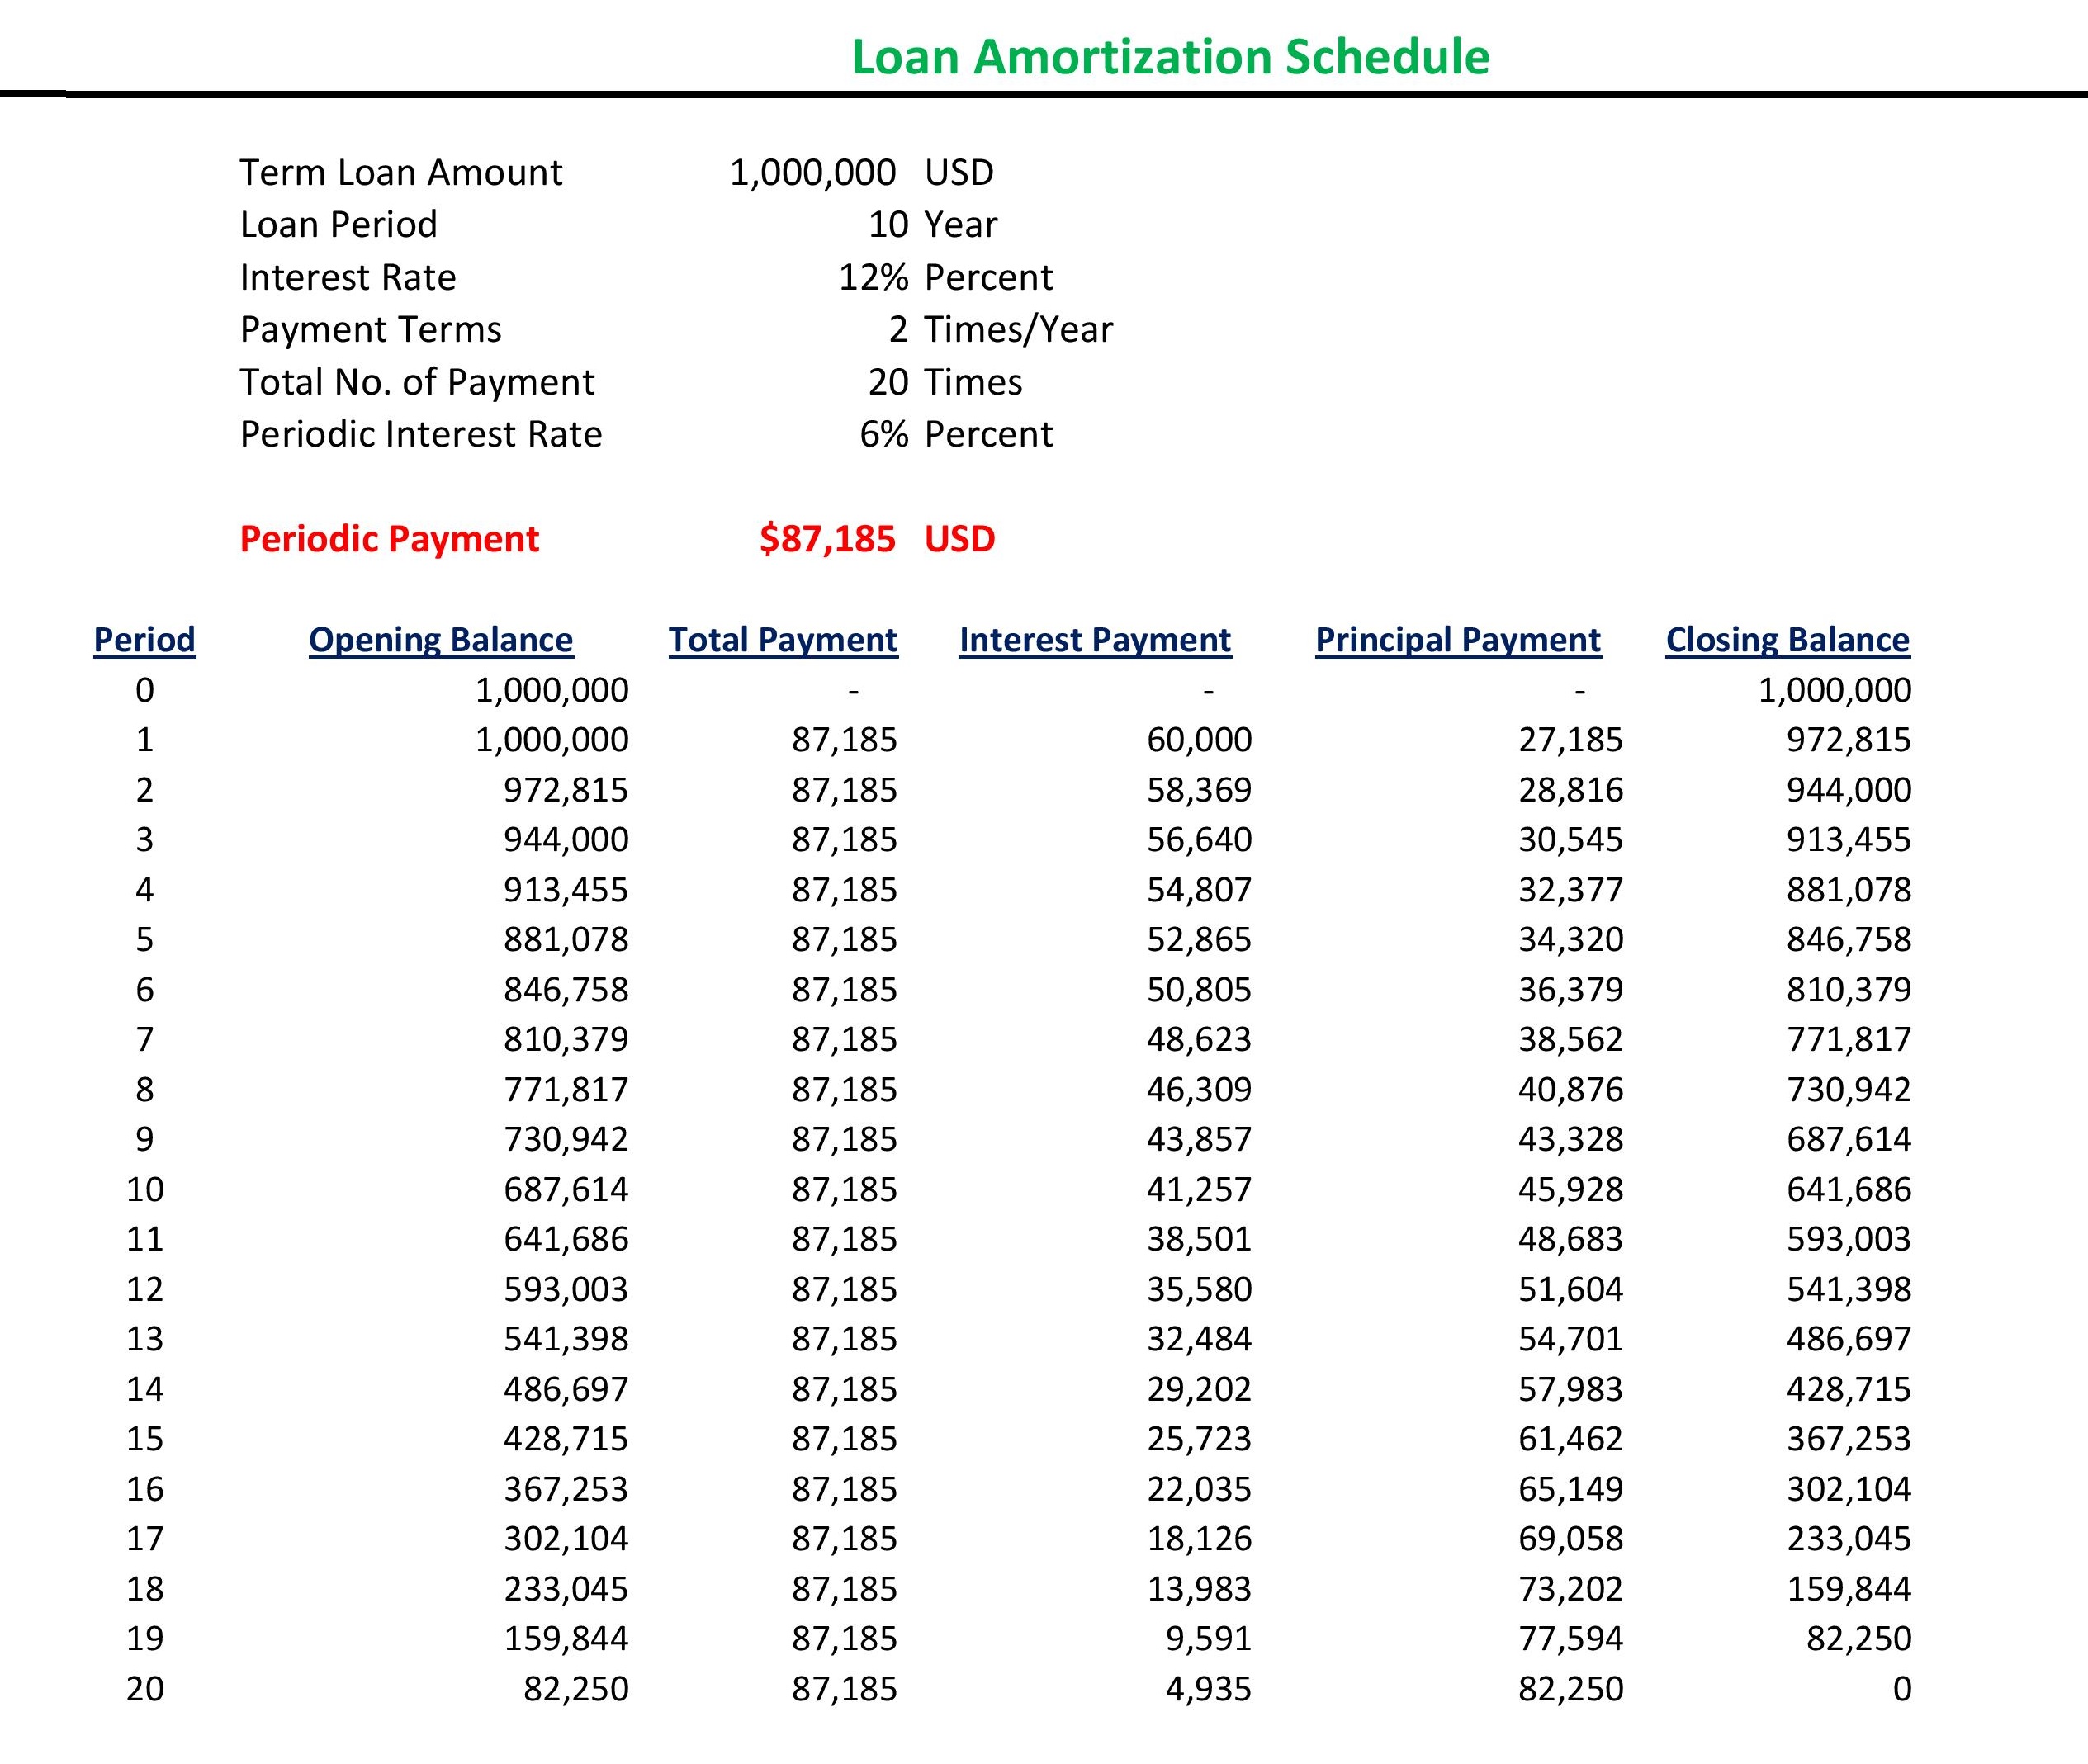
How to Make Loan Amortization Schedule in Excel - ORDNUR
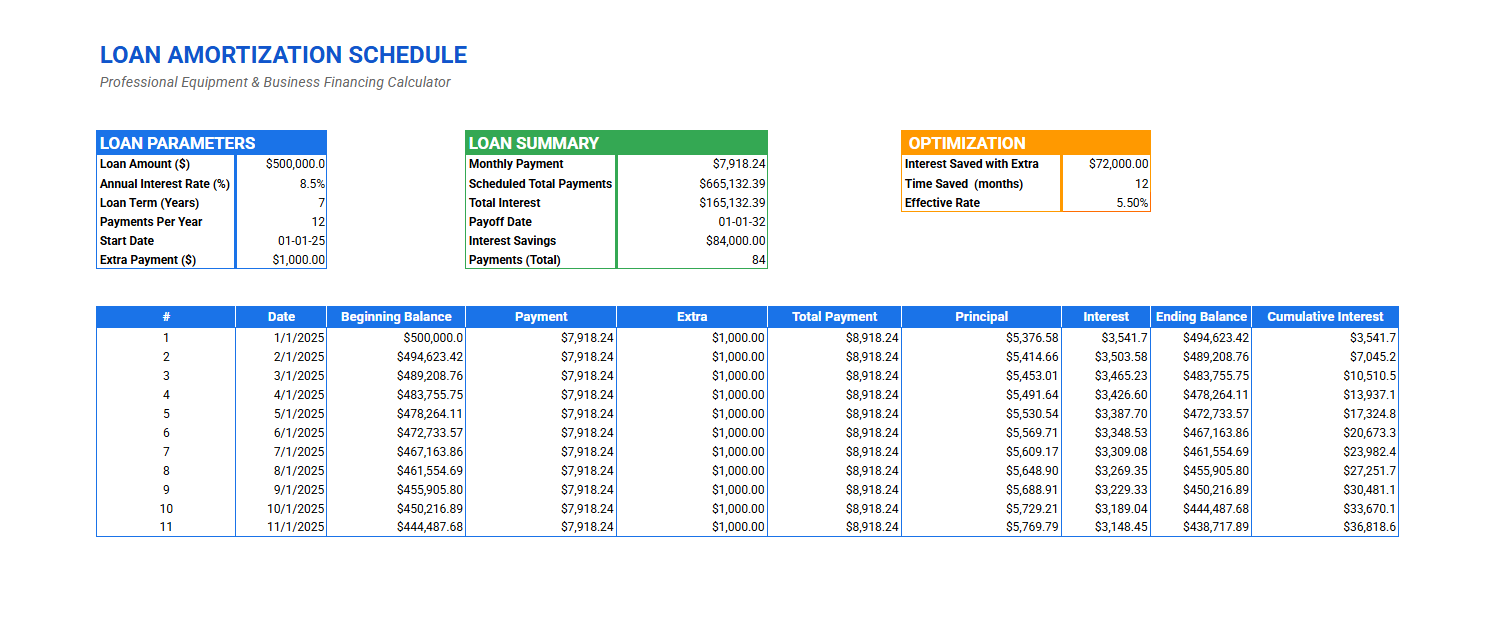
Basic Amortization Schedule Excel Excel Templates 5+ Cricket Score
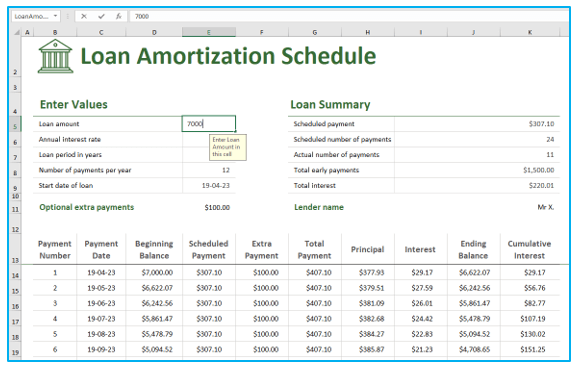
How to Create an Amortization Schedule in Excel?

Amortization schedule template | ONLYOFFICE | ONLYOFFICE

How to Create an Amortization Schedule in Google Sheets - FileDrop

How To Create An Amortization Schedule Excel Template And Google Sheets ...

How to Make an Amortization Schedule in Excel: 7 Steps (with Templates ...

Amortization Schedule Templates in Google Sheets - FREE Download ...

Free Printable Amortization Schedule Templates [PDF, Excel]
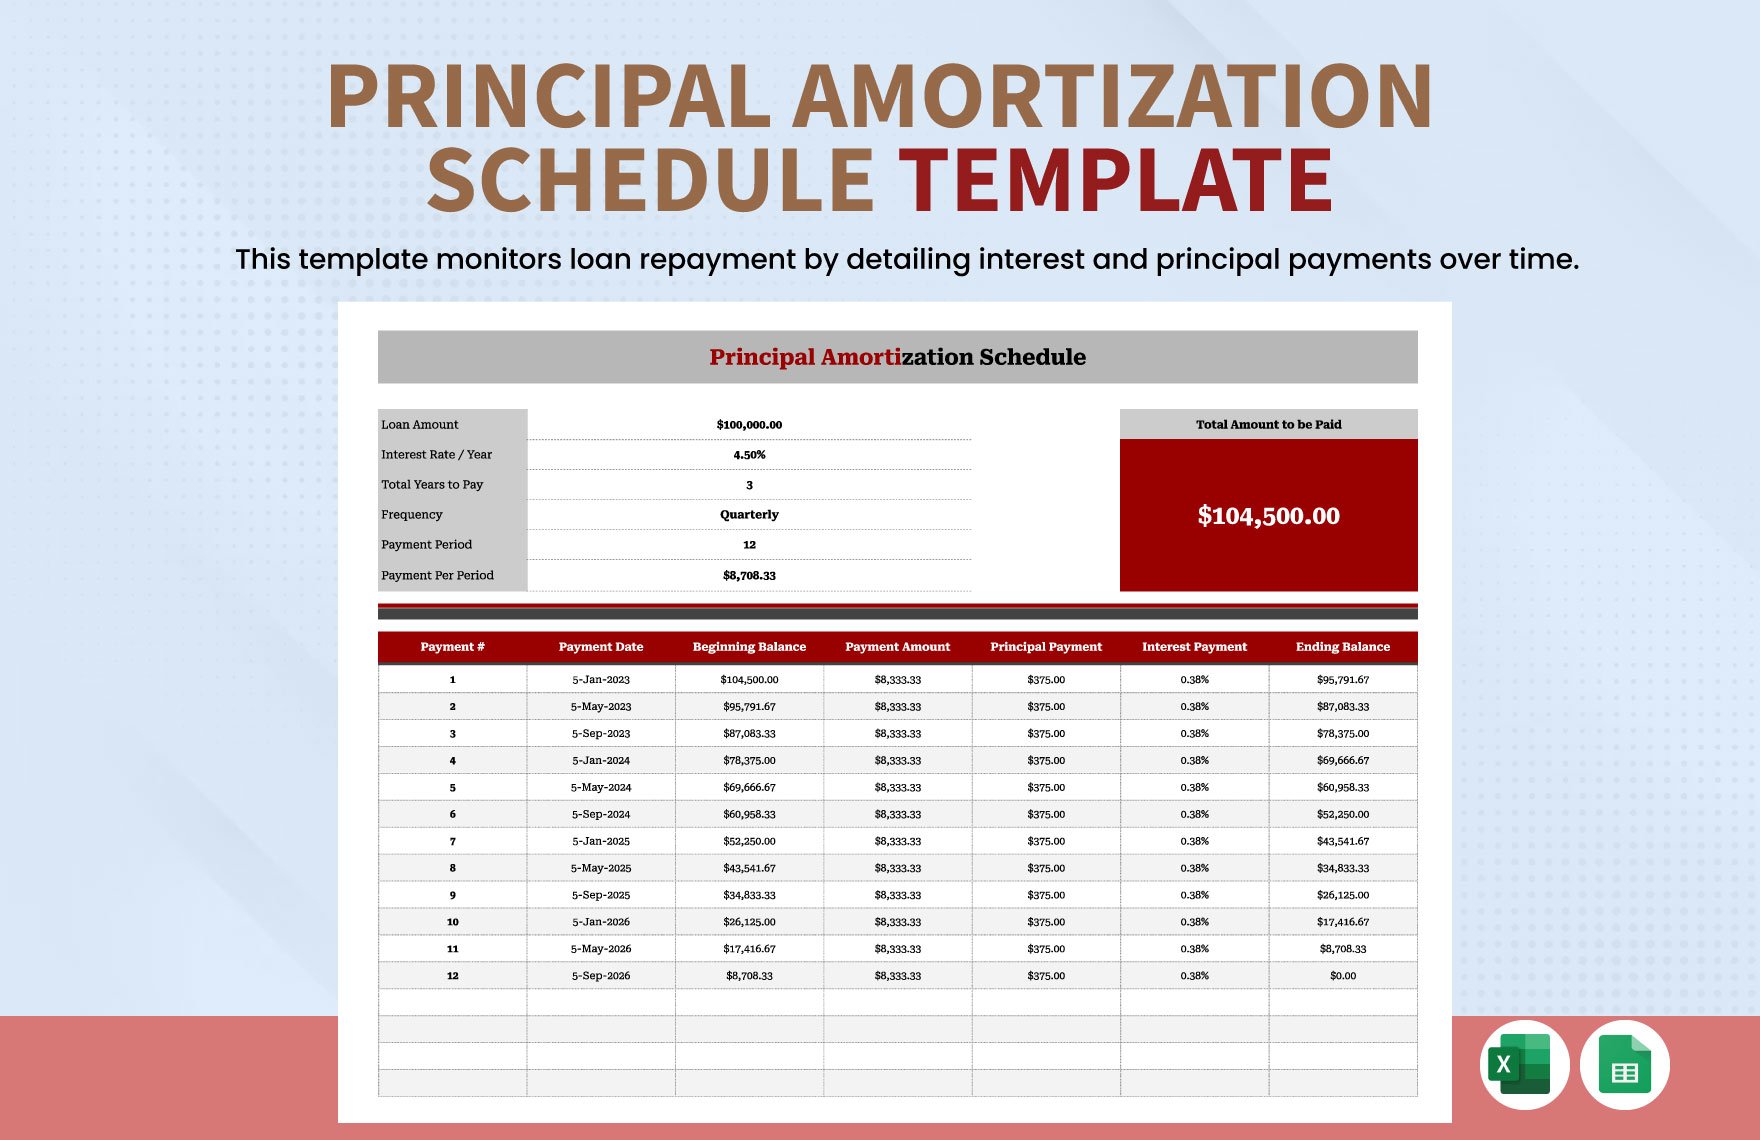
Schedule Table Template in Excel, Google Sheets - Download | Template.net