Overview of Two Year Grantor Retained Annuity Trust Grat 24 Pages
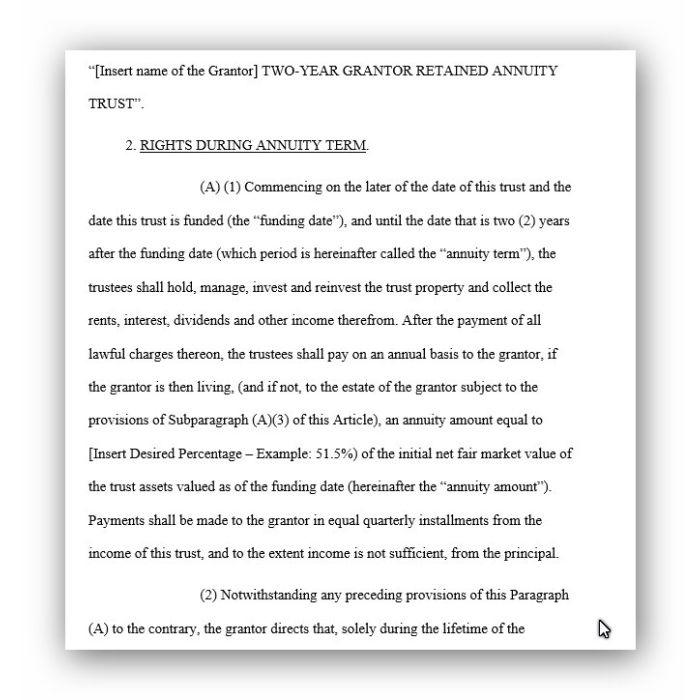
This is a Form of a GRAT designed to have a duration of two years . It is sometimes referred to as a short-term GRAT , or a Walton GRAT after the Tax Court case (Walton v. Commissioner) that authorized the zeroed-out GRAT planning concept. The goal here is to have the grantor recover everything placed into the trust , plus the applicable Code Section 7520 federal rate published by the IRS (the so ...

A GRAT is a federally recognized trust arrangement where the grantor /creator of the trust transfers assets to the trust . The trust terms provide that the grantor retains an annuity payment back from the trust of some identified value, and for a term of years ( two , four, ten years , whatever is decided).
PDF Grantor Retained Annuity Trust

GRAT is created by transferring one or more high-yield assets into an irrevocable trust and retaining the right to an annuity interest for a fixed term of years or for the shorter of fixed term or life. When the retention period ends, assets in the trust (including all appreciation) go to the named "remainder" beneficiary (ies). In some cases other interests, such as the right to have assets ...
How does it work? The grantor creates a GRAT and funds it with assets that are expected to appreciate.1 The trustee of the GRAT distributes an annuity (a fixed annual amount determined at the outset) to the grantor for a term of years . At the end of the GRAT term, any assets remaining in the trust pass to the remainder beneficiaries—often the grantor's children or trusts for their benefit.

Grantor Retained Annuity Trust (GRAT) 2702
Grantor Retained Annuity Trust ( GRAT ) — §2702 The complete practitioner guide to the Grantor Retained Annuity Trust ( GRAT ) — covering §2702 valuation, zeroed-out GRATs , rolling GRATs , and the estate freeze strategy for appreciating assets.
A Grantor Retained Annuity Trust ( GRAT ) is most effective when it is thoughtfully integrated into a broader estate planning strategy. Rather than functioning as a standalone tool, GRATs are often used alongside traditional estate planning documents such as wills, revocable living trusts , powers of attorney, and other tax planning vehicles.
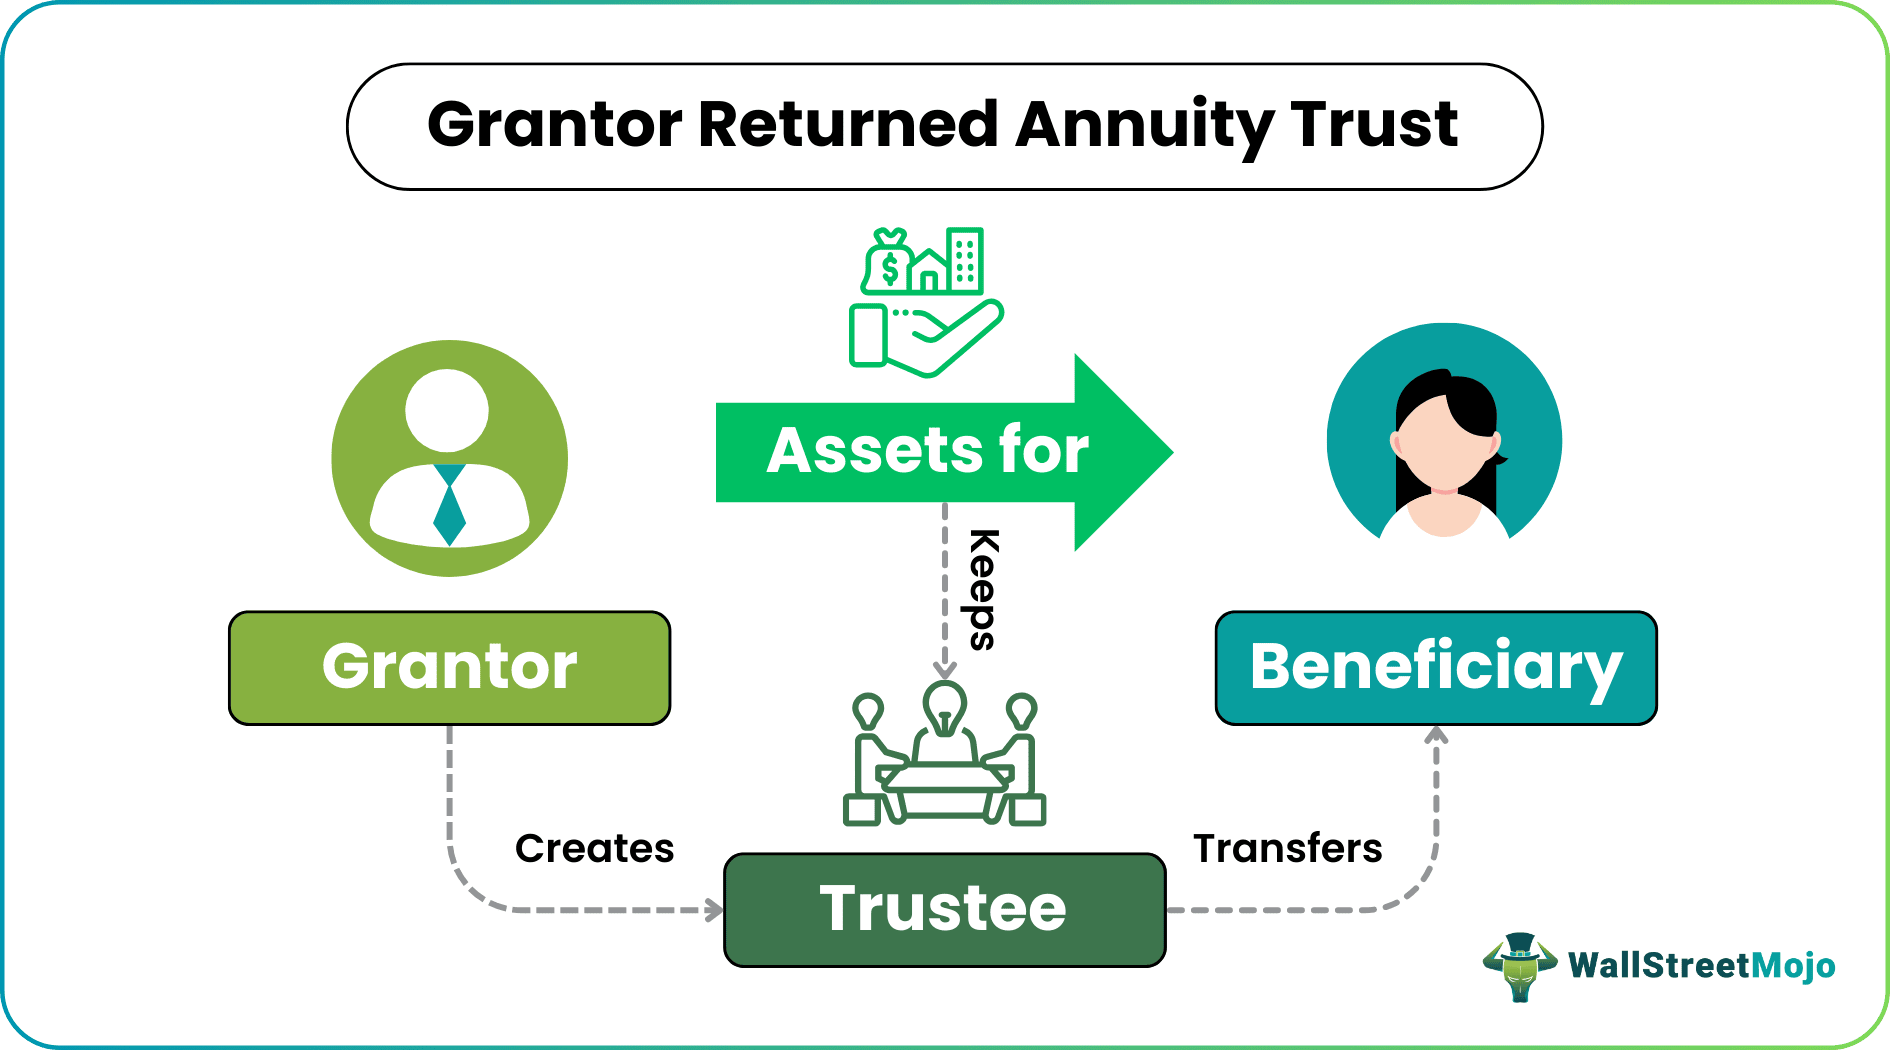
Grantor Retained Annuity Trust (GRAT) Calculator
A Grantor Retained Annuity Trust ( GRAT ) is an irrevocable trust used in estate planning to transfer wealth to beneficiaries with minimal or no gift tax. The grantor places assets into the trust and receives a fixed annuity payment for a specified term. Any appreciation in the trust assets above the IRS's Section 7520 discount rate passes to the beneficiaries gift-tax free at the end of the ...
A GRAT is an irrevocable trust that removes contributed assets from the grantor's estate, provides the grantor with an income that discounts the gift tax value of the transferred assets (possibly resulting in no gift tax liability), and allows trust assets to grow without additional gift tax.

PDF Grantor retained annuity trust (GRAT)
The IRS assumes the GRAT's assets will experience a particular rate of return (commonly referred to as the Sec. 7520 rate),* and that amount is included in the annual annuity payment to the grantor . When the trust's term ends, any assets remaining in the trust (above the annuity amount and the IRS presumed return) will transfer to the beneficiaries designated by the grantor in the trust ...

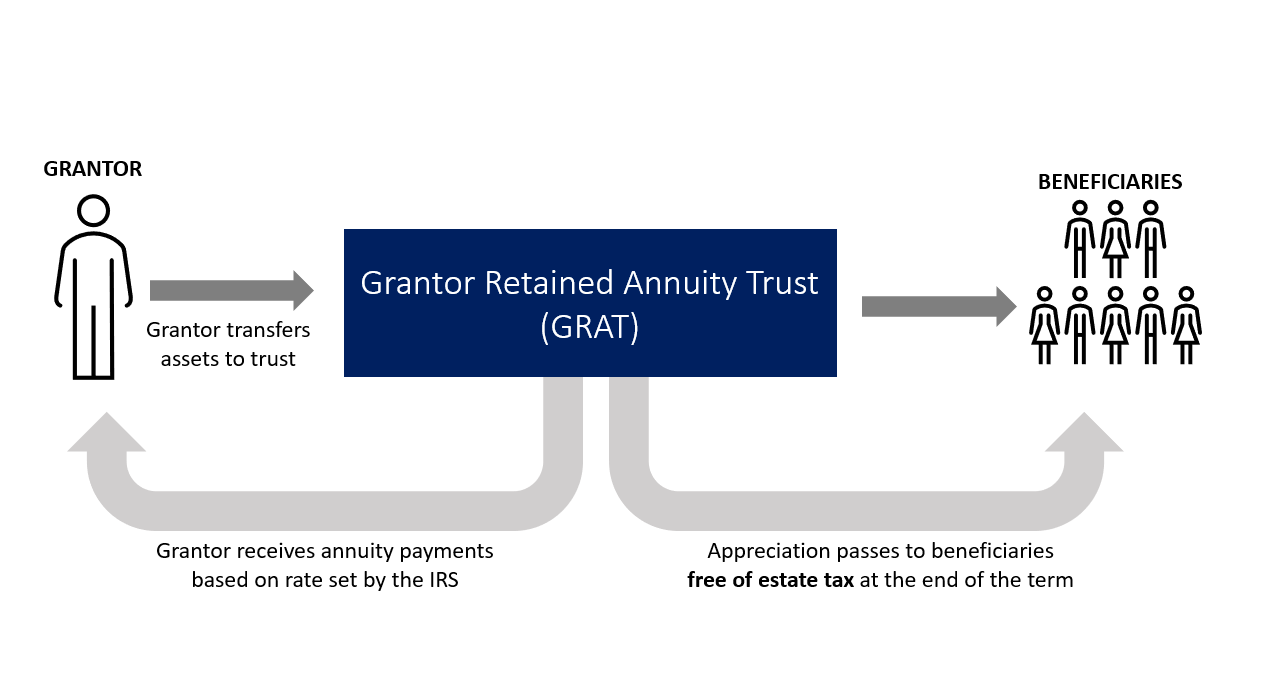


Grantor Retained Annuity Trust ( GRAT ) Looking for a smart, IRS-approved strategy to transfer business or investment assets to your heirs while minimizing gift taxes? Our Grantor Retained Annuity Trust ( GRAT ) Template helps you set up a powerful estate planning tool designed to freeze the value of appreciating assets and shift future growth to your beneficiaries—tax efficiently and legally.