2.7 Rabbi Trusts
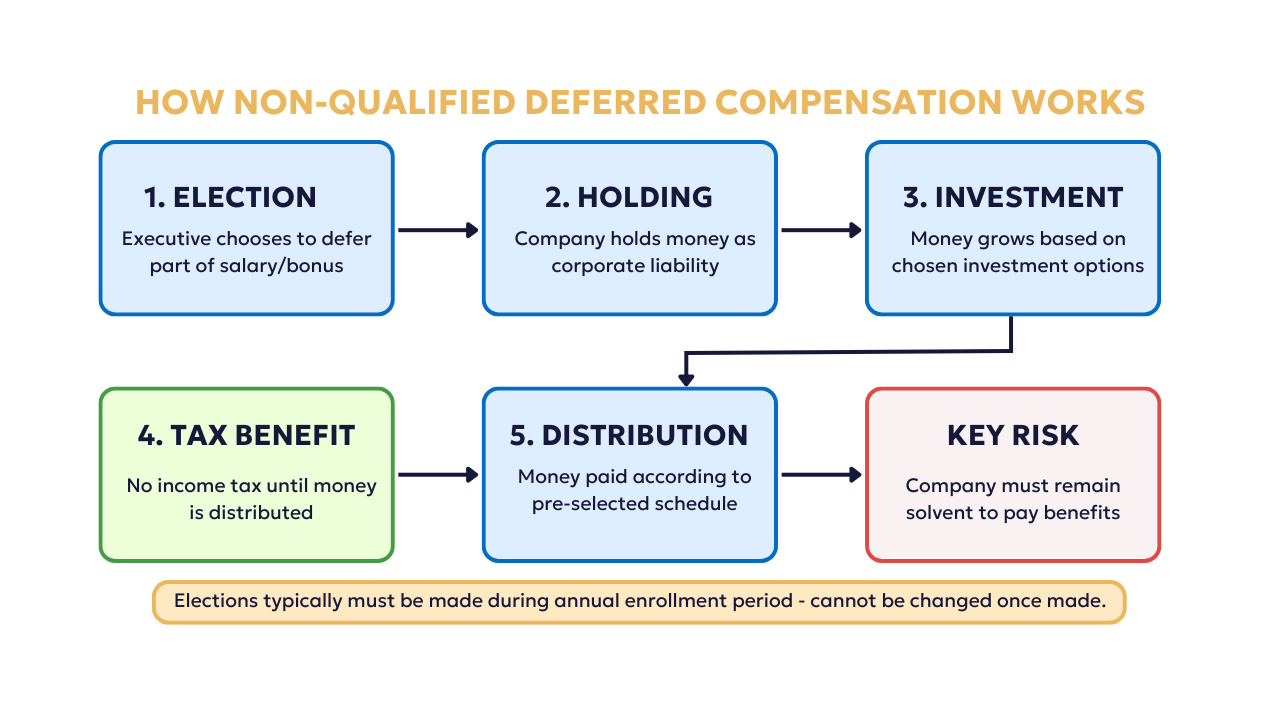
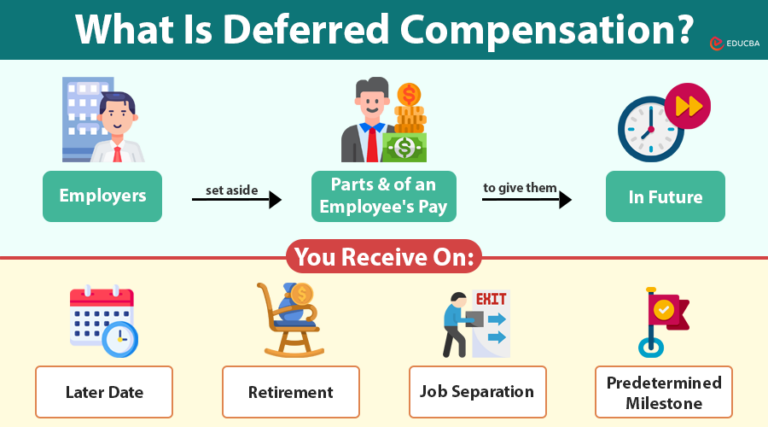
2.7 Rabbi Trusts Many entities have arrangements that allow their employees to defer some or all of their earned compensation (i.e., salary or bonus). Sometimes the employer uses a "rabbi trust " 4 to hold assets from which nonqualified deferred compensation payments will be made.
Rabbi trusts represent a unique financial arrangement designed to provide security for employees participating in non-qualified deferred compensation plans. Unlike qualified plans, which are protected under the Employee Retirement Income Security Act (ERISA), non-qualified plans do not offer the...
Rabbi Trusts

Such details provide a deeper understanding and appreciation for Deferred Compensation Trusts.
Rabbi trusts - irrevocable trust for deferred compensation benefits to select employees. Learn its role in estate planning, how to establish, and benefits.
A rabbi trust is a non-qualified employee trust used to support deferred compensation obligations under specific IRS guidelines. The trust offers tax deferral benefits for employees. Contributions ...
PDF Rabbi Trusts

ADVANTAGES OF RABBI TRUSTS An advantage of a rabbi trust , in addition to the protection afforded, is the opportunity for tax deferral by employees on the deferred compensation . The rabbi trust may be taxed like a grantor trust , with taxable income attributed to the employer because funds in the rabbi trust are subject to claims of the employer's creditors. If the plan and trust are properly ...
05-8 The Deferred Compensation — Rabbi Trusts Subsections of this Subtopic address the accounting for deferred compensation arrangements where amounts earned by an employee are invested in the stock of the employer and placed in a rabbi trust . Certain of those plans allow the employee to immediately diversify into nonemployer securities or to diversify after a holding period (for example ...
A form of irrevocable trust (referred to as a "rabbi" trust ) is sometimes used to fund deferred compensation arrangements to reduce the risk of non-payment to the executive. Assets are placed in an irrevocable trust established by the employer. Legally, the assets remain those of the employer; however, access to trust assets is severely restricted. The employer or an acquirer cannot revoke the ...
Section 877A (c) exempts deferred compensation items, specified tax deferred accounts, and interests in a non-grantor trust from the mark-to-market regime. This exemption applies if the covered expatriate was a beneficiary of the trust on the day before their expatriation date.
More Context About Deferred Compensation Trusts
The Executive's Guide to Non-Qualified Deferred Compensation Plans. It gives the article a little more context before the image collection begins.
PPT - Session 14 Fundamentals of Deferred Compensation PowerPoint. This note connects the source idea with the visuals in a simple, reader-friendly way.
Mississippi Nonqualified Deferred Compensation Trust for the Benefit of. It works as a short bridge between the article summary and the gallery section.