Understanding the 90-Day Payment Option: A Comprehensive Guide
In the dynamic world of business, flexible payment terms are not just a convenience, but a necessity. One such flexible payment option that has gained significant traction is the 90-day payment term. This article delves into the intricacies of this payment option, its benefits, potential drawbacks, and best practices for implementation.
What is the 90-Day Payment Option?
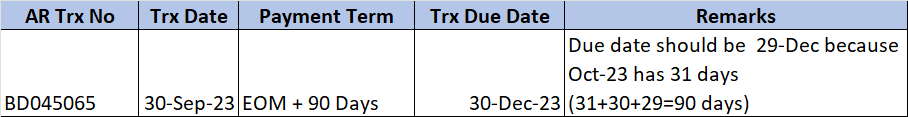
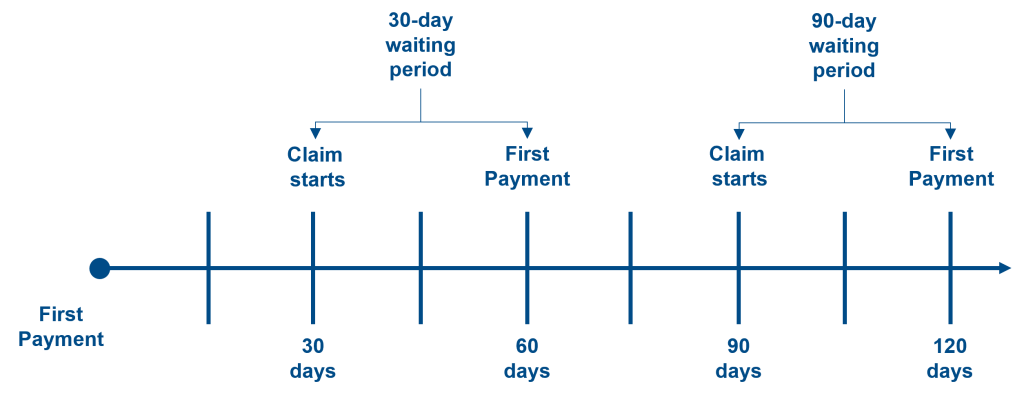
The 90-day payment option, also known as net 90, is a payment agreement where a buyer has 90 days from the invoice date to pay for goods or services rendered. This is a longer payment term compared to the more common net 30 or net 60 terms. It's often used in business-to-business (B2B) transactions, particularly in industries with longer sales cycles or complex supply chains.
Benefits of the 90-Day Payment Option
- Cash Flow Management: Longer payment terms allow businesses to manage their cash flow more effectively. It provides a buffer, enabling companies to collect payments from their customers before they need to pay their own suppliers.
- Relationship Building: Offering a 90-day payment term can foster stronger relationships with customers, demonstrating trust and flexibility. It can also be a competitive advantage, attracting customers who prefer longer payment terms.
- Risk Mitigation: In some cases, a 90-day payment term can help mitigate risks. For instance, it allows buyers to assess the quality of goods or services before making the final payment.
Potential Drawbacks and Mitigation Strategies
While the 90-day payment option offers several benefits, it's not without its potential drawbacks. These include:
- Delayed Cash Flow: While it helps manage cash flow, it also delays it. To mitigate this, businesses can implement strict credit policies and closely monitor accounts receivable.
- Credit Risk: Longer payment terms can increase credit risk. To manage this, businesses can conduct thorough credit checks on customers and maintain adequate insurance.
Table: Comparison of Payment Terms
| Payment Term | Days to Pay | Benefits | Drawbacks |
|---|---|---|---|
| Net 30 | 30 days | Quick cash flow, lower credit risk | Less flexible, may strain customer relationships |
| Net 60 | 60 days | Improved cash flow management, more flexible | Moderate credit risk, may still strain relationships |
| Net 90 | 90 days | Better cash flow management, relationship building, risk mitigation | Delayed cash flow, increased credit risk |
Best Practices for Implementing the 90-Day Payment Option
To maximize the benefits of the 90-day payment option, consider the following best practices:
- Credit Policy: Establish a clear credit policy that outlines the criteria for offering net 90 terms and the consequences for late payments.
- Regular Reviews: Regularly review and update your credit policy to ensure it aligns with your business needs and market conditions.
- Clear Communication: Clearly communicate the payment terms to your customers to avoid misunderstandings.
- Monitor Accounts Receivable: Closely monitor your accounts receivable to ensure timely payments and follow up on late payments promptly.
In conclusion, the 90-day payment option, when implemented strategically, can be a powerful tool for businesses to manage cash flow, build relationships, and mitigate risks. However, it's crucial to understand the potential drawbacks and implement best practices to maximize its benefits.