Navigating Financial Challenges: When Your House is Falling Apart and Money is Tight
Finding yourself in a situation where your house is falling apart, but you're short on funds, can be overwhelming. It's crucial to approach this challenge systematically, prioritizing safety and stability. This guide will help you navigate this situation, providing practical steps and resources to help you manage your home and finances.
Assessing the Damage: Safety First
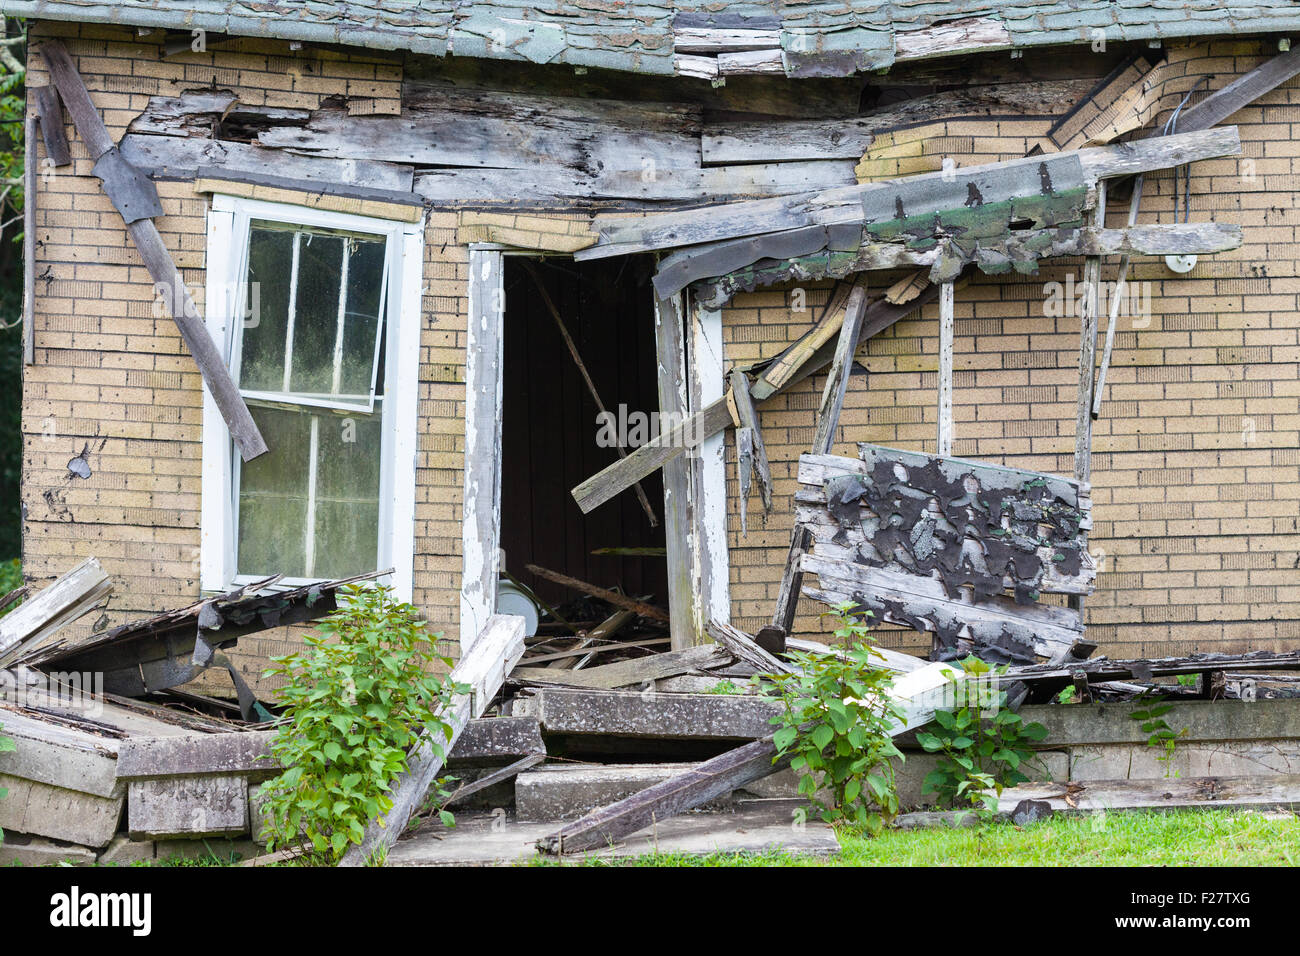
The first step is to assess the damage, focusing on safety and structural integrity. Look for signs of significant damage such as cracks in the foundation, leaks, or electrical hazards. If you're not sure, consider hiring a professional home inspector. Safety should always be your top priority.
Emergency Repairs vs. Cosmetic Issues
- Emergency Repairs: These are critical issues that pose a risk to your safety or the structural integrity of your home. Examples include leaks, electrical hazards, or a compromised roof.
- Cosmetic Issues: These are non-urgent problems that don't immediately threaten your safety. Examples include peeling paint or worn-out flooring.
Focus on emergency repairs first, even if it means temporarily neglecting cosmetic issues.

Creating a Budget and Prioritizing Repairs
Once you've identified the necessary repairs, it's time to create a budget. List all the repairs, their estimated costs, and prioritize them based on urgency and necessity. Remember to include a contingency fund (around 10-15% of your total budget) for unexpected costs.
Creative Financing Options
If you're short on funds, consider the following financing options:
| Option | Pros | Cons |
|---|---|---|
| Home Equity Loan | Low interest rates, can be used for any home repair | Requires good credit, puts your home at risk if you can't repay |
| Government Grants | No repayment required, can be used for specific repairs like energy efficiency | Limited funds, competitive application process |
| Personal Loans | No collateral required, can be used for any repair | Higher interest rates, can impact your credit score |
Also, consider DIY projects to save on labor costs. However, ensure you have the necessary skills and tools to avoid causing more damage.

Negotiating with Contractors and Suppliers
Once you've decided on the repairs and financing, it's time to find contractors and suppliers. Get multiple quotes, and don't be afraid to negotiate. Contractors may be willing to work with you on pricing, especially if you can offer them steady work.
Preventative Maintenance: Planning Ahead
While you're addressing the immediate issues, it's also important to plan for the future. Regular maintenance can prevent small problems from becoming big, expensive ones. Create a maintenance schedule, and set aside a small amount each month for preventative maintenance.
Remember, it's okay to ask for help. Reach out to friends, family, or local community resources. Many communities have programs to assist homeowners with repairs and maintenance. Don't hesitate to explore these options.