Comparing Student Loans: A Comprehensive Guide
Embarking on a college education is an exciting journey, but it often comes with a significant financial commitment. Student loans are a common way to fund these expenses, but with numerous lenders and loan types available, comparing student loans can be overwhelming. This guide will walk you through the process, helping you make an informed decision that aligns with your financial goals and needs.
Understanding the Basics of Student Loans
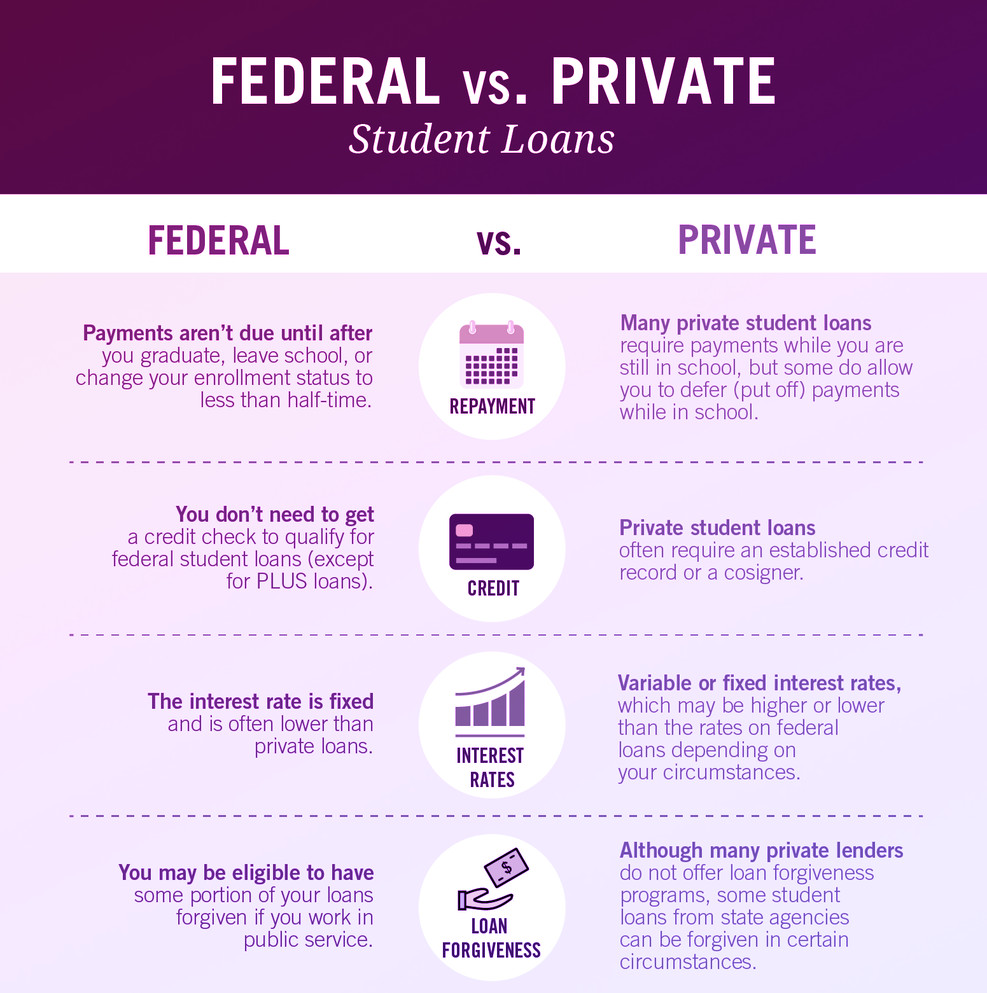
Before diving into the comparison process, it's crucial to understand the different types of student loans. They can be broadly categorized into two: federal and private loans.
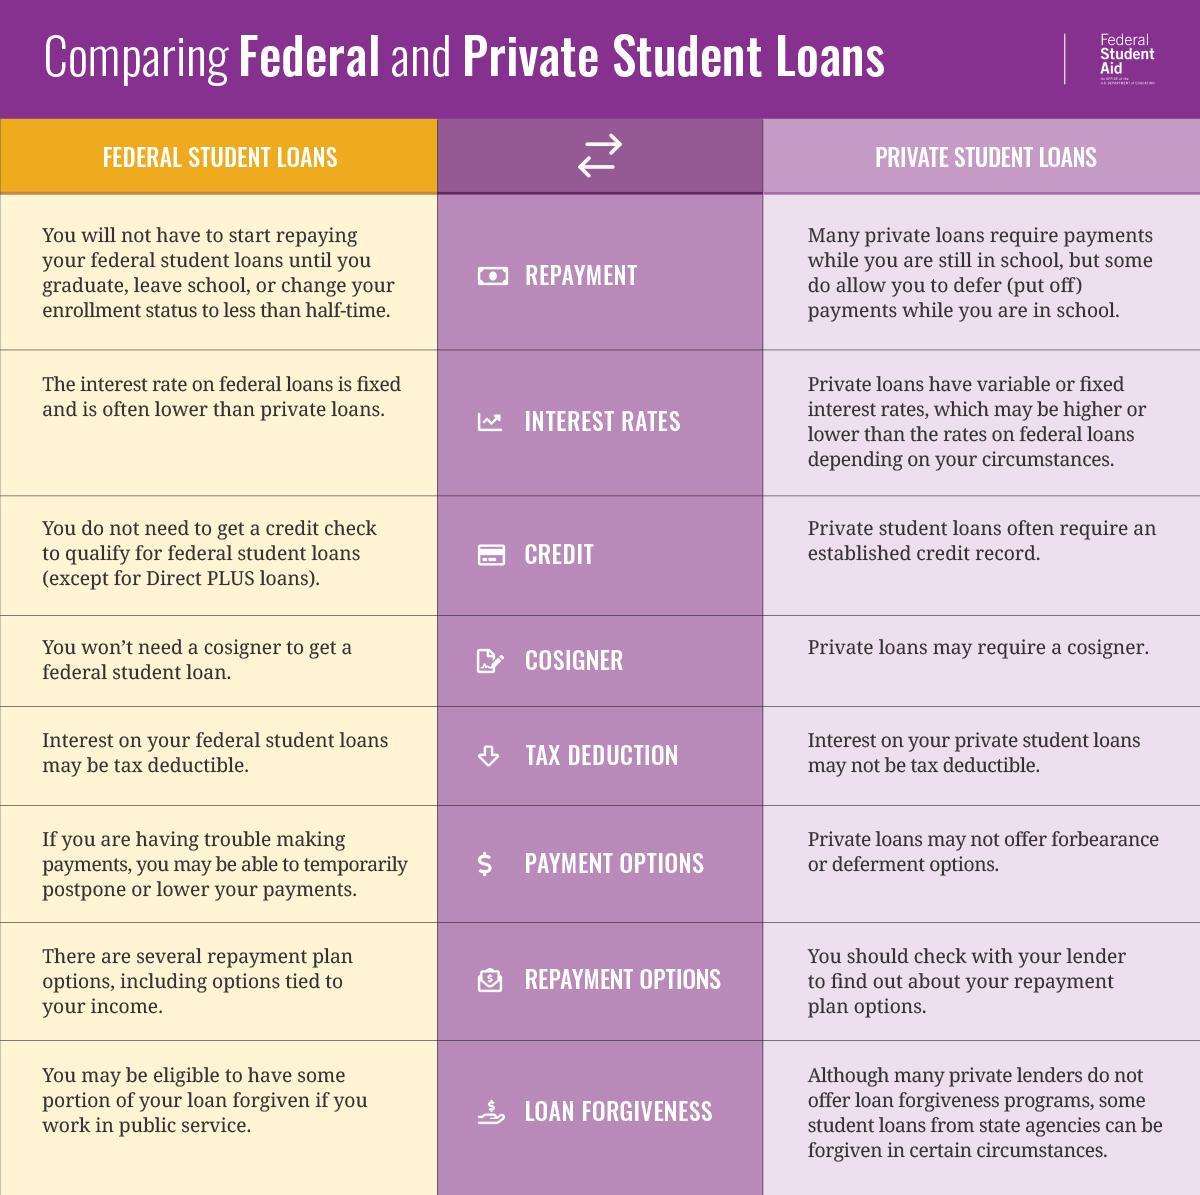
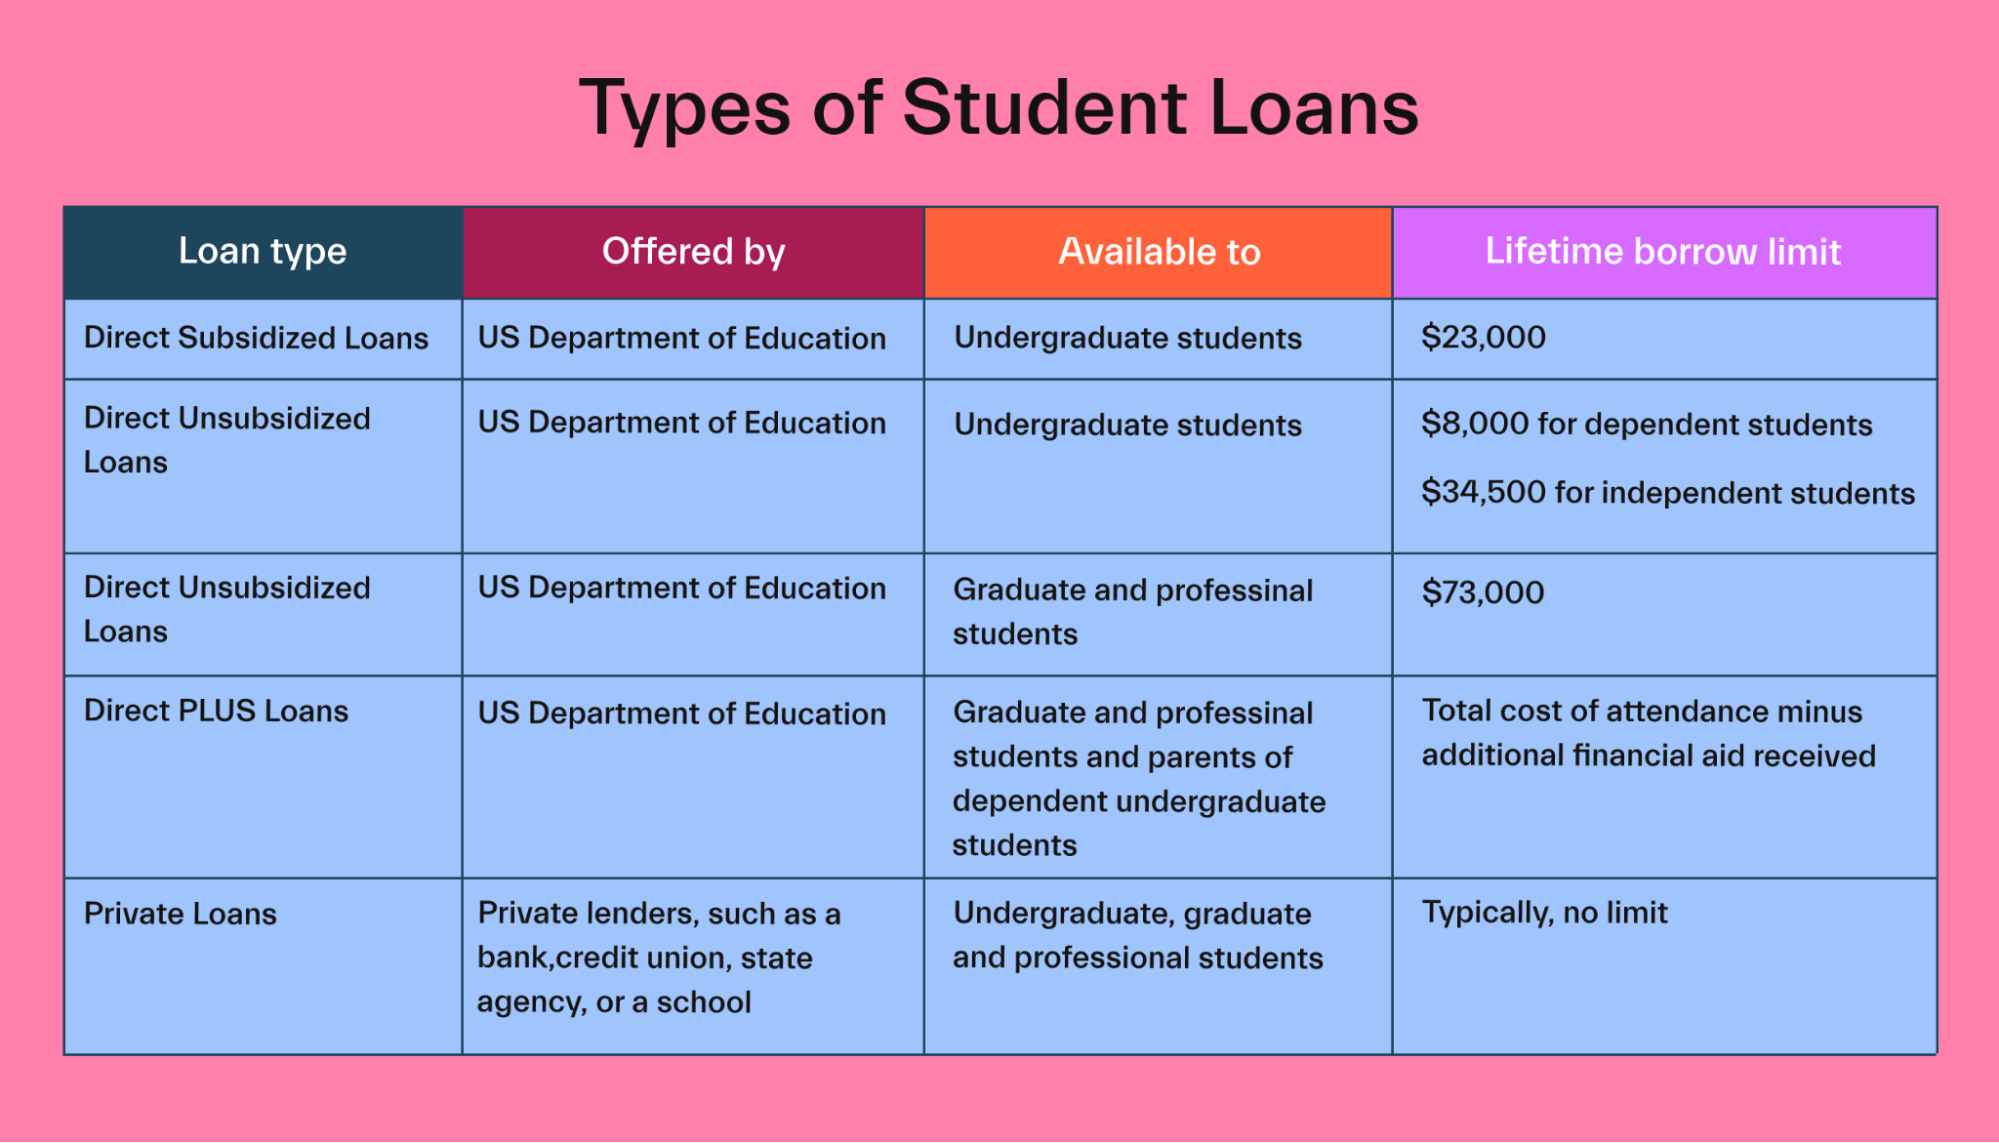
- Federal Loans: Offered by the U.S. Department of Education, these loans come with fixed interest rates, flexible repayment plans, and access to forgiveness programs.
- Private Loans: Provided by banks, credit unions, or online lenders, these loans have variable or fixed interest rates, and repayment terms can vary. They typically don't offer the same benefits as federal loans.
Key Factors to Compare When Evaluating Student Loans
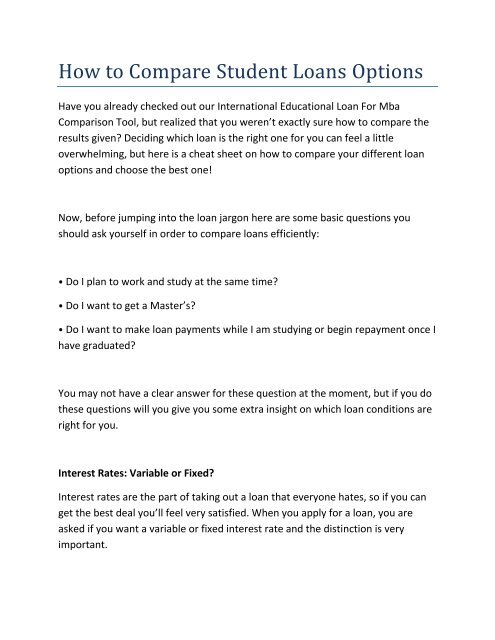
When comparing student loans, consider the following key factors to ensure you're making an apples-to-apples comparison.
/Content Offer 78/AFCU_78-StudentLoanComparison-padd.png?width=4500&height=3273&name=AFCU_78-StudentLoanComparison-padd.png)
Interest Rates
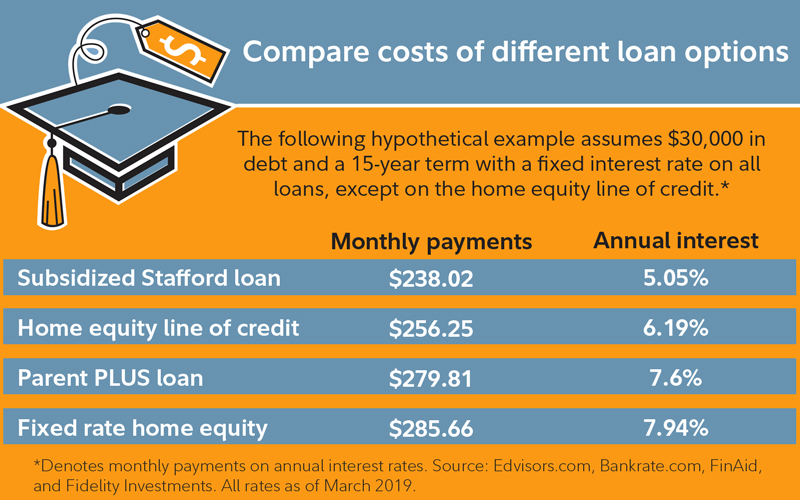
Interest rates significantly impact the total cost of your loan. Federal loans have fixed interest rates, while private loans can offer fixed or variable rates. Be sure to consider the interest rate when comparing offers.
Fees
Some lenders charge origination fees, disbursement fees, or prepayment penalties. These fees can add to your overall loan cost, so it's essential to factor them into your comparison.
Repayment Terms
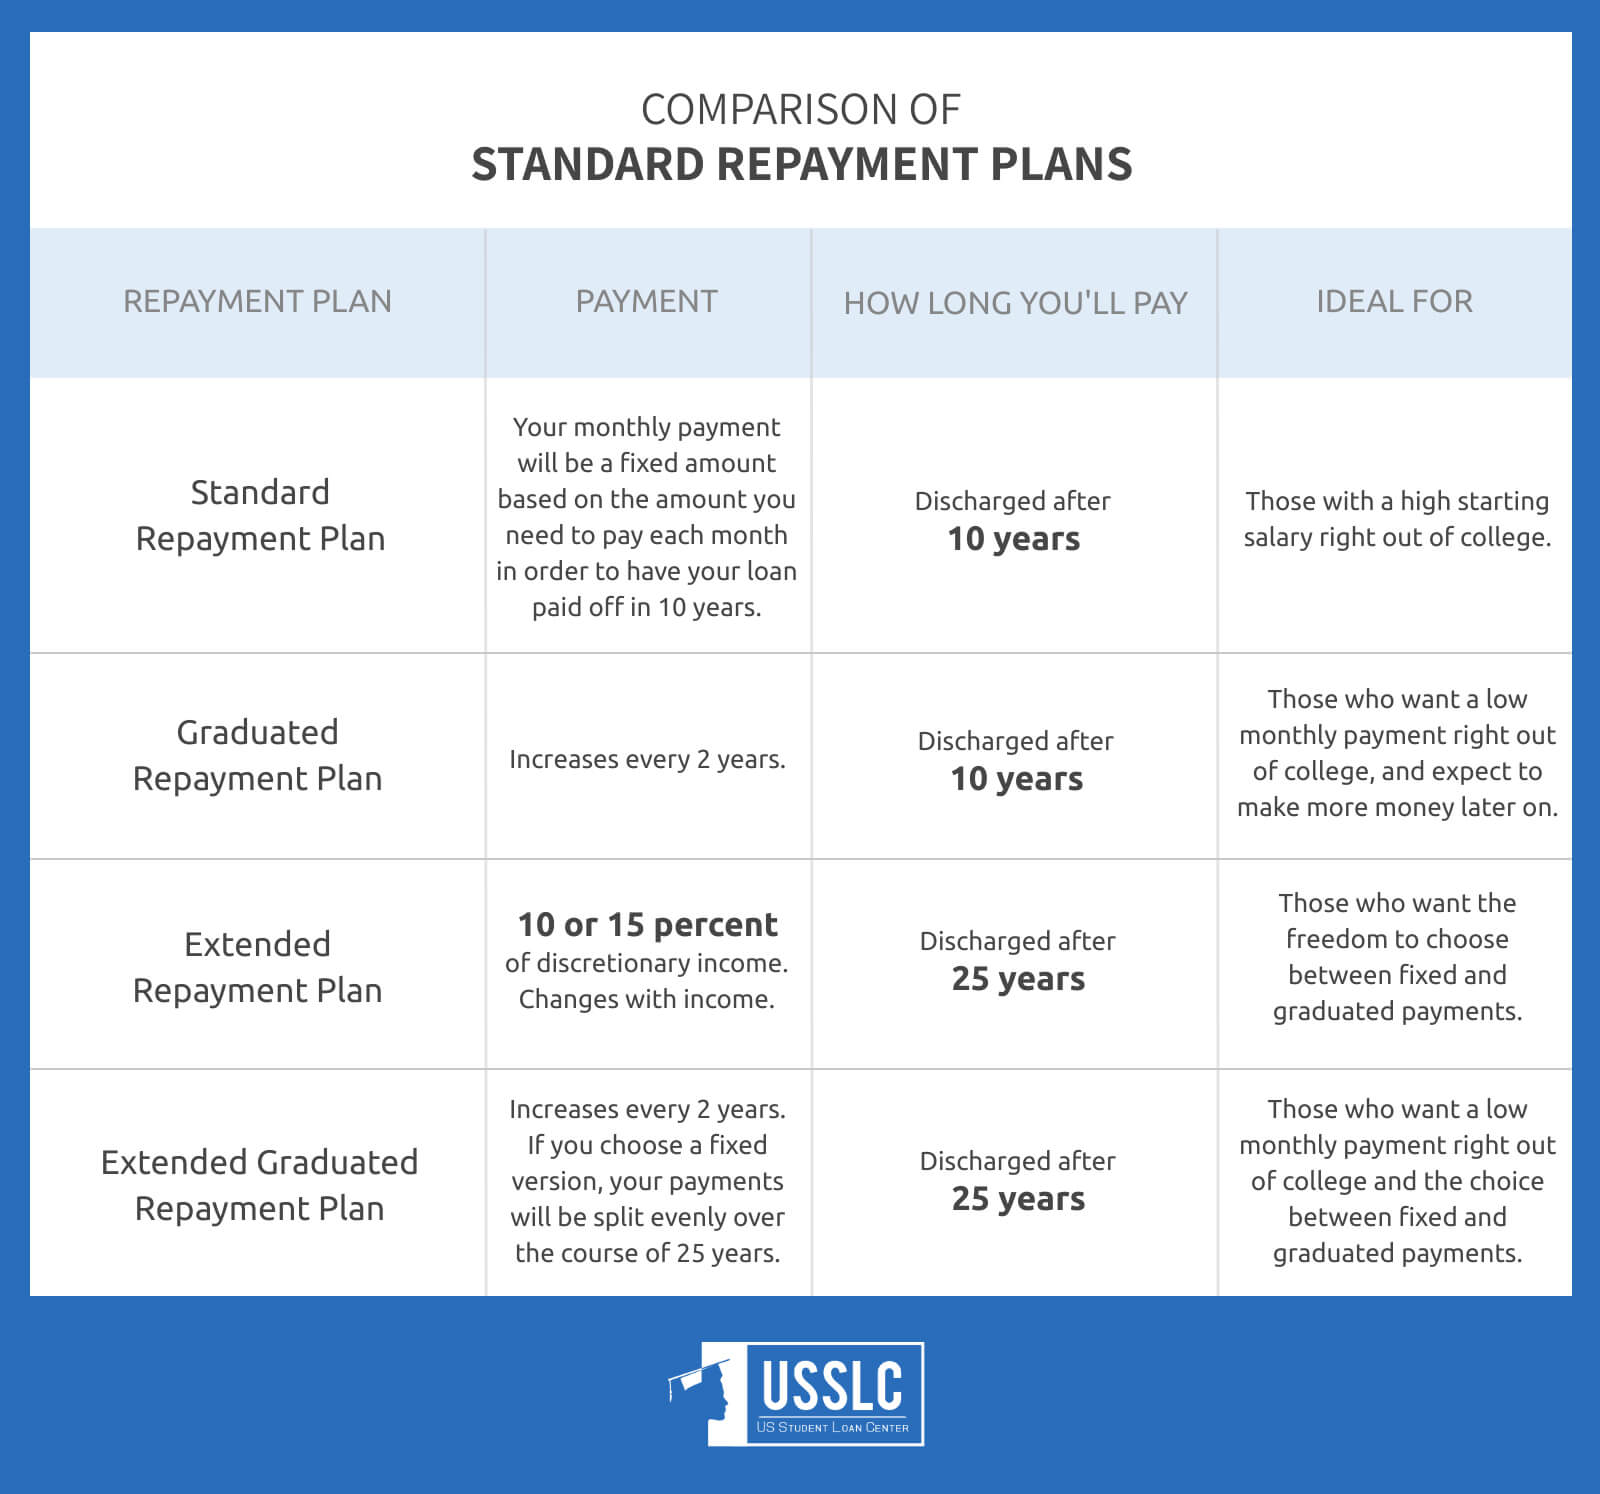
Understand the repayment terms, including the loan term length, minimum monthly payment, and when repayment begins. Federal loans offer flexible repayment plans, while private lenders may have stricter terms.
Loan Limits
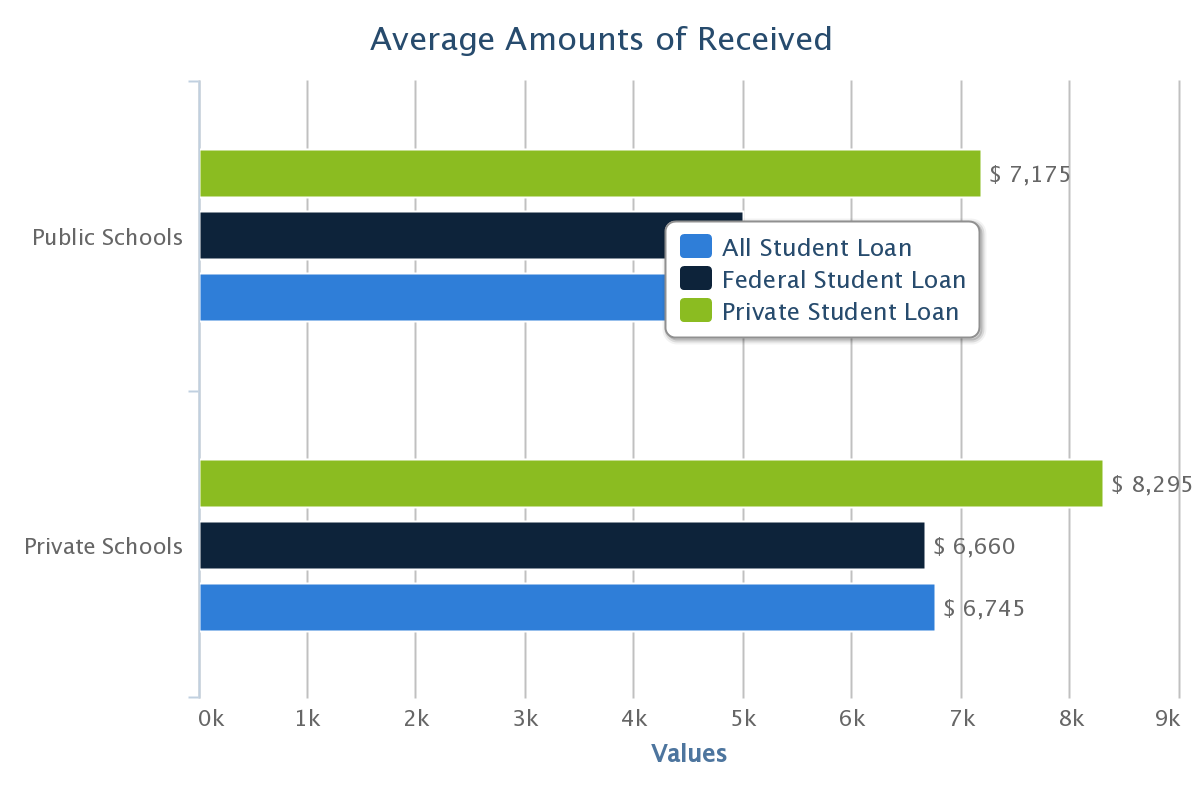
Federal loans have annual and aggregate loan limits. Private lenders may also have limits, so ensure you understand these restrictions when comparing loans.
Eligibility Requirements
Each loan type has specific eligibility requirements. Federal loans require students to maintain enrollment in an eligible program and meet certain academic progress standards. Private lenders may have different requirements, such as credit score minimums or co-signer requirements.
Comparing Student Loans: A Side-by-Side Example
Let's compare two student loan offers to illustrate the comparison process.
| Loan Type | Interest Rate | Fees | Loan Term | Minimum Monthly Payment | Loan Limit | Eligibility Requirements |
|---|---|---|---|---|---|---|
| Federal Direct Subsidized Loan | 4.53% | None | 10 years | $50 (minimum) | $5,500 (annual limit for freshmen) | Financial need, enrollment in eligible program |
| Private Loan (Lender X) | 5.25% (fixed) | 3% origination fee | 15 years | $100 (minimum) | $20,000 (aggregate limit) | Credit score of 650 or above, U.S. citizenship |
In this example, the federal loan offers a lower interest rate, no fees, and a shorter loan term. However, it has a lower annual limit and requires financial need. The private loan offers a longer loan term and higher aggregate limit but comes with an origination fee and stricter eligibility requirements.
Tips for Making the Best Choice When Comparing Student Loans
When comparing student loans, consider the following tips to make the best choice for your financial situation:
- Use a student loan calculator to estimate your monthly payments and total loan cost.
- Consider your financial needs and eligibility requirements when comparing offers.
- Prioritize federal loans before considering private loans, as they often come with more benefits and protections.
- Shop around with multiple lenders to find the best offer for your needs.
- Carefully review the terms and conditions of each loan before accepting an offer.
Comparing student loans is a crucial step in financing your education. By understanding the key factors to consider and using the tips outlined in this guide, you'll be well on your way to making an informed decision that sets you up for financial success after graduation.




/Content Offer 78/AFCU_78-StudentLoanComparison-2x1.jpg)