Unveiling Large Transactions: A Deep Dive into IRS Transactions Over $10,000
The Internal Revenue Service (IRS) keeps a watchful eye on significant financial transactions, with a particular focus on those exceeding $10,000. This threshold is not arbitrary; it's a key figure in the Bank Secrecy Act (BSA), which aims to prevent tax evasion and money laundering. Let's delve into the world of large transactions reported to the IRS, exploring why they matter, how they're tracked, and what they tell us about the economy.
Why Transactions Over $10,000 Matter to the IRS
Transactions over $10,000 are of keen interest to the IRS due to two primary reasons: tax evasion and potential criminal activities like money laundering. Here's a breakdown of these concerns:
- Tax Evasion: Large cash transactions can be a red flag for the IRS, as they may indicate an attempt to avoid reporting income or paying taxes. By tracking these transactions, the IRS can identify potential tax evaders and ensure everyone pays their fair share.
- Money Laundering and Other Criminal Activities: Transactions over $10,000 can also be used to launder money, finance terrorism, or support other illicit activities. The BSA requires financial institutions to report these transactions to help law enforcement agencies combat these crimes.
How the IRS Tracks Large Transactions
The IRS uses several methods to track transactions over $10,000. Here are some of the key ways:
- Currency Transaction Reports (CTRs): Financial institutions are required to file CTRs for any transaction involving more than $10,000 in a single day. This includes cash transactions, as well as checks, promissory notes, and other instruments.
- Monetary Instrument Logs (MILs): MILs are used to track physical currency transactions, such as those involving cashiers' checks, money orders, or traveler's checks, that exceed $10,000.
- Structuring: While not a specific transaction type, structuring involves breaking down a large transaction into smaller ones to avoid the $10,000 reporting threshold. The IRS actively looks for and investigates structuring activities.
Transactions Over $10,000: A Window into the Economy
While the primary focus of tracking large transactions is to prevent tax evasion and criminal activities, these data points also provide valuable insights into the economy. They can reveal trends in consumer spending, business activity, and even economic health. For instance, a significant increase in large transactions might indicate growing consumer confidence or business investment.
What Happens When a Transaction Over $10,000 is Reported?
When a financial institution reports a transaction over $10,000 to the IRS, it triggers a review process. The IRS may investigate further if the transaction appears suspicious or if it believes there may be underreported income. In some cases, this could lead to an audit or other enforcement actions. However, most reported transactions are simply logged and used for statistical analysis.
Staying Compliant: Tips for Individuals and Businesses
To stay on the right side of the IRS, it's crucial to understand and comply with the reporting requirements for large transactions. Here are some tips:
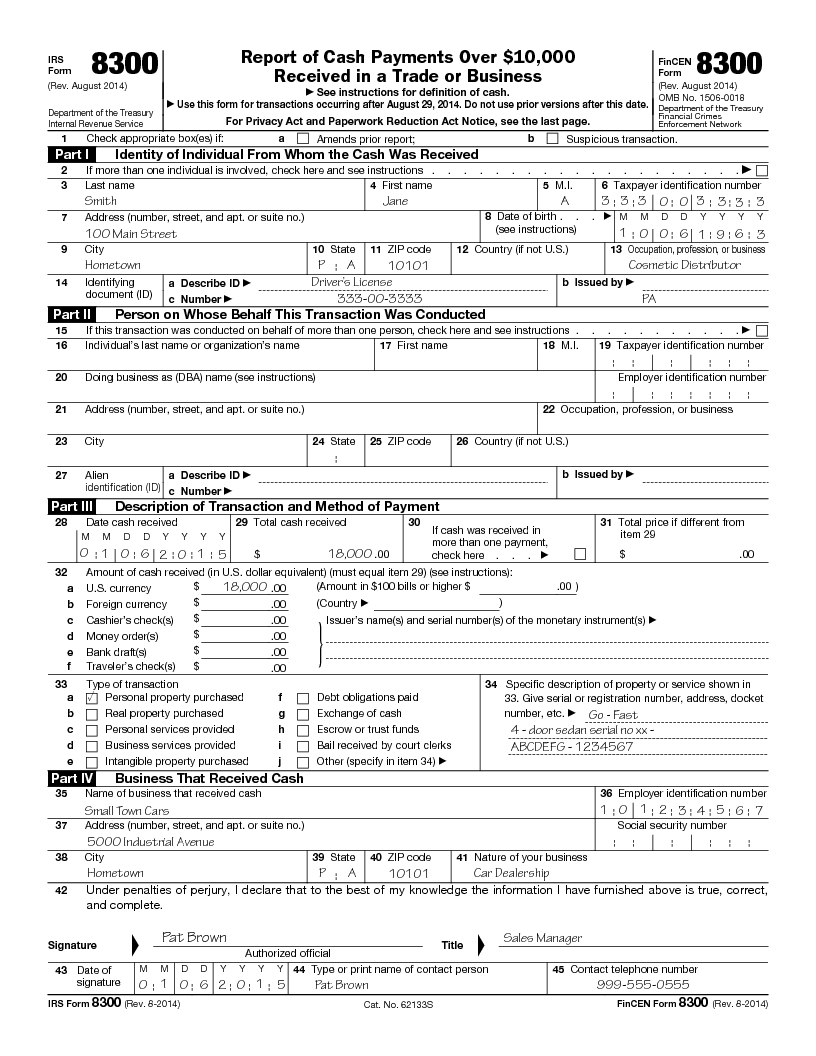
- Keep detailed records of all financial transactions, including those involving cash.
- Be aware of the $10,000 threshold and ensure that your financial institutions are complying with reporting requirements.
- If you're involved in a large transaction, consider consulting with a tax professional to ensure you're meeting all your legal obligations.
Transactions over $10,000 reported to the IRS serve a vital role in maintaining a fair and transparent tax system, as well as combating criminal activities. By understanding and complying with the relevant regulations, individuals and businesses can help ensure the integrity of the system and maintain the trust of their communities.