When to Start Paying Off Your Student Loans: A Strategic Guide
Embarking on your post-graduation journey can be an exciting time, filled with new opportunities and challenges. One of the most significant decisions you'll make during this phase is when to start paying off your student loans. While it might be tempting to put it off, understanding the intricacies of your loan terms and interest rates can help you make an informed decision that could save you thousands in the long run.
Understanding Your Loan Terms
Before you decide when to start repaying your student loans, it's crucial to understand the terms and conditions of each loan. Your loans could have different interest rates, repayment plans, and grace periods. Here's a breakdown of the most common types of student loans and their repayment terms:
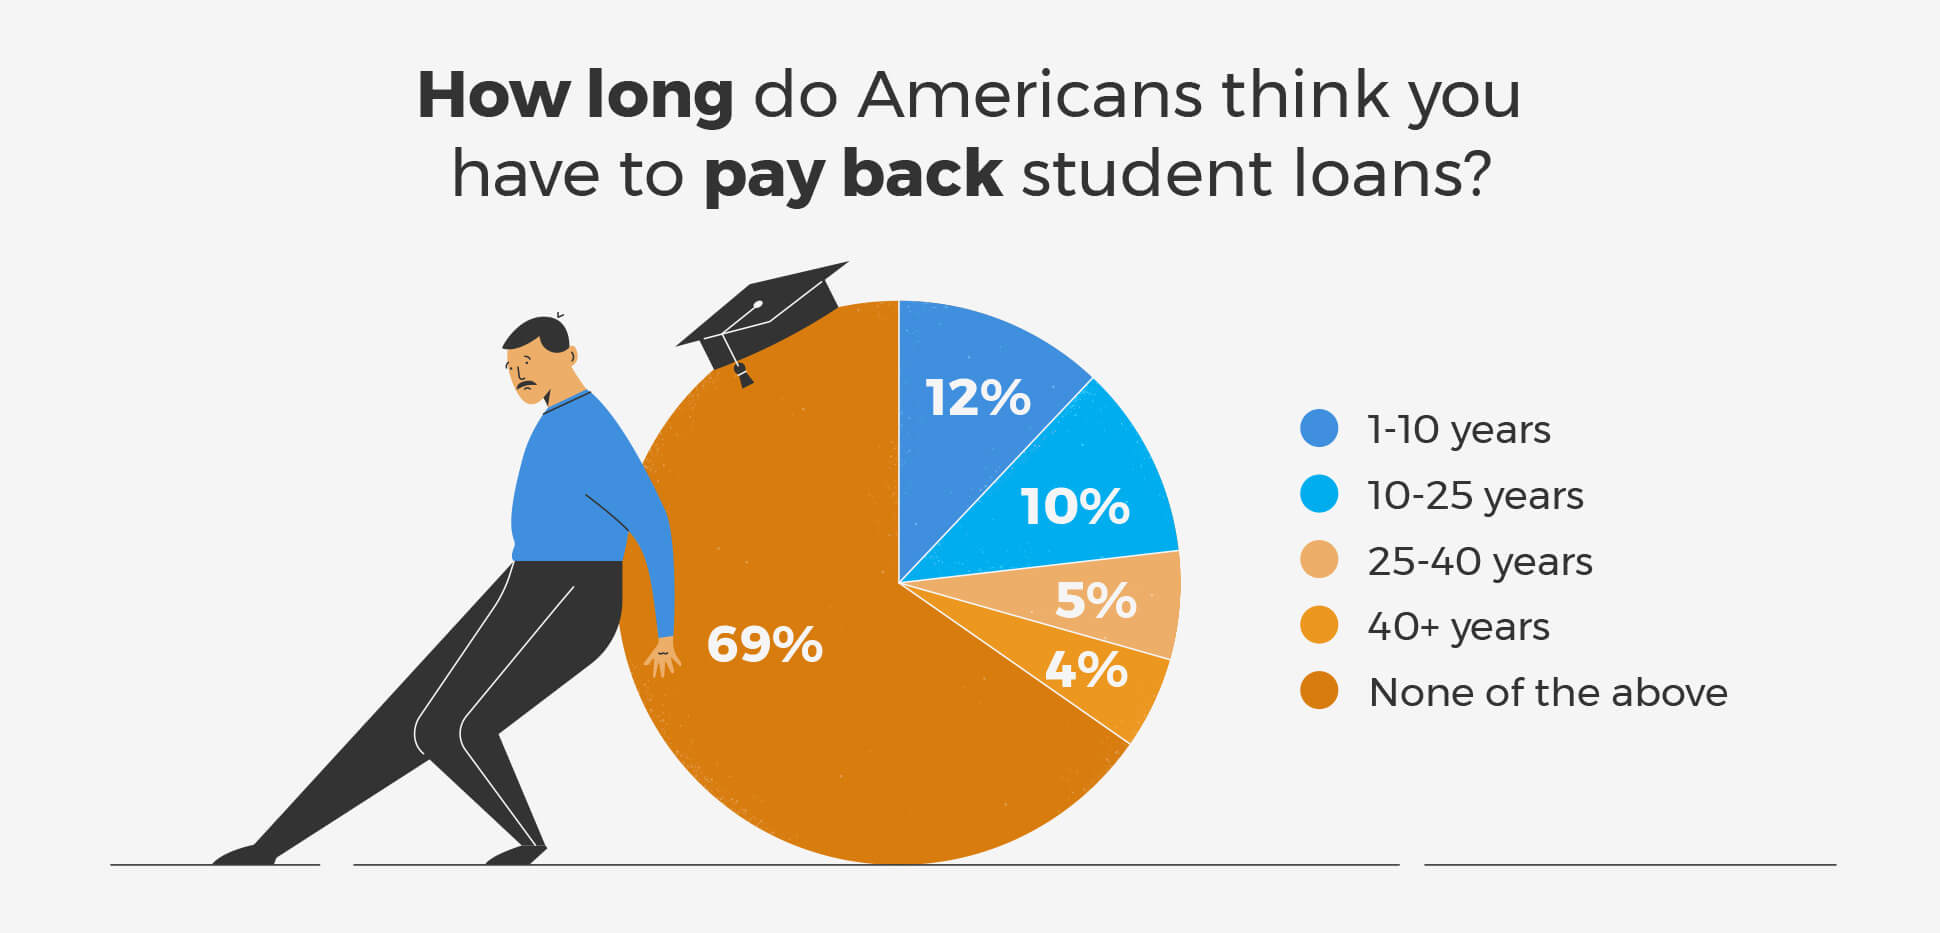
- Federal Student Loans: These loans have a six-month grace period after graduation or dropping below half-time enrollment. During this period, no payments are required, and interest does not accrue. Repayment plans range from 10 to 25 years, depending on the loan type.
- Private Student Loans: Repayment terms vary by lender, but most require payments to start as soon as the loan is disbursed. Some lenders may offer a grace period, but it's typically shorter than federal loans. Repayment terms usually range from 5 to 20 years.
When to Start Paying Off Your Student Loans
Now that you understand your loan terms, let's explore the pros and cons of starting loan repayment early versus waiting until the grace period expires.
Pros of Starting Loan Repayment Early
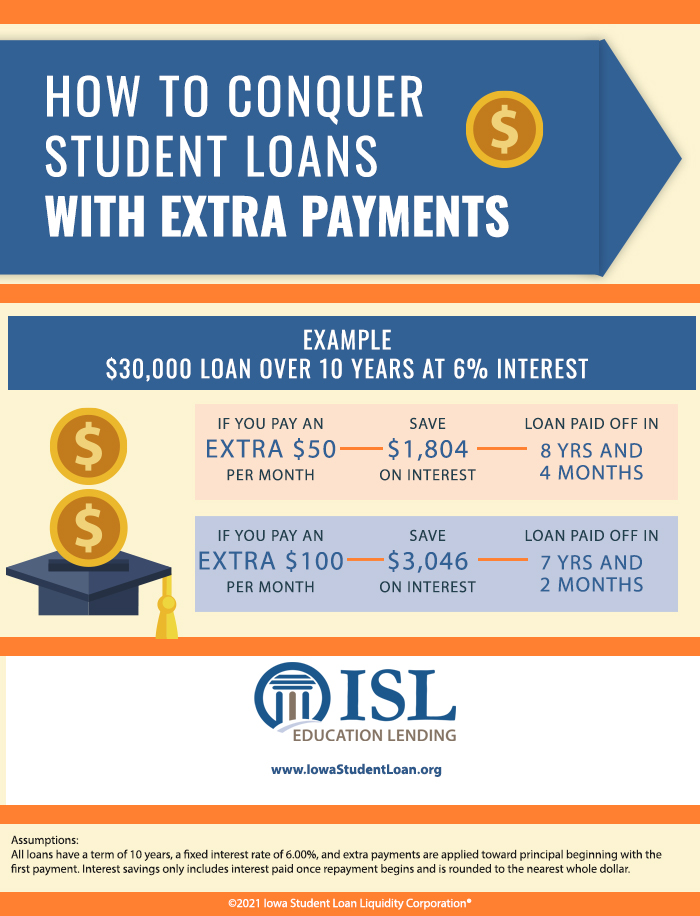
- Save on Interest: Interest accrues daily on most student loans. By starting repayment early, you can reduce the total amount of interest you'll pay over the life of the loan.
- Build Credit: Making consistent, on-time payments can help build your credit history, which can be beneficial when applying for future credit, like a mortgage or car loan.
- Peace of Mind: Starting repayment early can help you feel more in control of your financial future and reduce the overall stress of having significant debt.
Cons of Starting Loan Repayment Early
- Opportunity Cost: Money you use to pay down your loans could be invested or used to build your career, such as through further education or job training.
- Cash Flow: Starting repayment early may strain your budget, especially if you're just starting your career and your income is still growing.
Strategies for Managing Your Student Loans
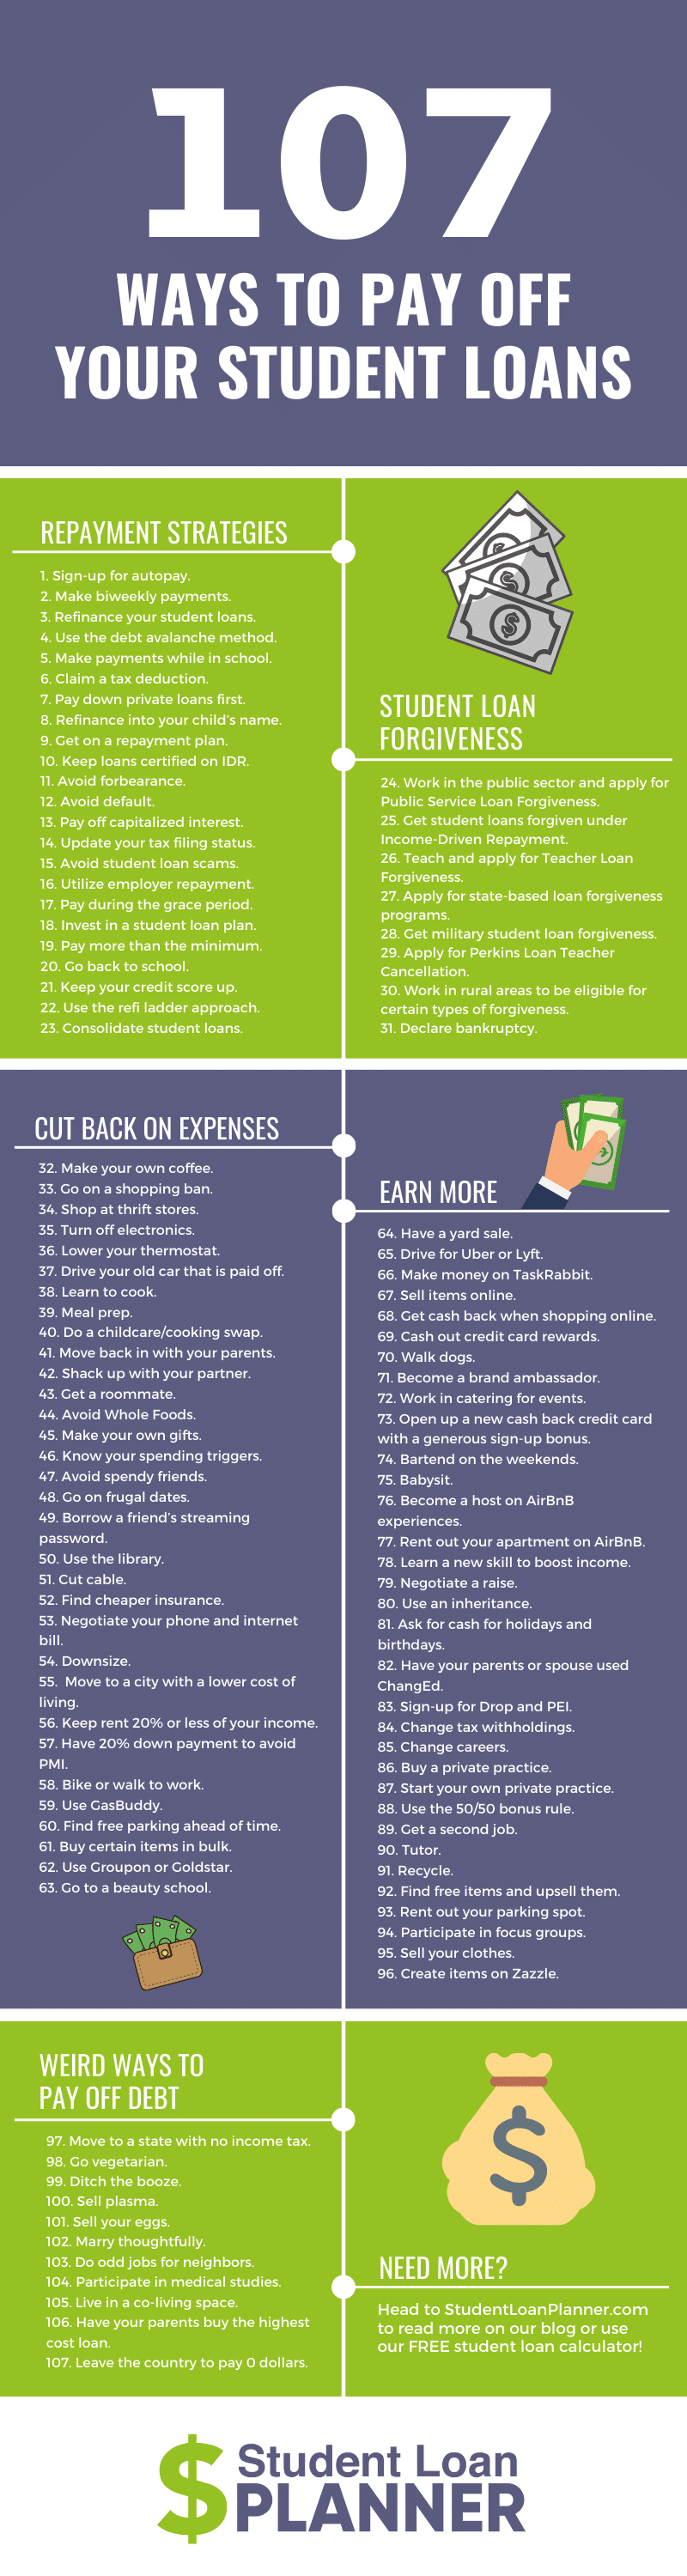
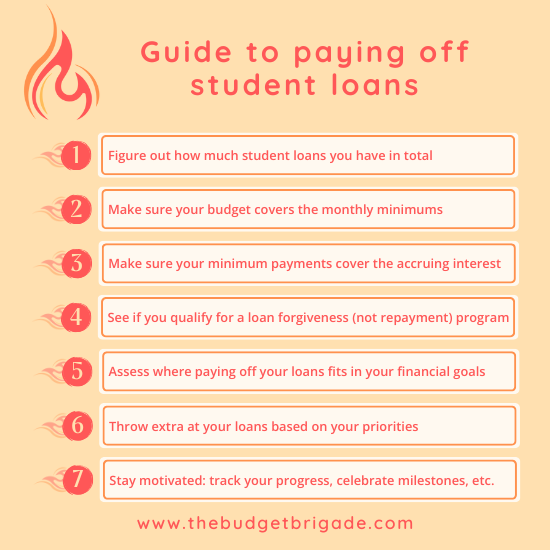
Regardless of when you decide to start repaying your loans, it's essential to have a strategy for managing your debt. Here are some tips to help you stay on track:
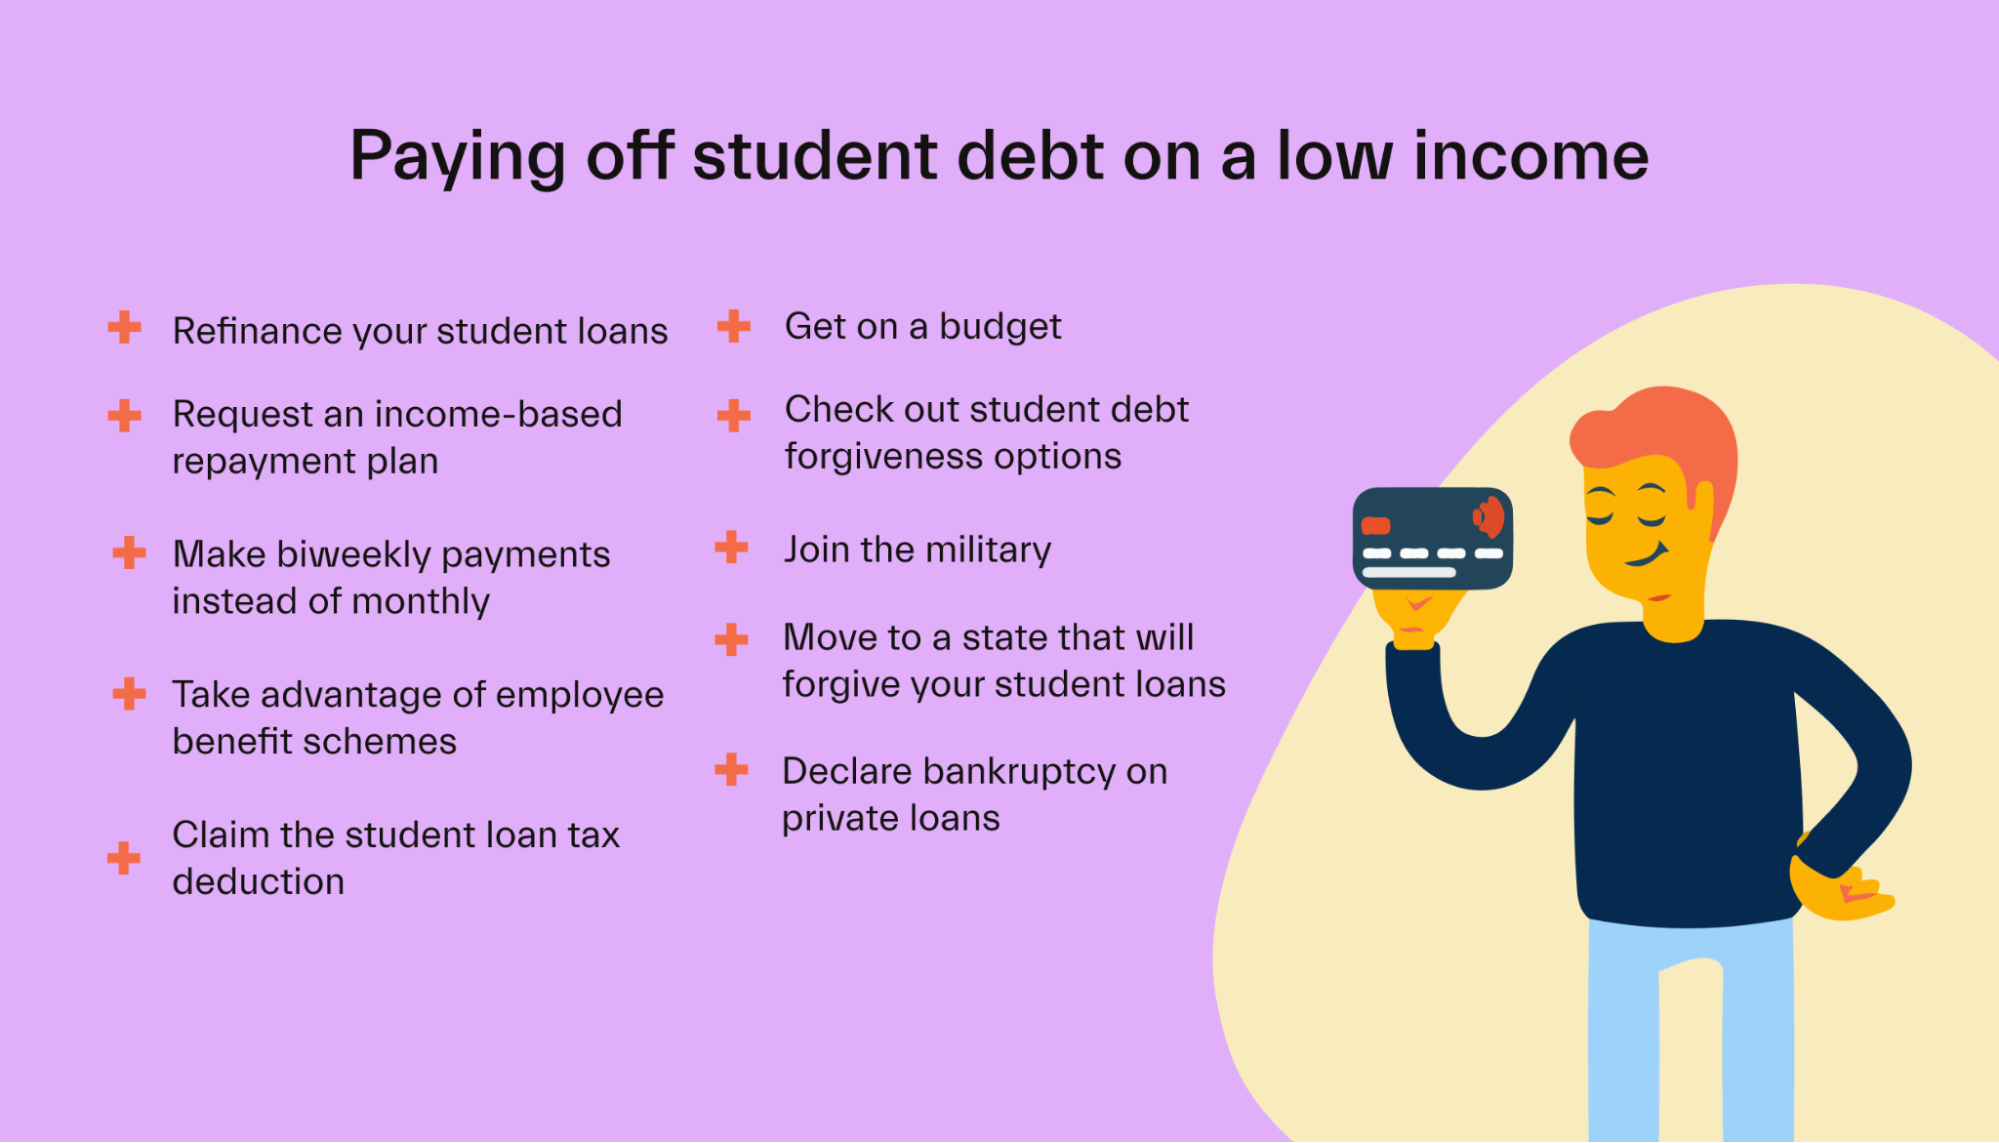
- Create a Budget: A budget can help you understand your income and expenses, allowing you to allocate funds towards your loan payments.
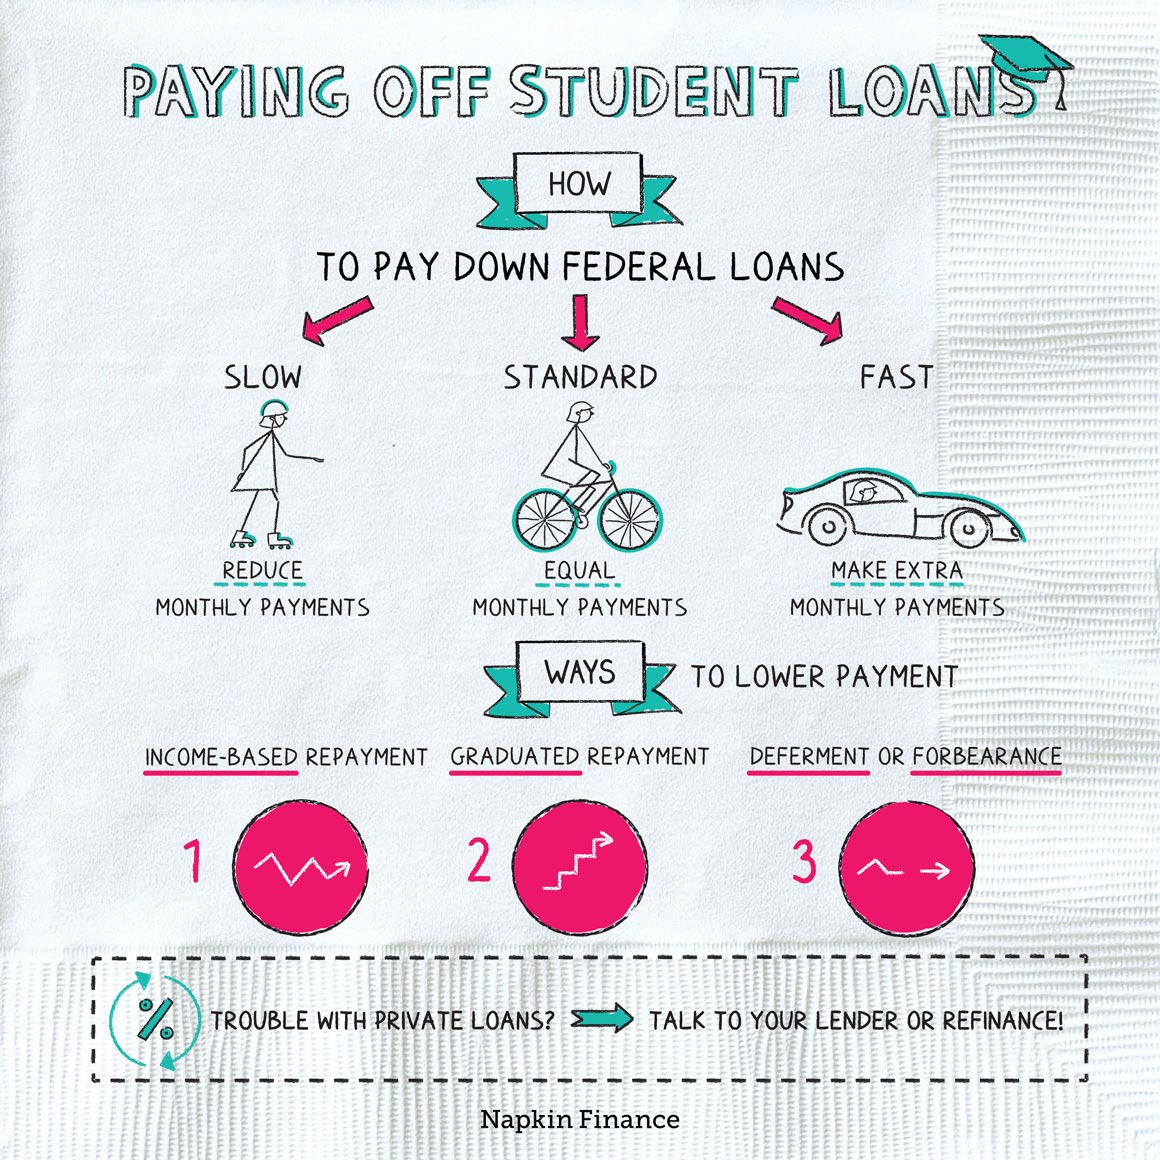
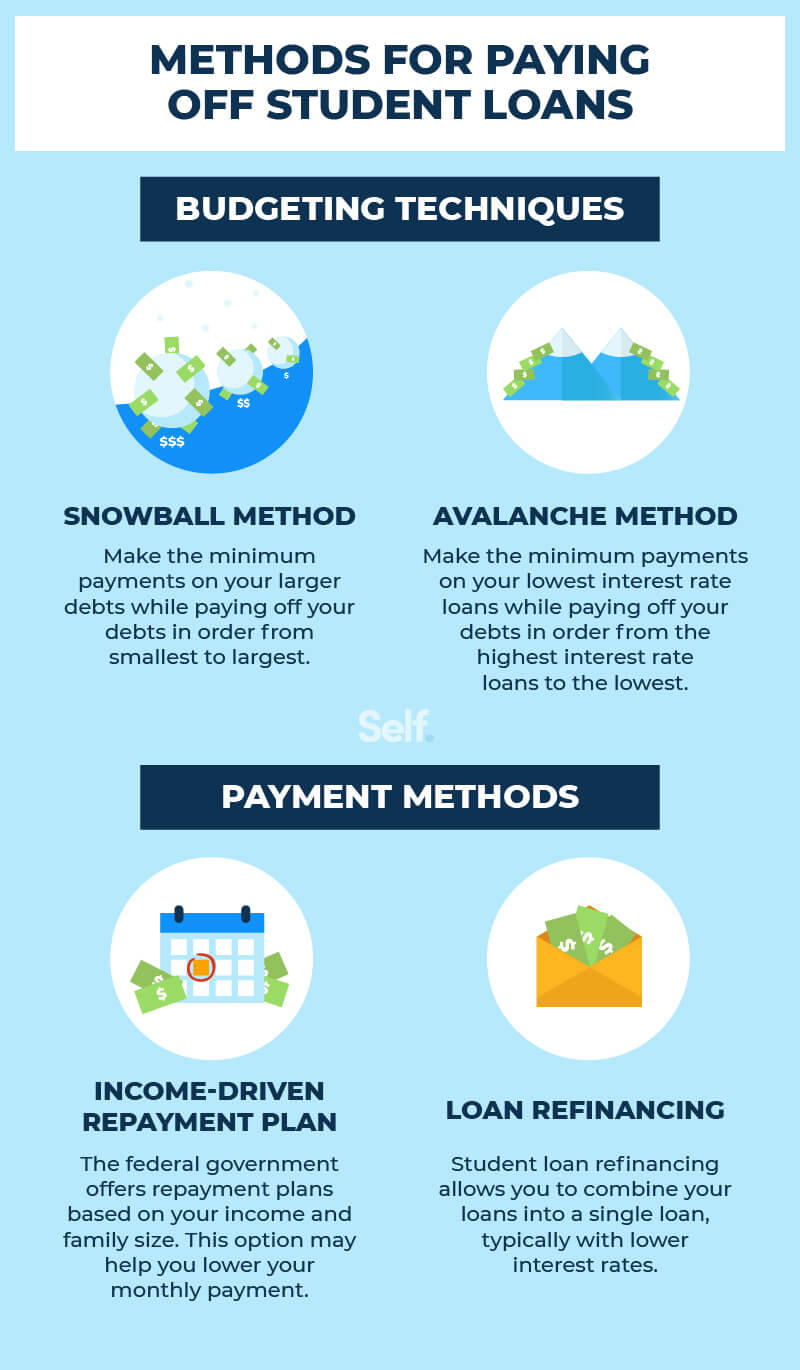
- Consider Income-Driven Repayment Plans: If you have federal loans, you may qualify for income-driven repayment plans, which cap your monthly payment at a certain percentage of your discretionary income.
- Explore Loan Consolidation: Consolidating your loans into a single loan can simplify your payments and may help you qualify for better interest rates or repayment terms.
- Make Extra Payments When You Can: Whenever you have extra money, putting it towards your loans can help you pay them off faster and save on interest.
Ultimately, the decision of when to start paying off your student loans is a personal one that depends on your unique financial situation. By understanding your loan terms and weighing the pros and cons of starting repayment early, you can make an informed decision that sets you on the path to financial success.