Understanding the Paradox: Why Good Accountants May Conduct Less Than Stellar Audits
In the realm of finance, accountants are often perceived as the gatekeepers of accuracy and reliability. Yet, even the most skilled and well-intentioned accountants can sometimes deliver subpar audit results. This article delves into the reasons behind this paradox, exploring the complex interplay of human nature, professional challenges, and systemic issues that can lead to less than optimal audit outcomes.
Lack of Independence and Objectivity
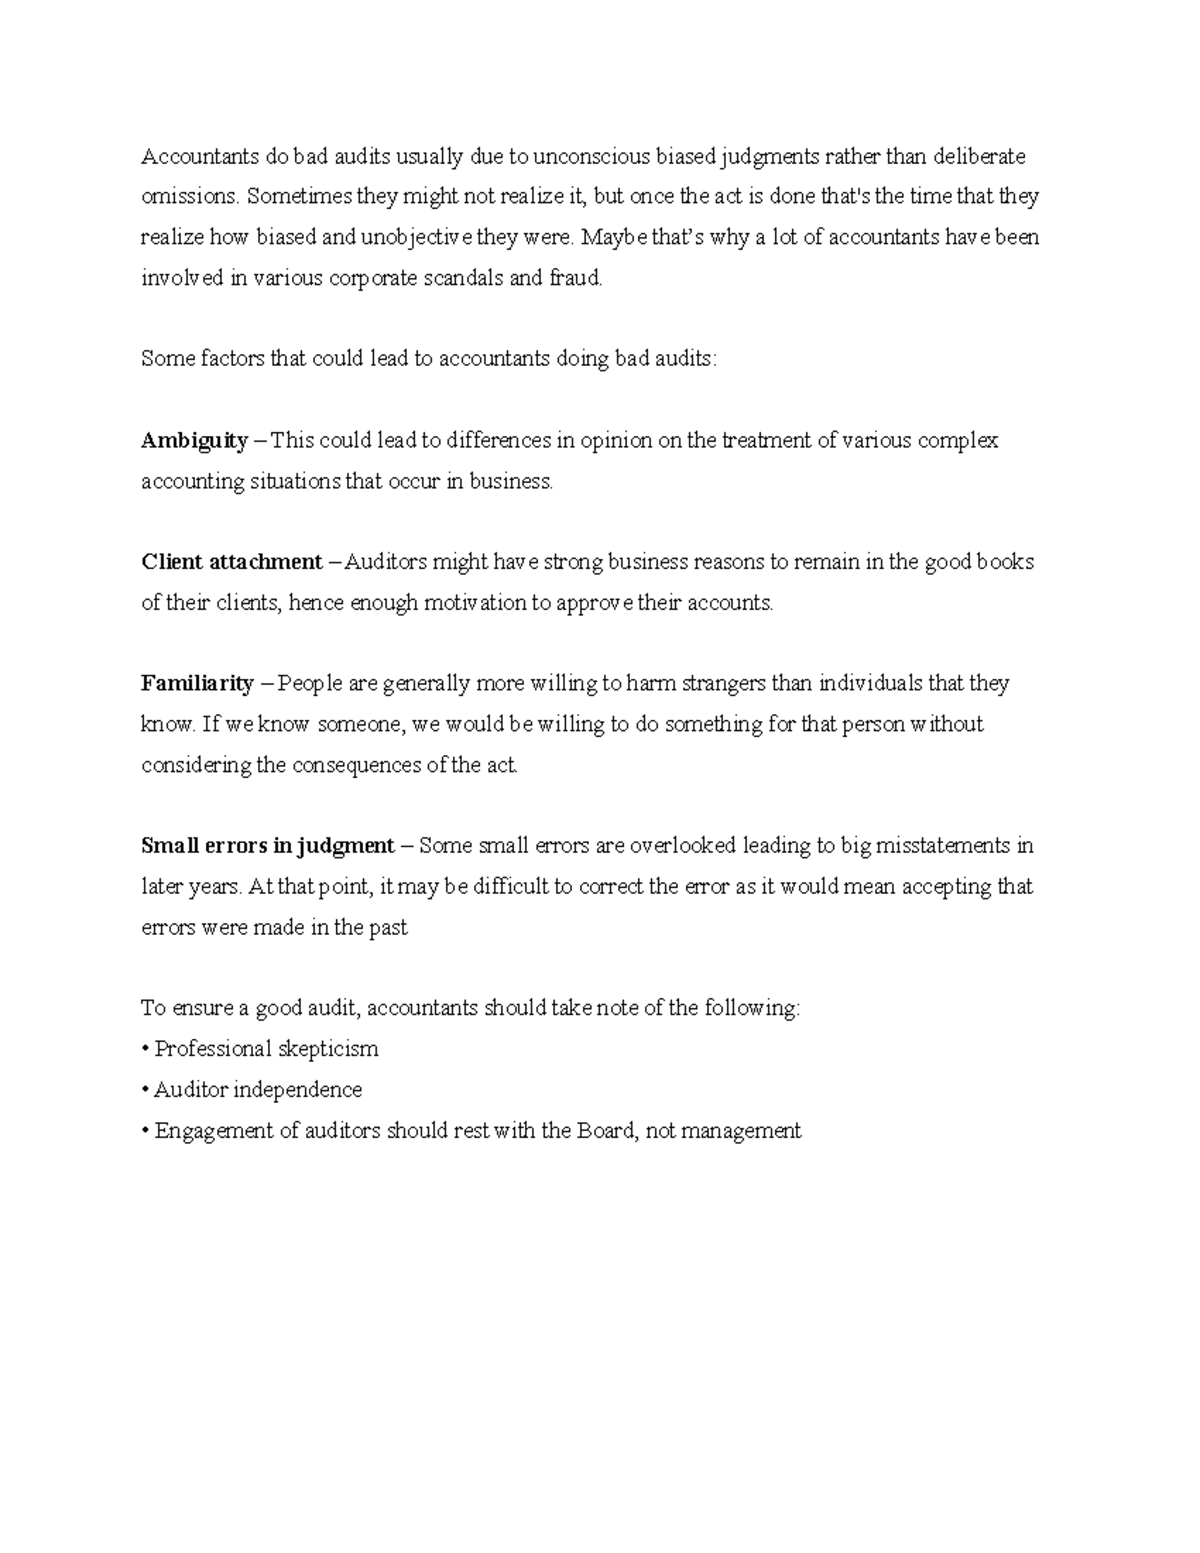
One of the primary reasons why good accountants might perform poorly in audits is a lack of independence and objectivity. This can stem from various factors:
- Internal Audits: When accountants audit their own work or that of their colleagues, they may unconsciously overlook errors or fail to challenge assumptions due to a desire to protect their team's reputation.
- Client Relationships: In external audits, accountants may feel pressured to maintain harmonious relationships with clients, leading them to downplay or ignore red flags.
Time Constraints and Workload Pressure
Accountants often face stringent deadlines and heavy workloads, which can compromise the quality of their audit work. Rushing through complex tasks can lead to oversights, while burnout can impact an accountant's ability to maintain the necessary level of vigilance and attention to detail.

Lack of Specialization and Training
While many accountants are generalists, some industries and companies have unique accounting practices or complex transactions that require specialized knowledge. If an accountant lacks the necessary training or experience in these areas, they may struggle to perform a thorough audit. Furthermore, without regular, relevant training, even experienced accountants may fall behind in their understanding of evolving accounting standards and best practices.
Groupthink and Confirmation Bias
Accountants are not immune to psychological biases that can affect their judgment. Groupthink, the tendency to follow the opinions of the group to maintain harmony, can lead accountants to overlook potential issues. Similarly, confirmation bias, the tendency to favor information that confirms preexisting beliefs or expectations, can cause accountants to miss red flags that contradict their initial assumptions.
Inadequate Audit Planning and Execution
A well-executed audit begins with a solid plan. However, poor planning can lead to inadequate sampling, insufficient testing, or overlooking high-risk areas. Moreover, even with a robust plan, poor execution, such as failing to document workpapers properly or not following up on identified issues, can result in a subpar audit.
Systemic Issues and Regulatory Pressures
Sometimes, the reasons for a poor audit lie not with the accountant but with systemic issues or external pressures. For instance,
- Regulatory Changes: Frequent changes in accounting standards can overwhelm accountants, leading to errors or oversights.
- Inadequate Resources: Understaffing, lack of technology, or insufficient budget can hamper an accountant's ability to perform a thorough audit.
Mitigating Risks: Best Practices for Accountants
To mitigate the risks of conducting a poor audit, accountants can adopt several best practices:
| Best Practice | How It Helps |
|---|---|
| Regular Training and Development | Keeps accountants up-to-date with changes in standards and best practices. |
| Independent and Objective Approach | Helps accountants maintain their professional skepticism and avoid biases. |
| Robust Audit Planning and Execution | Ensures that high-risk areas are adequately addressed, and workpapers are properly documented. |
| Regular Review and Quality Control | Helps identify and address any shortcomings in the audit process. |
In conclusion, while good accountants may sometimes conduct less than stellar audits, understanding the underlying reasons can help mitigate these risks. By adopting best practices and fostering a culture of professionalism, independence, and continuous learning, accountants can strive to deliver high-quality audits consistently.