Many retirees wonder how much extra income they can earn from Social Security after age 62—and the answer often surprises them. With strategic timing, delayed retirement benefits can significantly boost monthly income, enhancing financial stability in later years.
How Much Additional Income After Age 62?
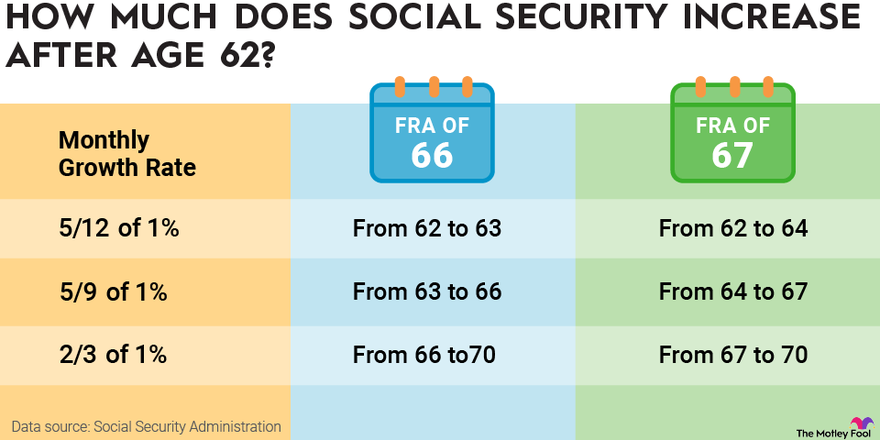
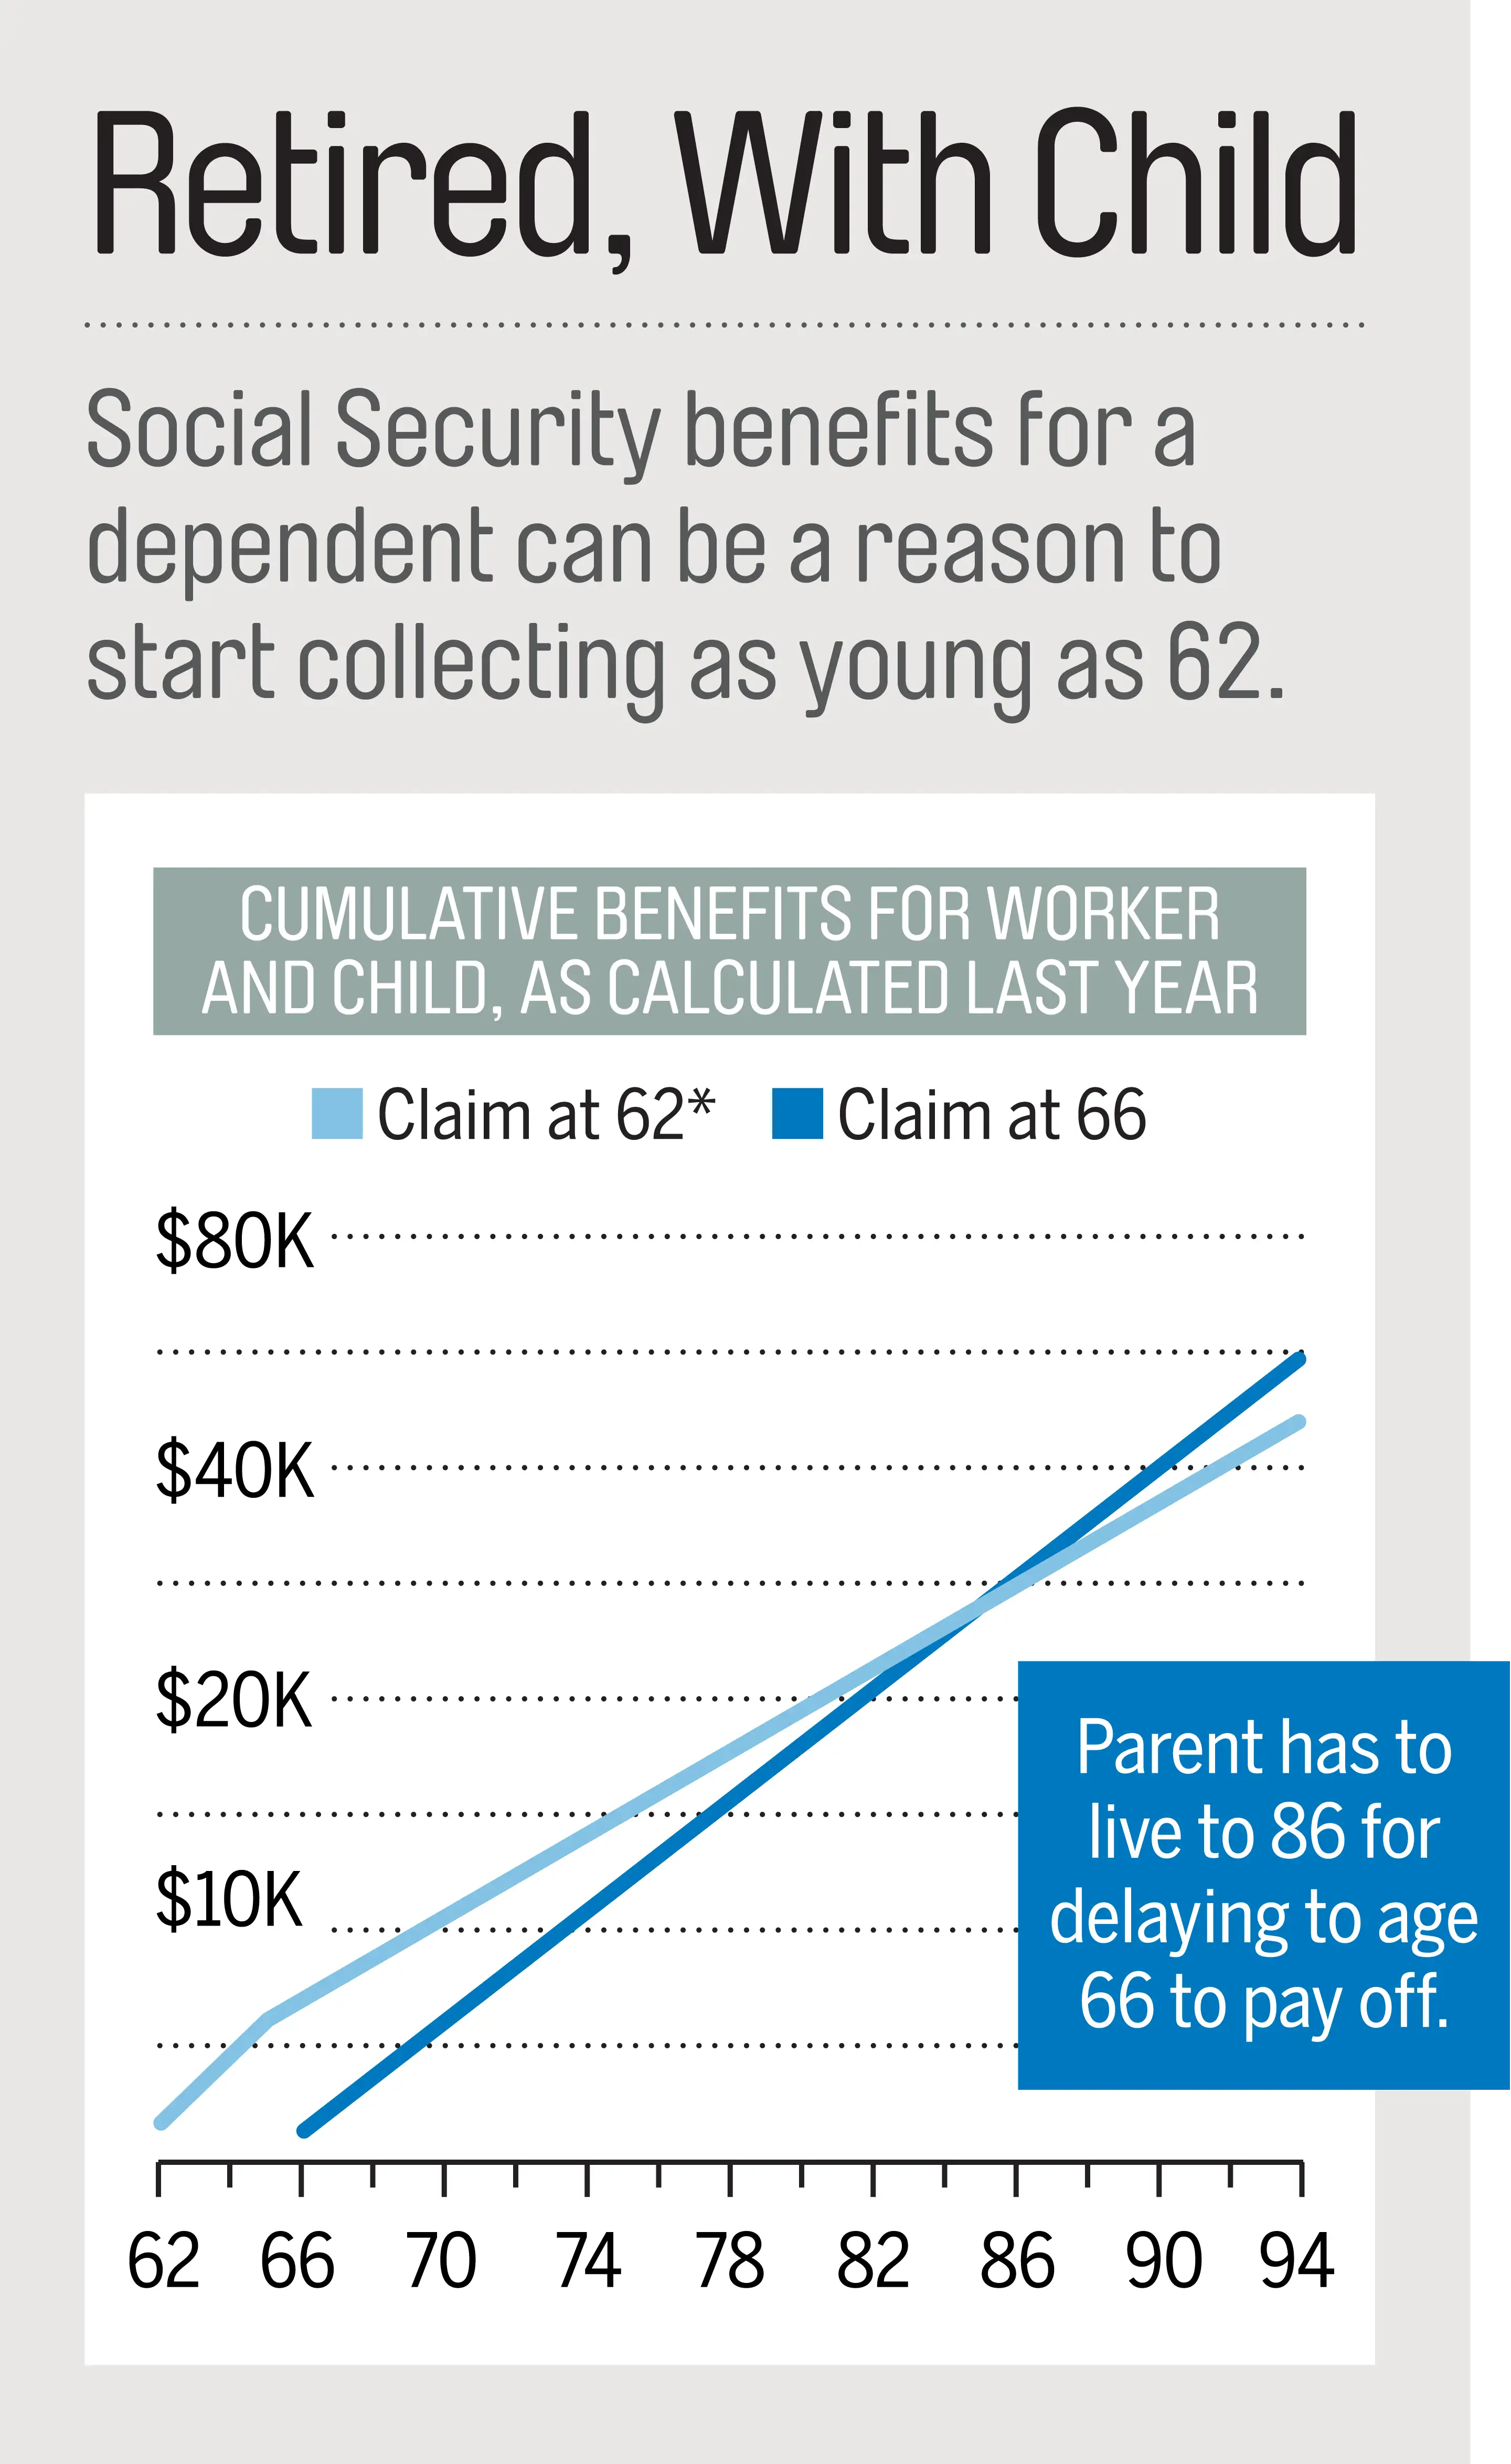
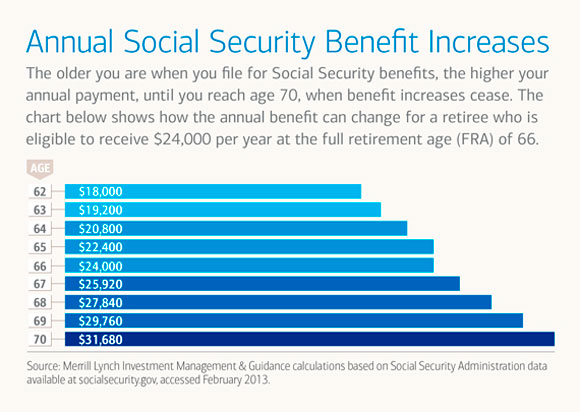
Starting at age 62, individuals begin claiming Social Security benefits at their full retirement age (FRA), typically between 66 and 67. Claiming before FRA reduces monthly payments, but delaying benefits past FRA increases them substantially. After turning 62, delaying benefits until age 70 can increase monthly income by up to 124% compared to claiming at 62. This additional income acts as a solid financial cushion, helping cover living expenses, healthcare, and unexpected costs throughout retirement.
Maximizing Delayed Retirement Credits
Every year benefits are delayed beyond FRA, Social Security credits accumulate—each delayed year adds one additional 8% to monthly payments, up to age 70. This compounding effect transforms moderate monthly income into a robust retirement income stream. Combined with other savings and pensions, this boosted Social Security payout strengthens long-term financial security and reduces reliance on personal savings during advanced age.
Practical Considerations for Maximum Gains
While delaying benefits increases income, it also requires careful planning. Health, life expectancy, and financial needs should guide timing choices. Consulting a retirement advisor can help tailor a strategy that balances delayed income with personal lifestyle goals. Proactive planning ensures retirees maximize their Social Security surplus, securing a more comfortable and confident retirement.

Conclusion: Unlock Greater Retirement Security
The additional Social Security income available after age 62—especially when delayed—represents a powerful tool for retirement planning. By understanding how delayed benefits increase monthly payments, retirees can significantly enhance their financial resilience. Start evaluating your options today to unlock the full potential of your Social Security benefits and build a more secure future.

Maximizing Social Security after age 62 isn’t just about delaying benefits—it’s about unlocking substantial extra income that strengthens retirement stability. Act now to optimize your retirement income and secure lasting financial peace of mind.

January 2, 2026 En español You can get Social Security retirement benefits and work at the same time. However, if you are younger than full retirement age and make more than the yearly earnings limit, we will reduce your benefits. Starting with the month you reach full retirement age, we will not reduce your benefits no matter how much you.
How much can you earn if you retire at 62 in 2024? If 2024 is the year you hit full retirement age, the income limit is $59,520, and 33% of anything over this limit will be held back from your Social Security check. Can I draw Social Security at 62 and still work full time after? ANSWER: Yes, you can. Key Points Delaying Social Security past 62 increases monthly benefits by 5% to 8% per year until age 70.

Claiming Social Security at 62 offers more years of benefits but reduces payments up to 30%. One of the most misunderstood Social Security issues is how working past age 62 affects retirement benefits. Ask an Advisor: How Much Money Can I Earn Working After Taking Social Security at Age 62? If you claim your benefit before hitting your full retirement age, you'll be subject to the earnings limit.
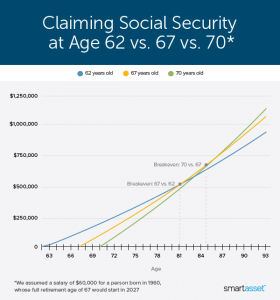
People under full retirement age can earn up to $23,400 in 2025 and $24,480 in 2026 while on Social Security without penalty. No cap after full retirement age. Claiming Social Security at 62 provides early income but comes with earnings limits that may reduce your benefits.
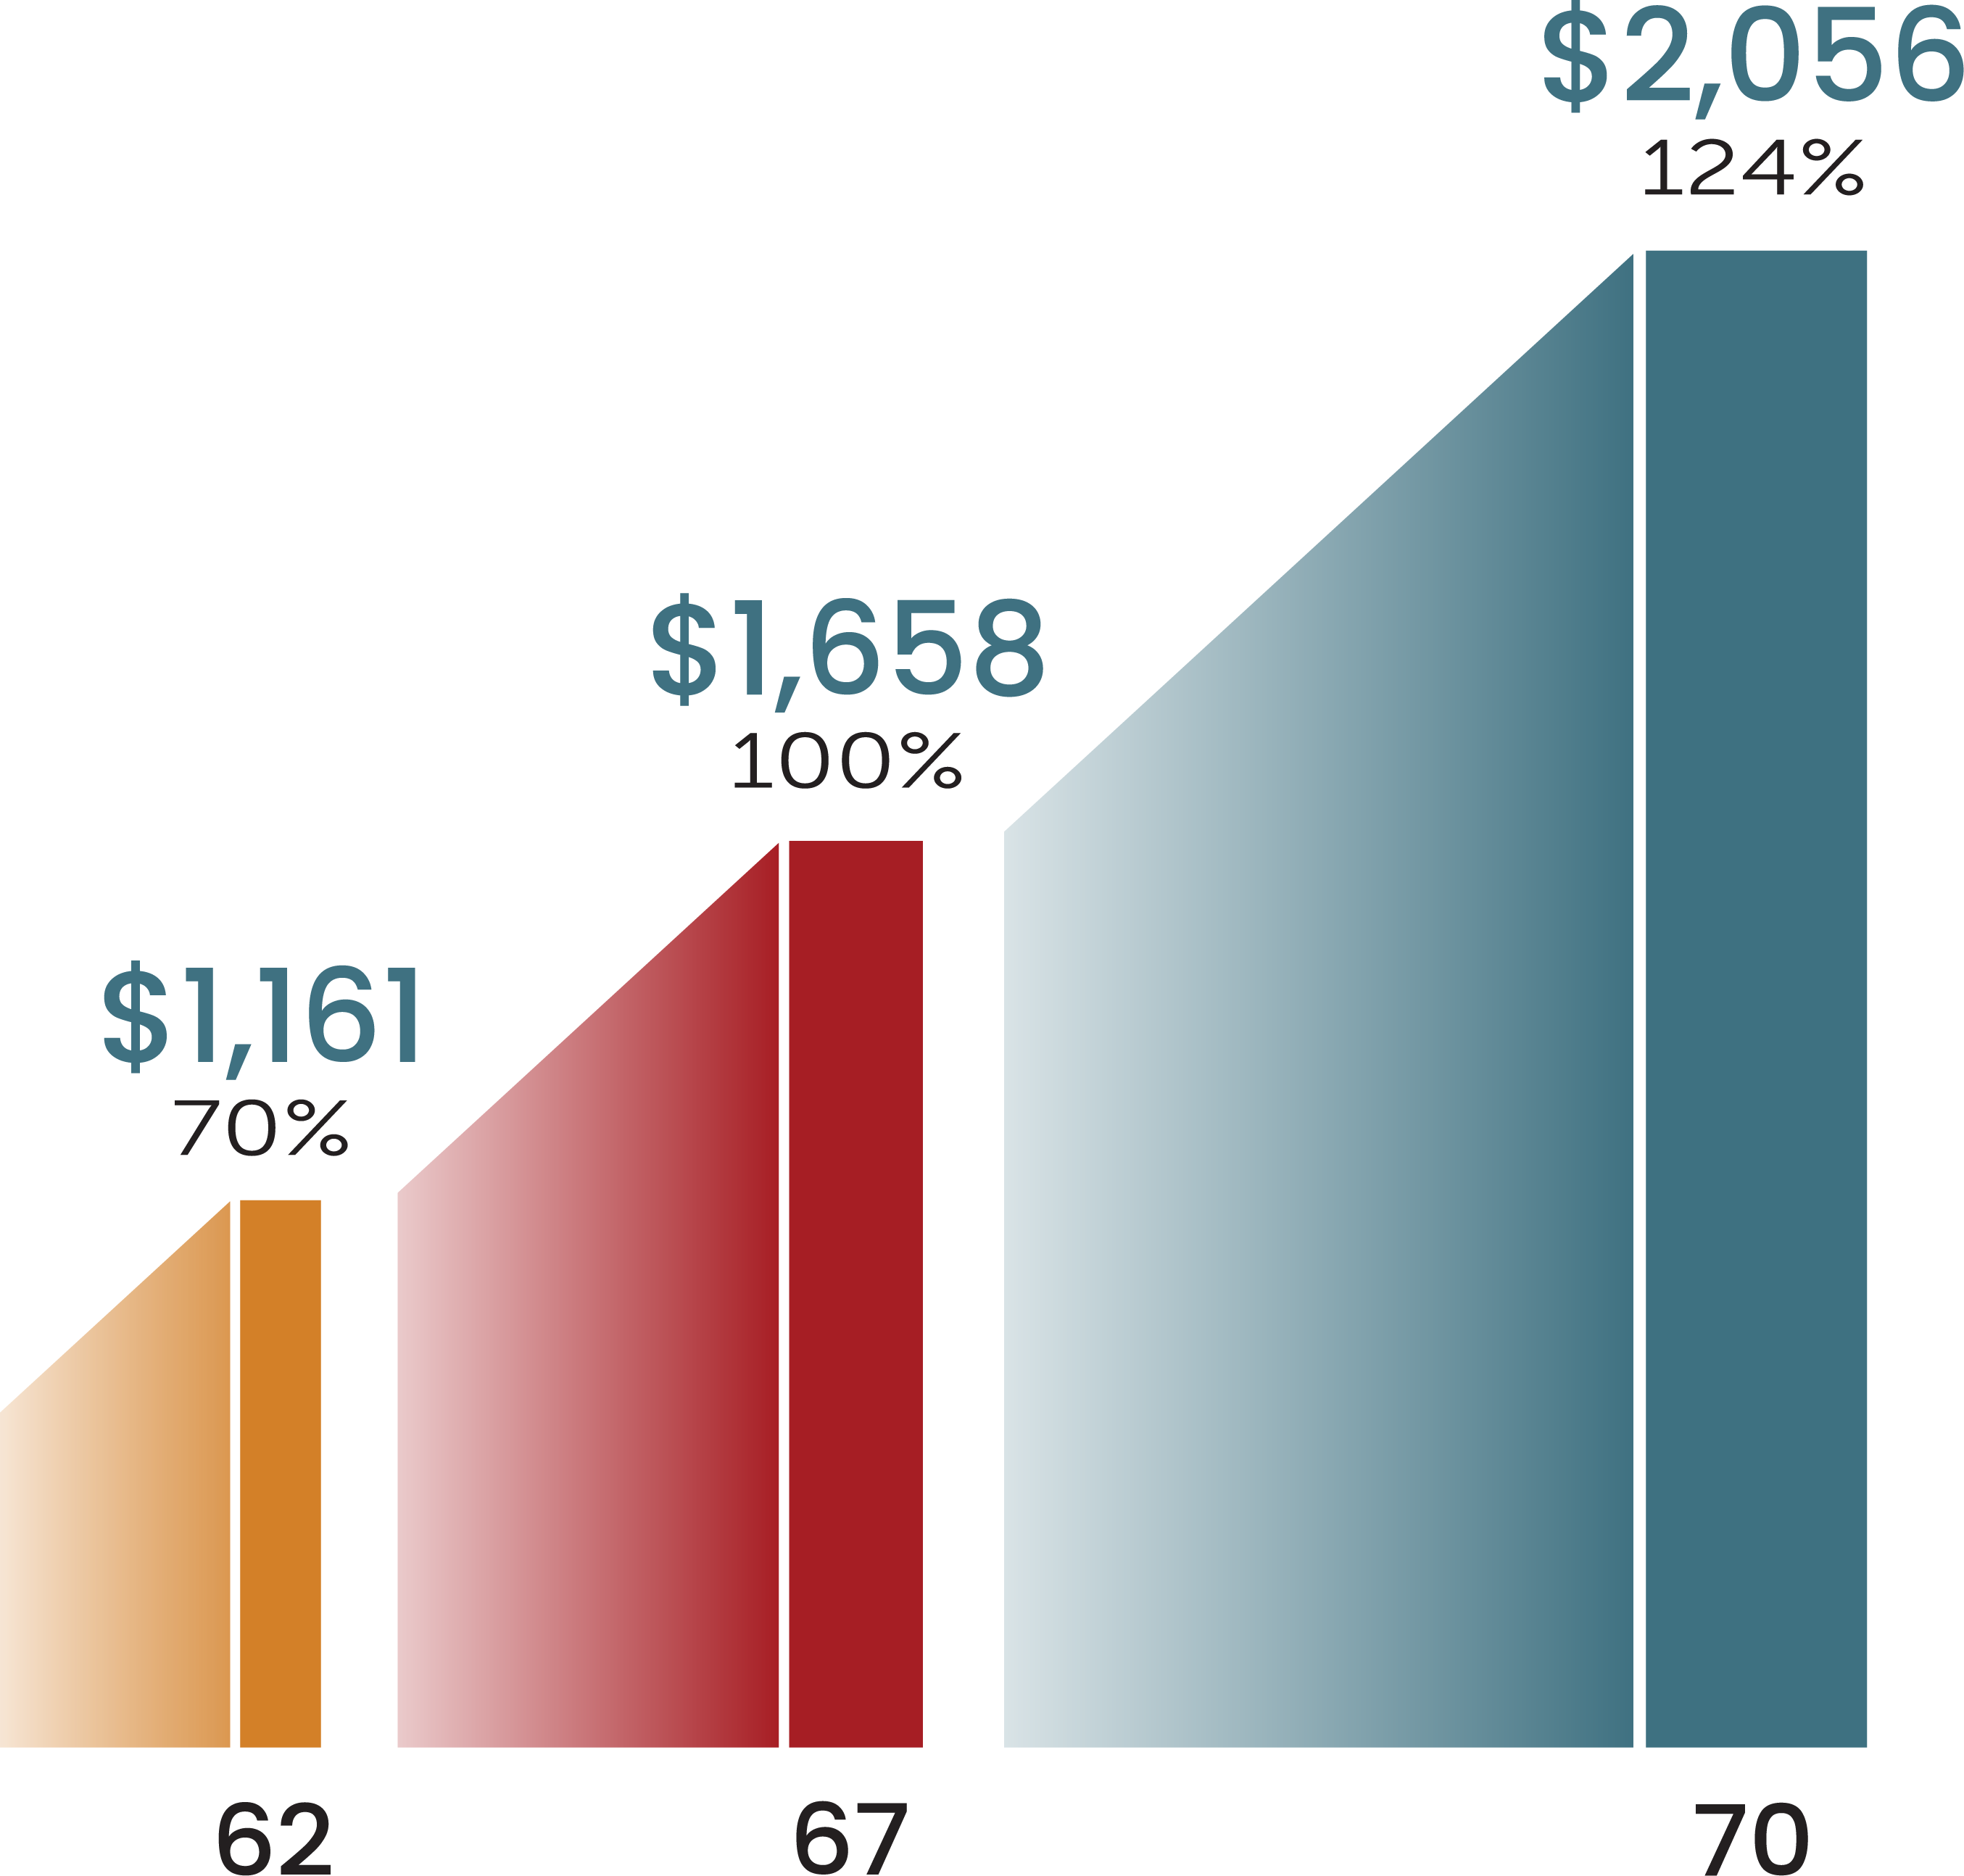
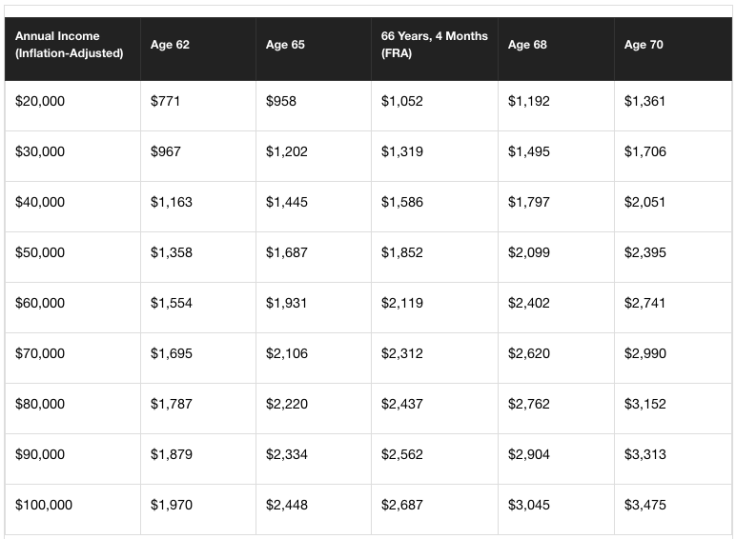
Learn how work and timing impact your payments. Before we tally the cost of filing for benefits at age 62, let's calculate the size of your Social Security check based on how much you currently earn. Continuing to work may have a benefit downside if you claimed Social Security early.
In the years before you reach full retirement age, you are subject to Social Security's earnings test, which reduces your benefits if your income from work exceeds a set limit ($24,480 in 2026). How much can I make while on Social Security? Once you've reached full retirement age, there's no SSA-defined limit to how much you can earn while receiving full Social Security benefits. If you're drawing benefits before that, however, you'll need to monitor your income, as making money while on social security can impact your bottom line.