The consumer electronics industry in 2017 reached a pivotal inflection point, marked by rapid innovation, shifting consumer expectations, and intensified global competition. As smart technology became increasingly embedded in everyday life, market dynamics evolved beyond traditional product cycles, pushing companies to rethink design, distribution, and data-driven services. This analysis examines key trends, challenges, and opportunities that defined the sector during this transformative year.
Market Growth and Global Expansion
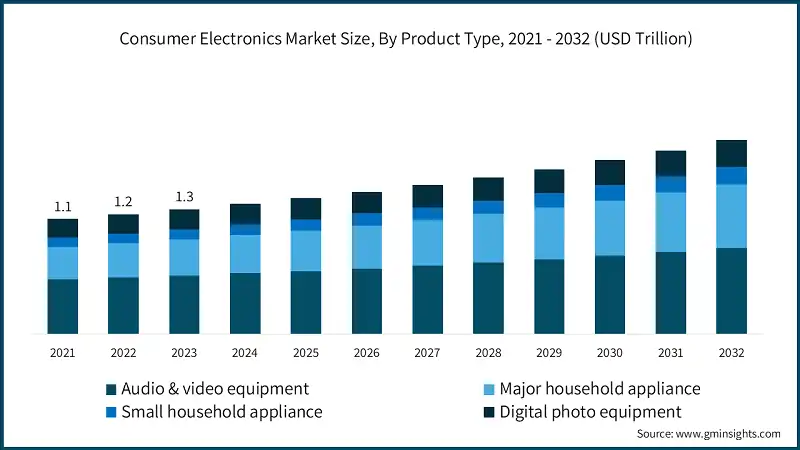
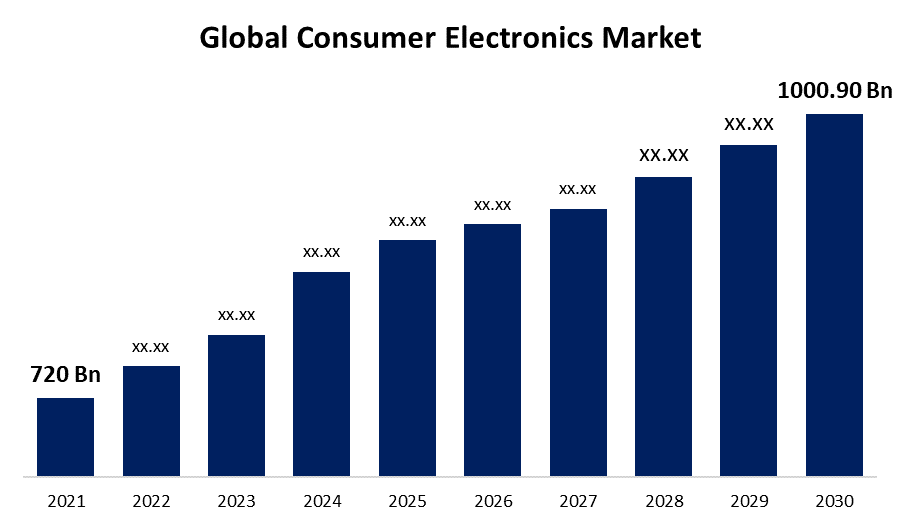
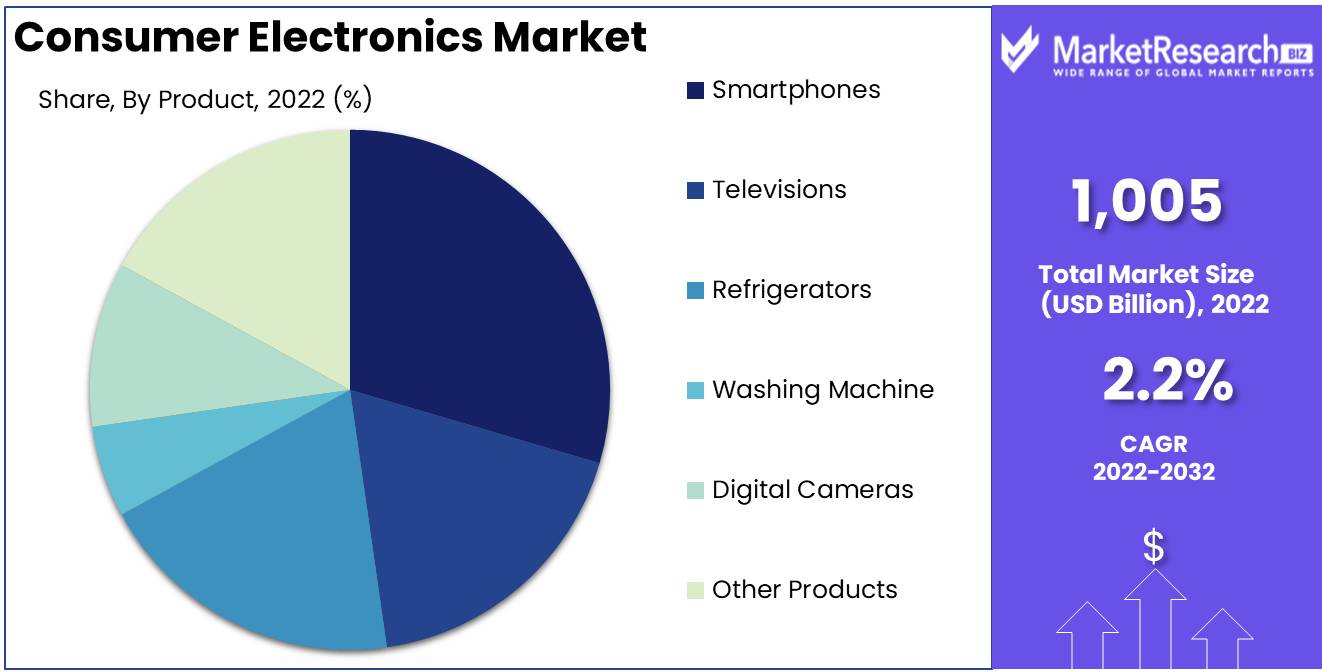
Global consumer electronics revenue surpassed $1 trillion in 2017, driven largely by emerging markets in Asia-Pacific and sustained demand for mobile devices. China and India led unit shipments, with smartphone penetration exceeding 50% in urban centers. Meanwhile, North America and Western Europe saw slower growth but higher average selling prices due to premiumization trends—consumers traded up for features like facial recognition and augmented reality. Wearables, smart home devices, and streaming media players also contributed significantly to year-over-year gains.
Key Product Categories and Innovation
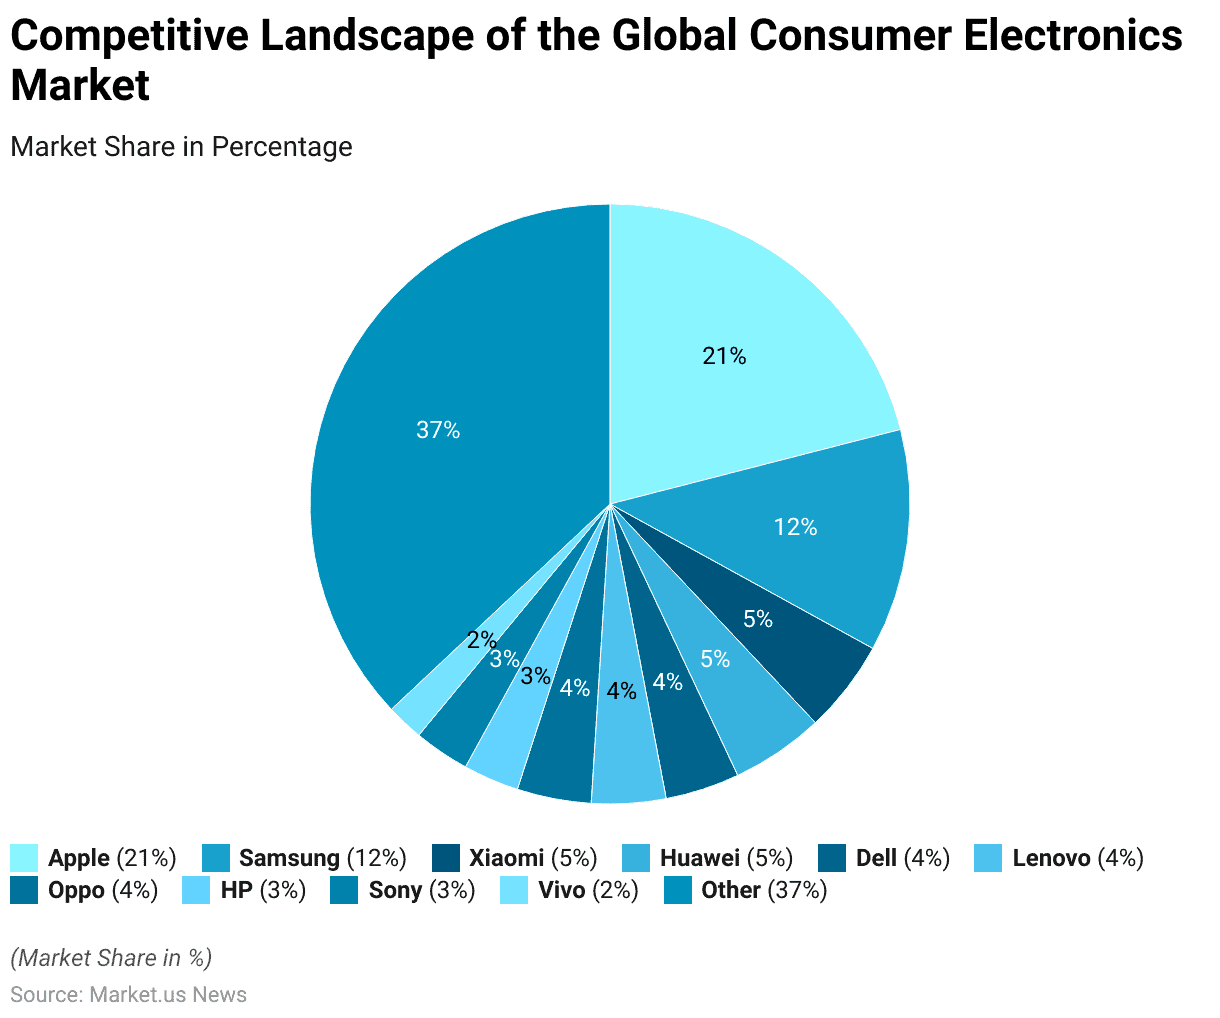
Smartphones remained the dominant category, with Apple’s iPhone X introducing Face ID and edge-to-edge OLED displays. Samsung and Huawei followed suit, emphasizing AI-powered cameras and on-device machine learning. Laptops continued to slim down, with ultrabooks and 2-in-1 convertibles gaining traction in enterprise and education sectors.

The Rise of Voice Assistants and Smart Home Ecosystems
Amazon Echo and Google Home sparked a wave of voice-activated smart speakers, prompting competitors to integrate third-party integrations and IoT protocols. By Q4 2017, over 30 million smart speakers were shipped globally. Security, interoperability, and privacy concerns remained barriers to mass adoption, but early data showed promising engagement with music streaming and home automation routines.
Supply Chain and Manufacturing Shifts
Component shortages—particularly in memory and display panels—forced several OEMs to adjust pricing strategies and sourcing. The price of DRAM and NAND flash surged 40% year-over-year, squeezing margins for mid-tier smartphone brands. Companies responded by diversifying suppliers and investing in vertical integration, a trend that would define the next decade’s competitive landscape.
Consumer Behavior and Digital Services
The line between hardware and services blurred in 2017. Subscription bundles became central to tech giants’ strategies. Apple doubled down on services like iCloud and Apple Music; Google expanded its YouTube Red (now Premium) offerings; and Microsoft leaned into Xbox Game Pass. Analysts noted a sharp increase in customer lifetime value from recurring revenue streams compared to one-time device sales.

Regulatory and Sustainability Pressures
E-waste regulation gained momentum, with the EU refining WEEE directives and several U.S. states passing right-to-repair legislation. Consumers increasingly favored brands with transparent recycling programs. Additionally, data privacy debates intensified—GDPR discussions were already shaping product roadmaps by late 2017, foreshadowing the 2018 compliance scramble.
Competitive Landscape and M&A Activity
2017 saw strategic acquisitions, such as Logitech acquiring Blue Microphones to bolster audio hardware, or Qualcomm’s attempted takeover of NXP for automotive IoT foothold (blocked in 2018). Meanwhile, Chinese manufacturers like Xiaomi and Oppo expanded globally through aggressive pricing and localized marketing, challenging incumbents in Southeast Asia and Eastern Europe.
Looking Ahead: Lessons from 2017
The industry’s pivot toward AI, services, and ecosystem lock-in set the tone for the late-2010s. Companies that balanced hardware innovation with digital services outperformed their peers. Supply chain resilience and regulatory foresight emerged as critical success factors. For stakeholders analyzing 2017, the consumer electronics sector proved that adaptability and user-centric design were no longer optional—they were the baseline for survival in an increasingly sophisticated global market.