Finding a blank endorsement on a check you are holding can immediately trigger a wave of uncertainty. This specific security feature, or lack thereof, dictates whether the paper can be negotiated further or if it is essentially frozen in place. Understanding the mechanics of this endorsement is crucial for anyone involved in the handling of paper payments, from individual recipients to corporate treasury departments.
What is a Blank Endorsement?
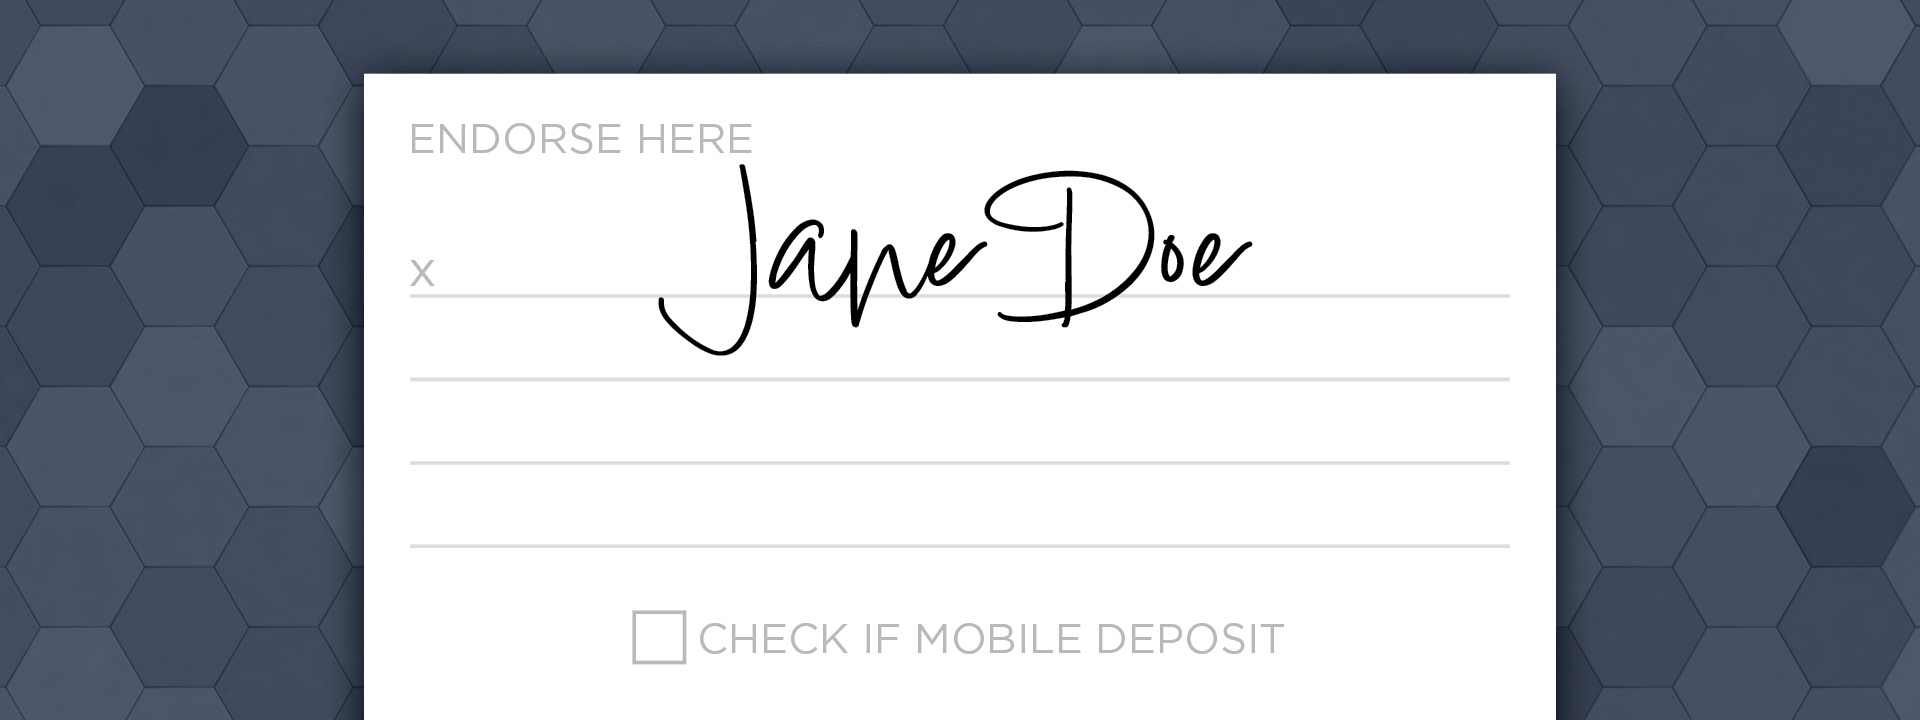
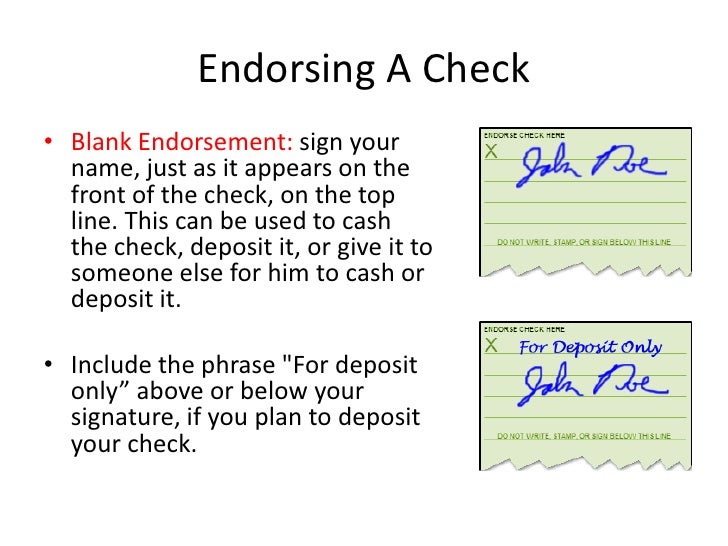
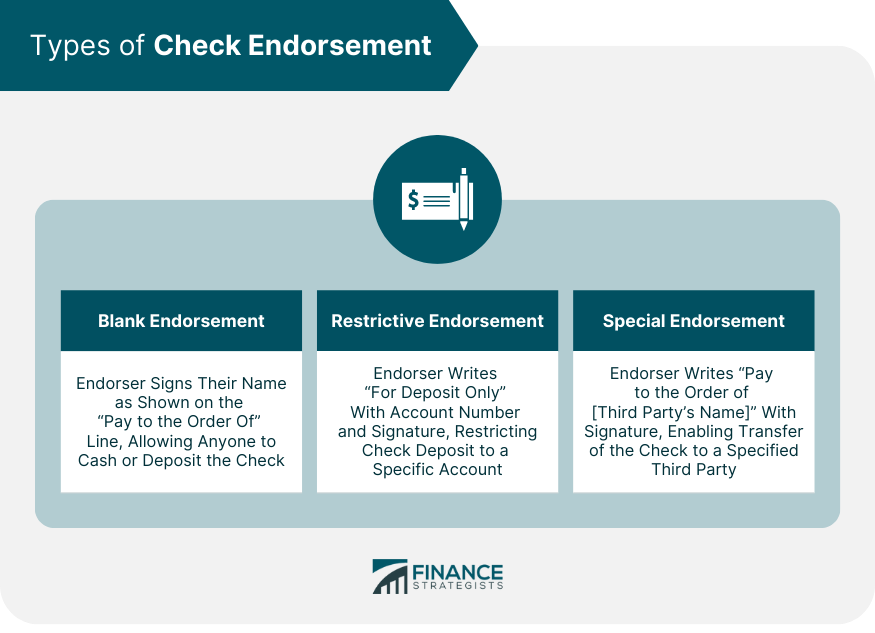
A blank endorsement occurs when the payee or holder of a check signs the back of the instrument without adding any restrictive instructions. Unlike a special endorsement, which names a specific third party or includes the phrase "For Deposit Only," a signature alone grants significant power to whoever possesses the check. This act transforms the check into a bearer instrument, meaning the bank is legally obligated to pay the item to whoever presents it, provided the signature matches the one on the front of the paper.
The Mechanics of Transformation
When a check is signed in blank, the legal title to the instrument shifts. The original payee effectively transfers possession rights to the check itself, rather than just the funds. Anyone who finds the check or receives it in good faith can then endorse it again—either in blank or specially—and present it for payment. Financial institutions are generally required to honor a check bearing a blank endorsement, as it represents the highest form of transferability in check processing.
| Endorsement Type | Language on Check | Risk Level |
|---|---|---|
| Blank | Just a signature | High |
| Special | "Pay to the order of [Name]" | Medium |
| Restrictive | "For Deposit Only" | Low |
Risks Associated with Blank Endorsements
The primary danger of a blank endorsement lies in its irreversibility and portability. Once a check is signed in blank, losing possession of it means potentially losing control over the funds. A dishonest finder could immediately cash the check or negotiate it to another party. For this reason, financial experts consistently advise individuals to avoid signing a check in blank until they are physically at the bank and ready to deposit or cash it, minimizing the window of exposure.
Liability for Financial Institutions
Banks operate under strict regulations regarding good faith payment. If a check with a blank endorsement is presented and the bank pays it in good faith—meaning they verified the signature and the account had sufficient funds—the bank typically has no liability to the original payee. The law generally protects the holder in due course who takes a properly endorsed instrument for value. This places the burden of safekeeping squarely on the individual who signed the check blank.
Proper Handling and Best Practices
To mitigate the risks, treat a blank endorsement like cash. If you receive a check that requires your signature, only sign the back when you are ready to finalize the transaction. If you need to endorse a check to give to a third party—such as when paying a bill with a third-party check—use a special endorsement that includes the recipient's name. This adds a layer of security, as the bank will know the intended recipient and can reject payment if the chain of custody is broken.

Dispute Resolution
In the event a check with a blank endorsement is lost or stolen, the situation becomes a complex dispute between the original payee, the bank, and the subsequent holder. Recovery of funds is difficult once the check has been cashed by a third party in good faith. Therefore, documentation and immediate communication with your financial institution are vital if the check goes missing after you have applied a blank endorsement.
Ultimately, a blank endorsement is a powerful legal tool that prioritizes liquidity and transferability over security. By recognizing the implications of that single signature, individuals and businesses can navigate the check clearing process with greater confidence and protect themselves against preventable financial loss.
How to Endorse Checks Explained | Blog | Academy Bank
How to Endorse a Check | Beginners Guide – Money Instructor

PPT - 4.02 C Check Writing & Endorsements PowerPoint Presentation - ID ...

ACCOUNTING 1 Cash Control Systems Chapter 5 Advanced

PPT - Checking Accounts PowerPoint Presentation, free download - ID:2888190

Restrictive Check Endorsement Example

PPT - Checks, Deposits, and Check Registers PowerPoint Presentation ...
How to Endorse a Check | PNC Insights

PPT - Checking Accounts and Banking Services PowerPoint Presentation ...

How to Endorse a Check | Check City Blog

How to Endorse a Check: Step-by-Step Guidance

How to Endorse a Check: A Step-By-Step Guide • Benzinga

How To Cash a Check: Save Money and Avoid Problems

How to Endorse a Check: A Step-By-Step Guide • Benzinga

3 Ways to Endorse a Check - wikiHow
Banking Basics PowerPoint
Money Basics Guide to Savings and Checking Accounts | MyCreditUnion.gov

Terms & Conditions | National Bank of Blacksburg | Blacksburg, VA

Endorsement Meaning Endorsement: Exploring The Significance Of
Check Endorsement | Definition, Types, How It Works