When taking on additional debt, understanding the full financial burden is essential—especially the post-tax cost of borrowing. While interest rates and principal amounts dominate initial calculations, the impact of taxes on interest expenses significantly shapes the real-world price of debt. This article breaks down the post-tax average cost of new debt, offering clarity for borrowers aiming to make informed financial decisions.

Understanding the Post-Tax Average Cost of Additional Debt
The post-tax average cost of additional debt reflects the true economic burden after accounting for tax deductions on interest payments. Unlike gross interest rates, which show nominal borrowing costs, the post-tax cost incorporates tax savings, delivering a more accurate picture of debt affordability. For example, a 6% interest rate on a loan in a 30% tax bracket results in an estimated 4.2% effective cost after tax benefits—this effective rate is the average cost borrowers should consider when evaluating new debt. Understanding this metric helps align borrowing strategy with long-term financial health.
How Tax Deductions Lower Effective Interest Expenses
Interest expense on certain debts—like mortgage interest or corporate bonds—often qualifies for tax deductions, reducing the net cost to the borrower. This tax shield effectively lowers the interest rate borrowers pay, lowering the post-tax expense compared to a similar loan without deductions. However, tax rules vary by jurisdiction and debt type, influencing how much relief is realized. Borrowers must assess applicable tax laws to accurately estimate their after-tax borrowing costs, ensuring realistic budgeting and investment decisions.
Factors Influencing the Average Post-Tax Cost of Debt
Several key factors determine the average post-tax cost of additional debt. First, the marginal tax rate plays a critical role—higher rates amplify the tax benefit of interest deductions, reducing effective costs. Second, the type of debt matters: home mortgages often offer substantial tax advantages, while credit card debt typically does not. Third, economic conditions and interest rate environments shift borrowing costs and tax planning strategies, impacting long-term debt efficiency. Finally, individual financial circumstances—such as deductions for state taxes or business expenses—can alter the real post-tax burden, making personalized analysis essential for accurate cost assessment.

Grasping the post-tax average cost of additional debt is vital for smart financial planning. By factoring in tax savings on interest, borrowers gain a realistic view of true borrowing expenses. This awareness supports better decisions around loans, investments, and risk management. Whether financing real estate, business expansion, or personal expenses, understanding post-tax debt costs empowers smarter, more sustainable financial choices in a tax-aware world.
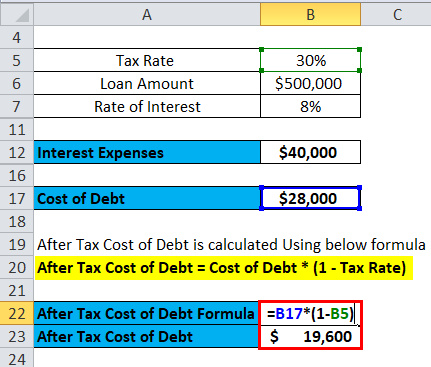
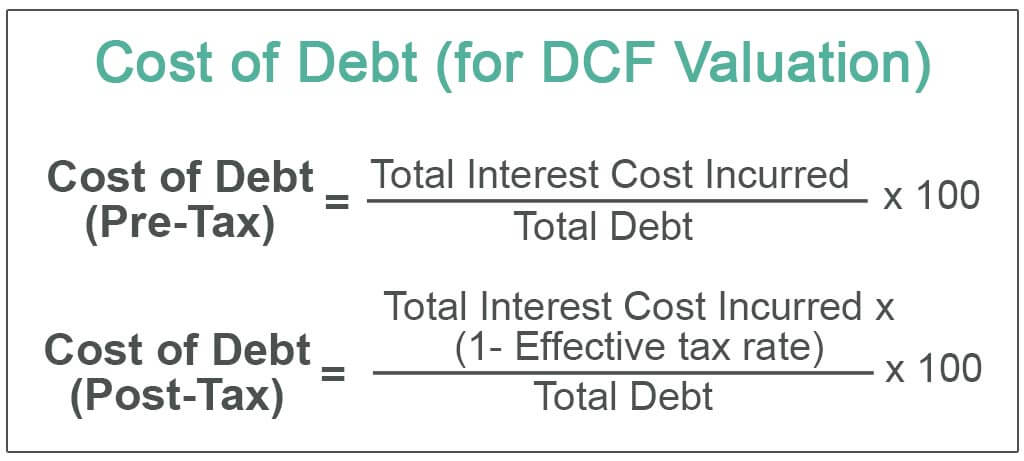
By calculating the effective tax rate, stakeholders can make more informed decisions regarding investments, as this rate directly impacts the after-tax cost of debt-a key component in the calculation of a company's weighted average cost of capital (WACC). To calculate the after-tax cost of debt, the following formula is used, After-tax COD This formula first deducts the tax savings from the cost of interest. The result is an effective interest cost after deduction, the division of this amount with the total volume of debt results in an effective interest rate.
To calculate the after-tax cost of debt, subtract a company's incremental tax rate from 100% and then multiply the result by the interest rate on the debt. For companies, interest expenses are tax-deductible, meaning there is a key difference between the pretax cost of debt and the after-tax cost of debt. Debt is one part of a company's capital.

Instantly compute your company's pre-tax and after-tax cost of debt using interest expense, total debt and tax rate - accurate, fast, finance. Weighted Average Cost of Capital: Essential for business valuation, this tool integrates the after-tax cost of debt to determine a company's overall cost of capital. Debt-to-Equity Ratio: Helps analyze a company's capital structure and understand the proportion of debt and equity financing.

The after-tax cost of debt directly lowers borrowing expenses by accounting for tax savings from interest deductions. This metric is critical for calculating your Weighted Average Cost of Capital (WACC), which determines the minimum return investors and lenders expect. The after-tax cost of the debt is computed as follows: $10,000 paid to the lender minus $3,000 of income tax savings equals a net cost of $7,000 per year on the $100,000 loan.
This means the after-tax cost is 7% ($7,000 divided by $100,000) per year. Using the example above, the after. Understanding your after-tax cost of debt is crucial for capital structure decisions, investment analysis, and comparing different financing options.
Business owners use this metric to evaluate whether to take on additional debt, refinance existing loans, or pursue equity financing alternatives. The after-tax cost of debt represents the total interest paid on debt minus savings on your income taxes. In other words, you're adjusting your total cost of debt to account for the effects of your tax rate.
Examples of cost of debt Your cost of debt is any interest expense you pay on any business loan. That can include interest payments for.