When it comes to maintaining optimal oral health, dental insurance is a cornerstone of the process. For those seeking flexibility and comprehensive coverage, Delta Dental 100 optional plans often emerge as a popular choice. These plans are designed to provide robust protection for a variety of dental procedures, allowing members to visit their preferred dentists with minimal hassle. Understanding what the "100" signifies and how the "optional" benefits stack up can make a significant difference in choosing the right coverage for you and your family.
Understanding Delta Dental 100 Basic Coverage
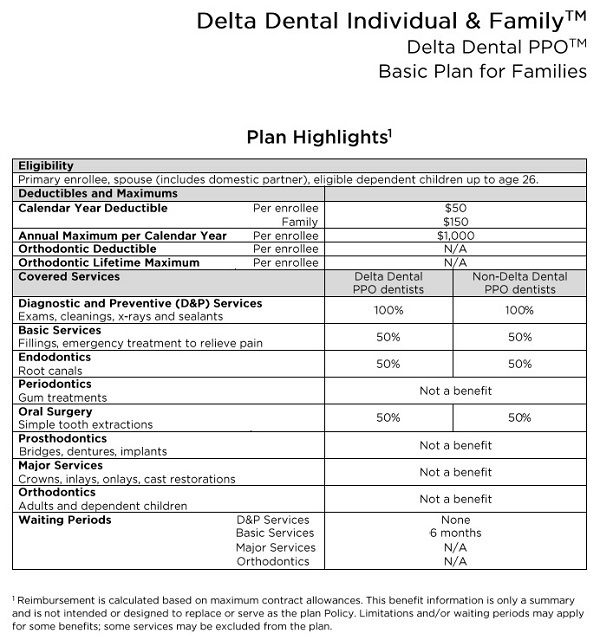
The "100" in Delta Dental plans generally refers to the percentage of coverage for specific categories of care. Under a standard Delta Dental PPO plan, the "100" typically indicates that the plan covers 100% of the costs for preventive and diagnostic services. This includes routine check-ups, cleanings, and X-rays. The goal is to encourage regular visits to the dentist, which is the foundation of preventing more costly and invasive treatments down the line. By covering these basics at 100%, the insurance company shifts its focus to prevention, which saves both the patient and the provider money in the long run.
However, the coverage percentages will vary for other categories. Basic procedures like fillings or simple extractions might be covered at 80%, while major services such as crowns, bridges, or root canals are often covered at 50%. Being aware of these tiers is essential for budgeting and understanding what you might owe out-of-pocket after the insurance pays its portion.

The "Optional" Rider: What It Means for You
The term "optional" in Delta Dental coverage typically refers to benefits or riders that can be added to your plan for an additional premium. These options might include orthodontic coverage for adults or enhanced annual maximums. These riders are not mandatory and allow the policyholder to tailor their dental insurance to their specific needs. For example, if a family has a history of needing braces or other orthodontic work, adding an orthodontic rider could be a wise investment. Conversely, if a young, healthy adult has never needed orthodontic work, they might forgo this optional rider to keep their monthly premiums lower.
How PPO Networks Impact Your Choices
Delta Dental operates primarily through a Preferred Provider Organization (PPO) network. When you enroll in a Delta Dental PPO plan with optional benefits, you gain access to a vast network of dentists who have agreed to discounted rates for plan members. Visiting a Delta Dental PPO dentist usually results in the lowest out-of-pocket costs. You also retain the freedom to visit out-of-network providers, but your costs will likely be higher and the coverage percentage lower compared to visiting an in-network provider. This dual-access model provides a balance between cost-saving and freedom of choice.
Navigating Annual Maximums and Waiting Periods
A critical component of any Delta Dental plan is the annual maximum, which is the total amount the insurance company will pay for your dental care in a single year. Standard plans might start at $1,000 to $1,500. Optional riders can sometimes increase this cap. Additionally, many Delta Dental plans include waiting periods for major services, often ranging from 6 to 12 months.

It is crucial to review the Summary of Benefits carefully before enrolling. Knowing when your coverage kicks in for specific treatments and how high your annual limit is ensures you aren't hit with unexpected bills, especially if you require extensive work soon after enrolling.
| Plan Feature | Typical Coverage | "Optional" Considerations |
|---|---|---|
| Preventive Care | 100% | Generally included in base plan. |
| Basic Procedures | 70% - 80% | Included in base plan. |
| Major Services | 50% | Riders may boost this percentage. |
| Orthodontics | Varies | Usually an optional extra. |
Making the Most of Your Delta Dental Membership
To truly maximize your Delta Dental 100 optional plan, take full advantage of the 100% preventive care. Schedule your cleanings and exams as soon as your waiting periods allow. Use your enhanced optional benefits proactively if you anticipate needing orthodontic work or hitting your annual maximum. Always verify that your dentist is in-network to ensure you receive the negotiated rates. By understanding the structure of the "100" coverage and the available optional riders, you can craft a dental insurance experience that keeps your smile healthy and your finances stable.