Programmatic buying, the automated auction‑based purchasing of digital ads, has transformed how brands reach audiences. While it started in display environments, it now spans multiple formats and screens. But one question still comes up repeatedly: which channel is programmatic buying most used in? Understanding the dominant channel requires looking not just at volume or spend, but also at reach, measurability, and how it fits into the broader digital ecosystem.
Digital Display Advertising Is the Core Programmatic Channel
Historically and still today, digital display ads—banners, interstitials, and rich media across websites and apps—are the foundation of programmatic buying. Most large demand‑side platforms (DSPs) and supply‑side platforms (SSPs) were built for display inventory first. That legacy shapes where programmatic buys happen and where the majority of automated auction‑based spend flows.
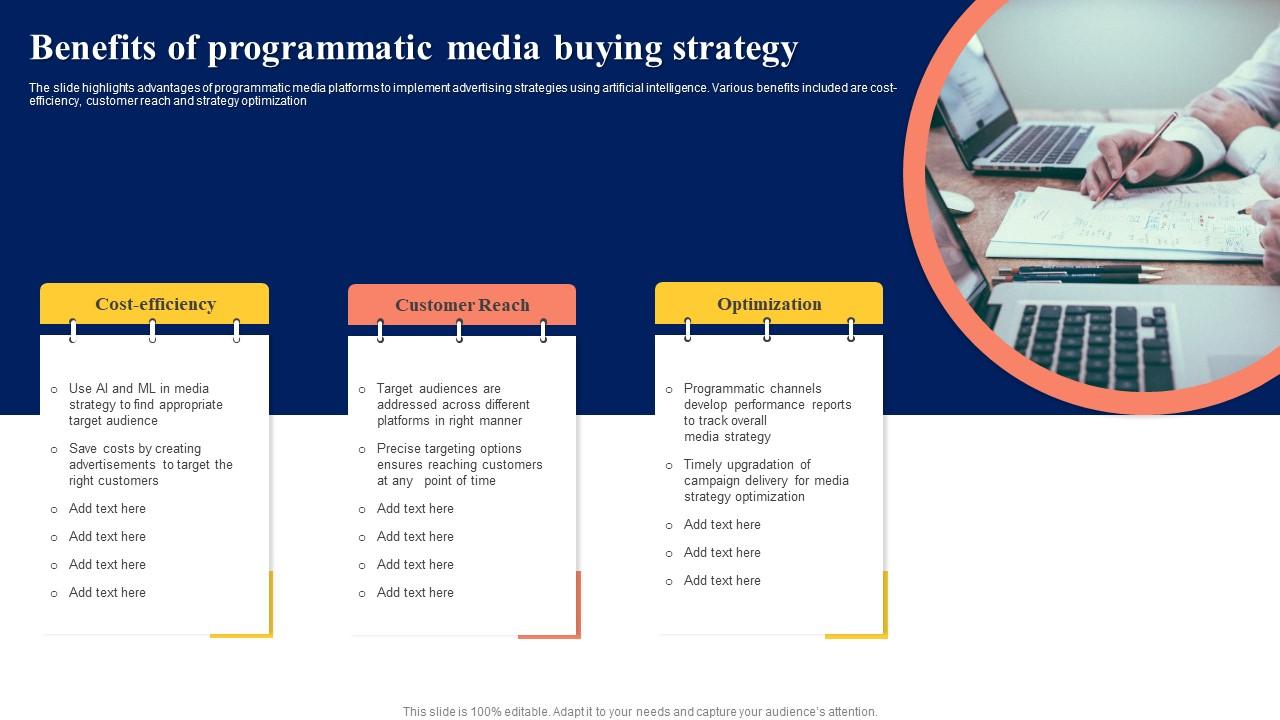
Easy data targeting (demographics, interests, context, behavior, and retargeting pixels) made display the natural home of early programmatic campaigns. Advertisers could:
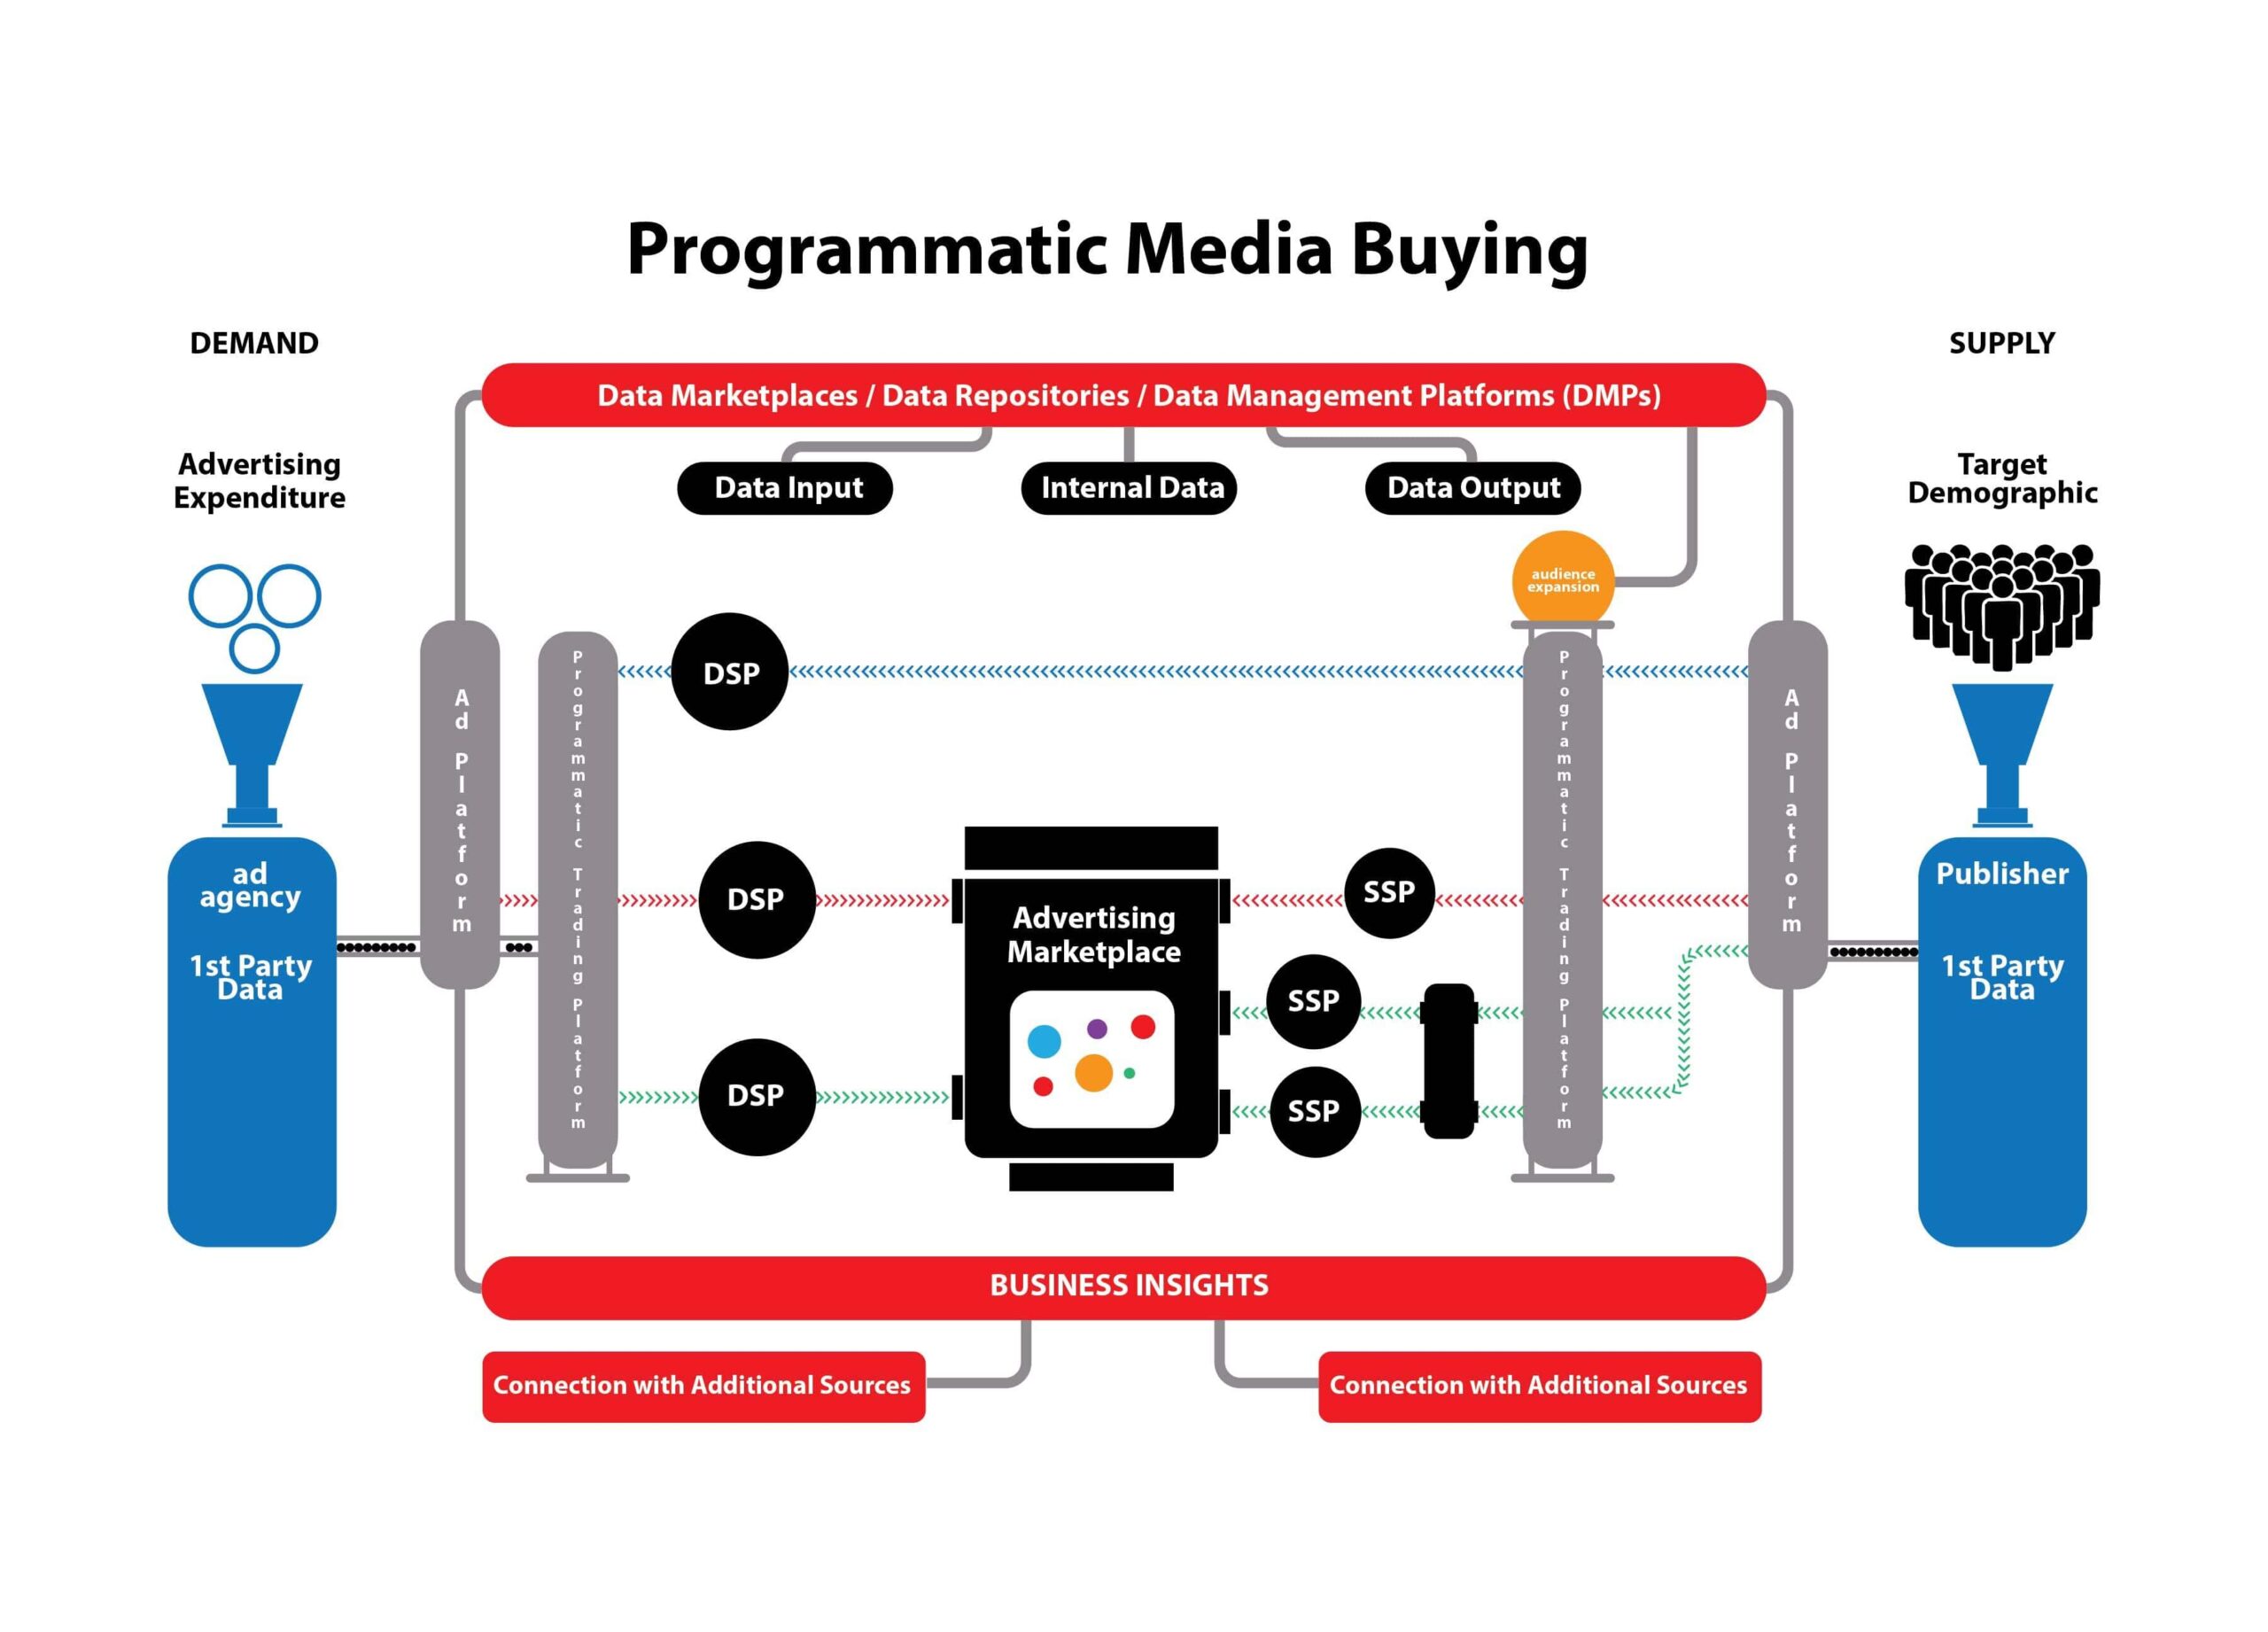
- Use first‑ and third‑party data to define and refine audiences
- Layer on brand‑safety and viewability controls
- Track measurable actions such as clicks, leads, and conversions
- Optimize bids in real time based on performance signals
Because of that maturity and flexibility, display remains the primary entry point into programmatic for brands converting from manual media buying to automated optimization.
Why Display Leads Over Video, Mobile, or Social
Mobile in‑app and mobile web may be growing faster in some markets, but display is still where most programmatic infrastructure, guidelines, and measurement standards were codified. Several practical reasons explain this:
- **Inventory scale**: Tens of millions of websites and thousands of apps expose display units, giving demand‑side buyers enormous supply.
- **Ad formats**: Display evolved from static banners to rich media, expandable formats, and native‑style creatives that mimic editorial content, while staying within a standardized ecosystem.
- **Integration**: Most ad servers, verification tools, and attribution models were built around display.
Video (CTV/OTT, in‑stream, and out‑stream) is often the fastest‑growing programmatic segment, yet total spend and transaction volume still largely tilt toward standard display inventory and its extended native placements.

Mobile and Video Are Catching Up—but Not Yet Ahead
When people ask if mobile or video is now the #1 programmatic channel, the story depends on the market and metric:
- In regions with high smartphone penetration, mobile ad spend and impressions are very large.
- In some verticals—especially entertainment and CTV—programmatic video budgets now rival or exceed display for top advertisers.
However, on a global and cross‑industry basis:
- Most DSPs still allocate a large share of their auction traffic to classic display units across desktop and mobile web.
- Measurement and fraud controls are still more standardized and mature for display than for many newer formats.
So while mobile and video are critical and growing fast, they have not yet displaced display as the primary programmatic channel when considering total spend, number of campaigns, and breadth of adoption across verticals.
How Channels Compare in Programmatic Buying
Below is a simplified view of how major digital channels stack up in terms of programmatic adoption, relative spend share, and infrastructure maturity. This is a general industry‑level snapshot, not a single official source; exact numbers vary by year and market.
| Channel | Dominant Ad Formats | Typical Use Cases | Programmatic Spend Share (Approx.) | Maturity (Tech + Measurement) | Trends |
|---|---|---|---|---|---|
| Digital Display (Web + In‑App Banners) | Standard banners, rich media, native‑style ads | Brand awareness, retargeting, performance campaigns | High (often 40–60%) | Very mature | Native and privacy‑centric targeting |
| Digital Video (In‑Stream, CTV/OTT) | Pre‑roll, mid‑roll, CTV/OTT impressions, out‑stream | Mid‑funnel engagement, premium brand campaigns and DR | Medium–High (20–35%) | Mature and evolving (VAST/VPAID/VUID) | Fast growth, identity challenges |
| In‑App & Mobile Web | Banners, interstitials, rewarded video | App installs, retargeting, local campaigns | Share overlaps with Display & Video | Very mature | PrivacySandbox & ATT impacts |
| Social (Programmatic via APIs) | Native feeds, stories, short video | Consideration, engagement, commerce | Significant but semi‑owned ecosystems | Moderate–Mature (owned platforms) | More API‑based programmatic integration |
| DOOH & Other Emerging Screens | Digital billboards, screens in transport/retail | Upper‑funnel brand, location‑based campaigns | Low–Medium | Early–Moderate | Growth as it integrates with DSPs |
This table shows why many media experts still point to display as the core programmatic channel: it has the largest breadth of supply, longest track record, and standardized practices.
What “Channel” Really Means in Programmatic
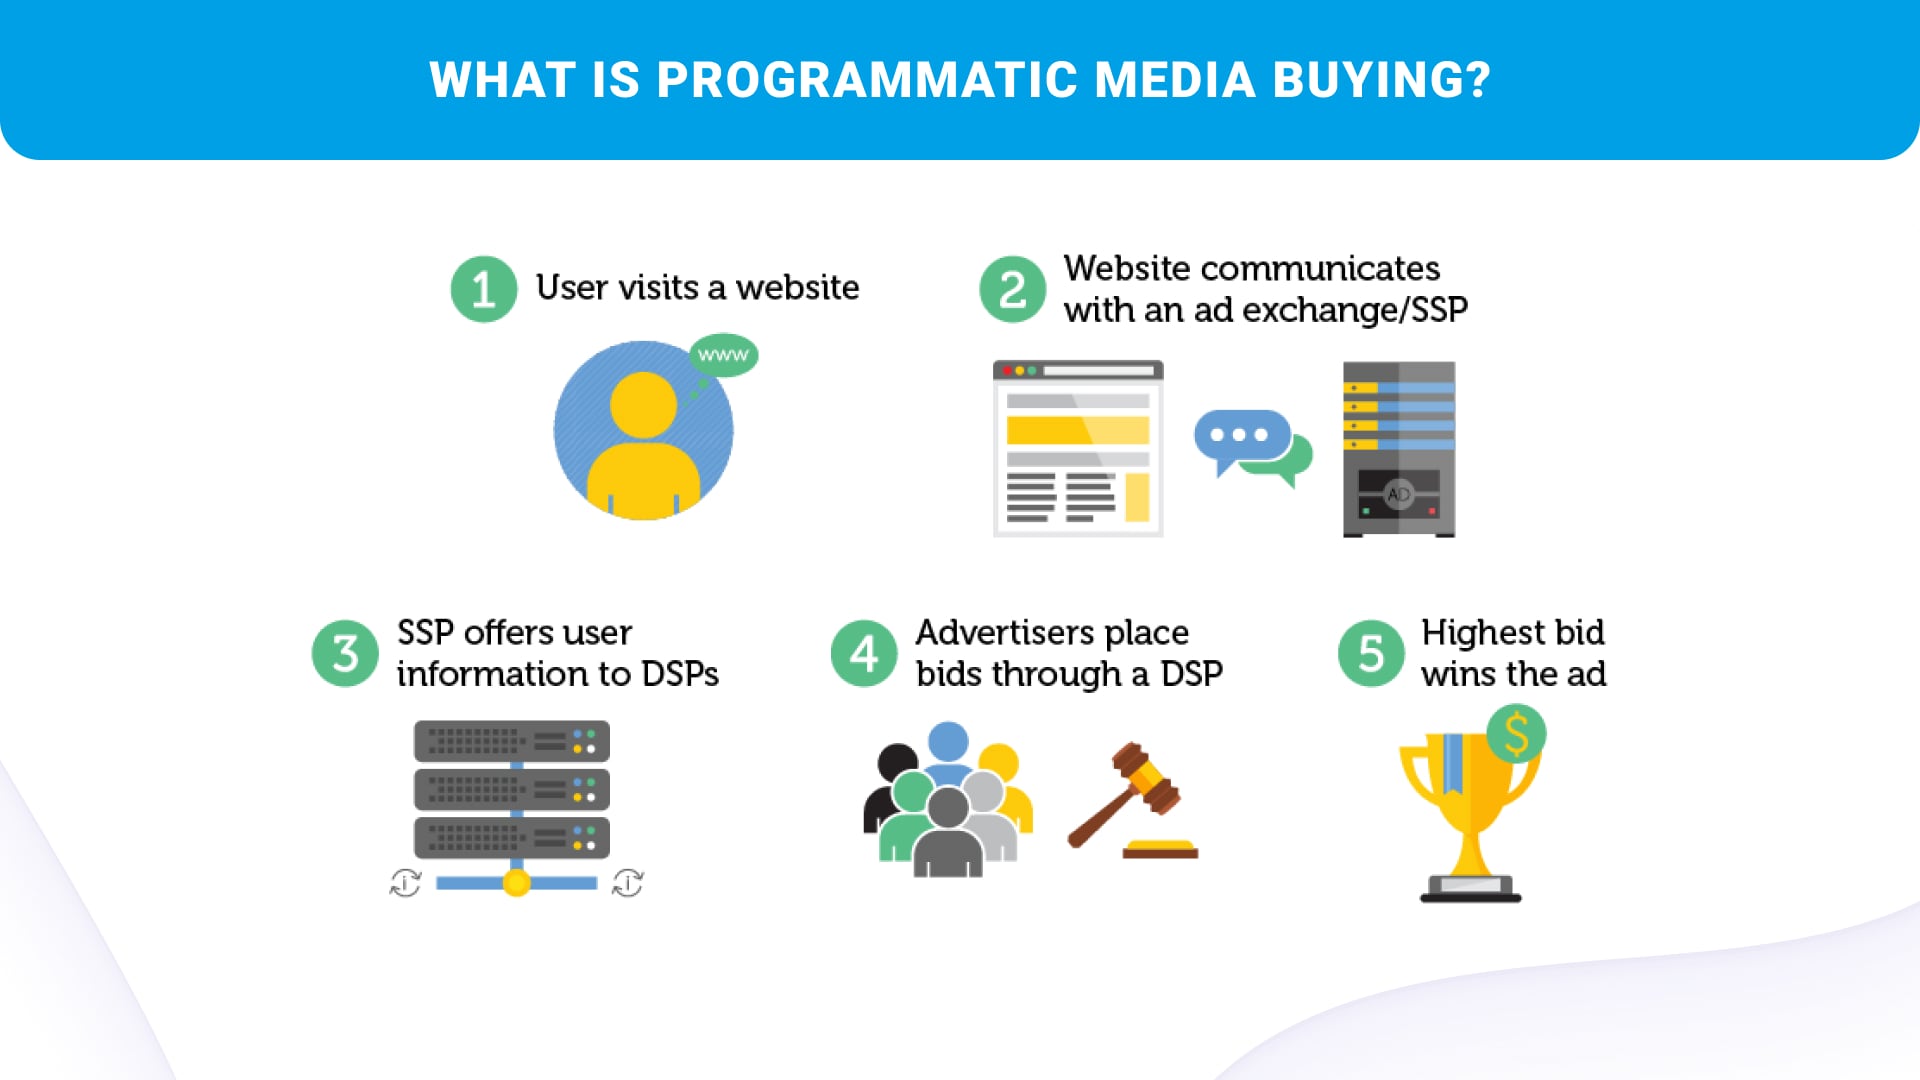
Programmatic buying is fundamentally a method, not a single screen or placement. It can be executed across:
- Display (desktop web, mobile web, in‑app banners)
- Video (in‑stream, out‑stream, CTV/OTT)
- Social placements accessed via APIs
- Digital out‑of‑home (DOOH) and other emerging inventory pools
When people ask “which channel is programmatic buying most used in,” the real answer is: across multiple channels, with digital display being the baseline and most universal channel for both brand and performance objectives.
Why Display Remains Central to Programmatic Campaigns
Several structural factors keep display at the core of programmatic ecosystems:
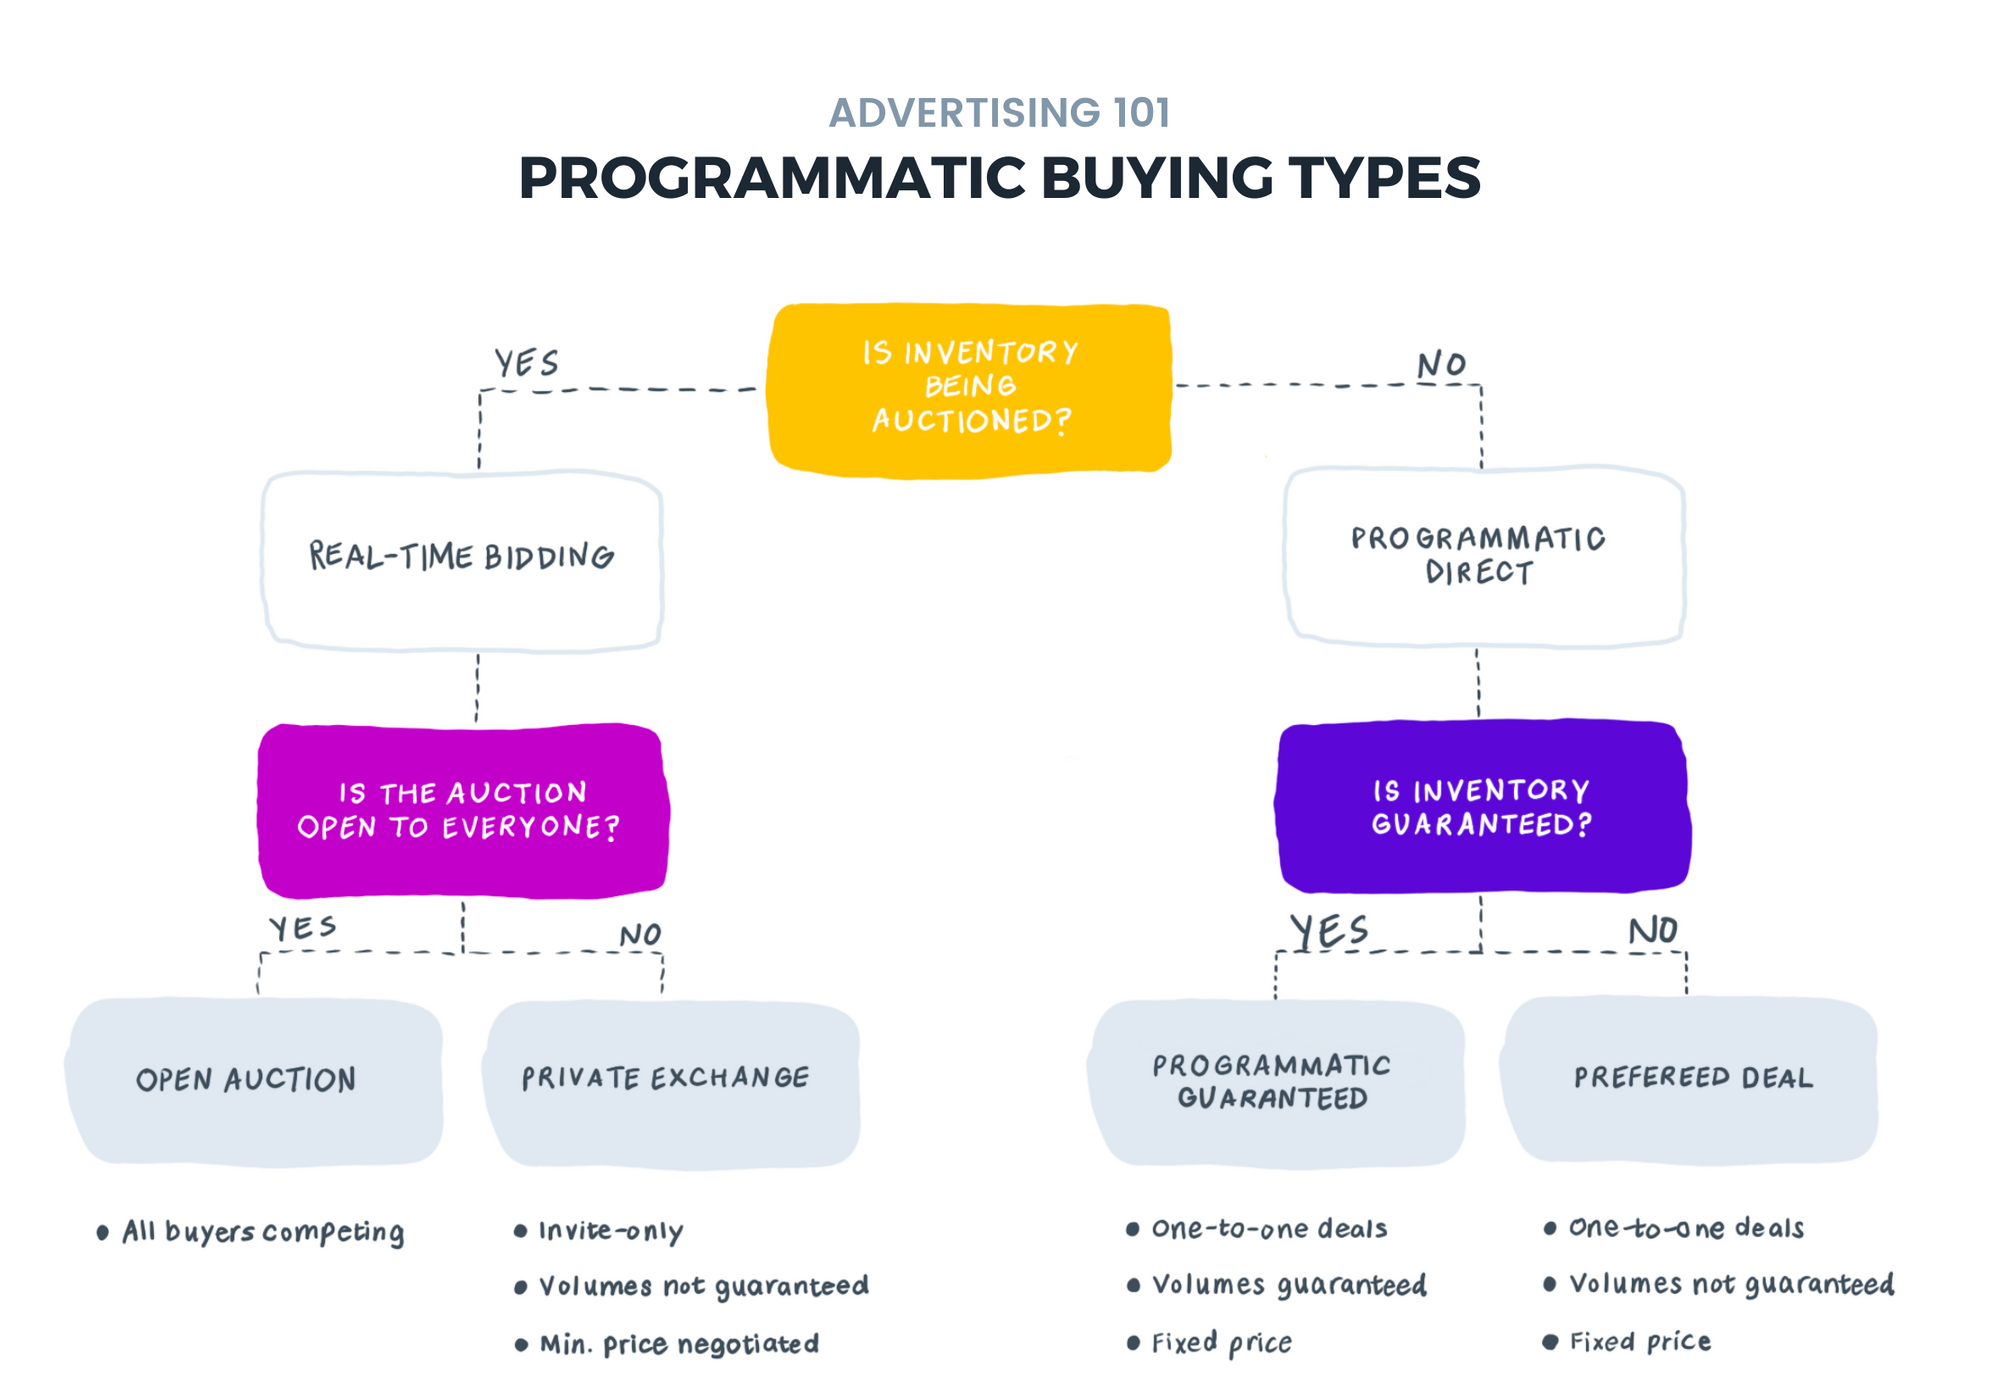
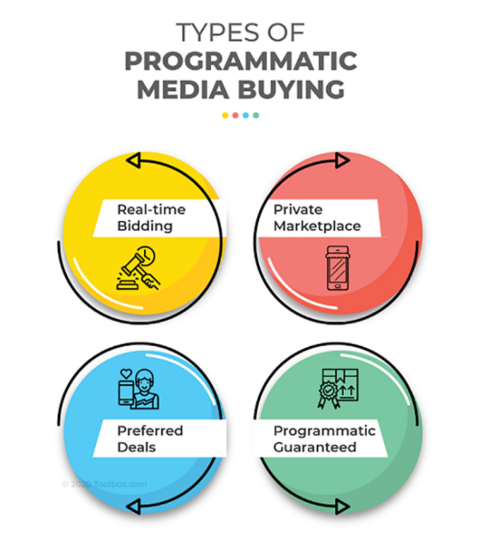
- **Automation and scale**: Billions of display impressions are traded daily via real‑time bidding, header bidding, and programmatic guaranteed deals.
- **Measurement consistency**: Click‑through rates, viewability standards (MRC), and brand‑safety tools have long been built around display.
- **Creative flexibility**: From simple banners to dynamic creatives and interactive ads, display accommodates everything from awareness to direct response.
These strengths mean that even when advertisers scale up video or social, they often maintain a strong display layer for retargeting, compliance, and global reach.
Ownership vs Intermediated Buying
On major social platforms, advertisers often use “walled gardens” with their own automation (e.g., Boosted Posts, Auto‑Applied Ads). These use programmatic concepts but are sometimes perceived as “social ad platforms” rather than open‑programmatic channels.
Nonetheless, many marketers still treat programmatic buying as the interoperable, cross‑publisher strategy that starts with display, then extends into video, DOOH, and other formats through shared identifiers and standards.
The Future: Multi‑Channel but Still Display‑Centric
The trajectory of programmatic buying is increasingly multi‑channel:
- Connected TV and streaming will grow as identity resolution and measurement mature.
- Contextual, privacy‑first targeting will redefine how display is bought and optimized.
- More inventory types (gaming, DOOH, advanced TV, retail media networks) will plug into programmatic pipes.
Yet, display is expected to remain the backbone—where performance marketing and brand campaigns are most consistently optimized at scale.
Putting It All Together
When asked “which channel is programmatic buying most used in,” the most accurate and SEO‑relevant answer is: digital display advertising remains the primary programmatic channel globally, with video, mobile, and social placements representing growing but often secondary segments within overall programmatic ecosystems.
Brands and agencies typically:
- Start or consolidate programmatic strategies around display
- Use display inventory as the baseline for automation, data activation, and performance optimization
- Gradually layer on video, CTV, and other formats as they mature
That combination—display at the core, with video and other channels expanding around it—is both where and how most programmatic buying is used today.