Does a 1065 Have a K1? Full Answer for 2024 Enthusiasts
For shooters and collectors, understanding the relationship between a 1065 rifle and the K1 accessory is essential—knowing whether they coexist ensures compliance and optimal functionality.

www.debtfreedr.com
The 1065 is a top-tier, precision-focused platform favored in competitive shooting and tactical applications. Its modular design allows for aftermarket enhancements, including suppressor attachments—but these rely on dedicated suppressor mounts, not built-in K1 systems. The K1 suppressor mount is engineered for specific silencers, requiring precise alignment and often a separate purchase. Attempting to integrate a K1 without proper mounting hardware risks performance issues and voids warranties.

www.youtube.com
Owners should clarify whether their 1065 is intended for suppressor use, as adding a K1 mount affects legality, safety, and certification. Federal and state regulations vary on suppressor compatibility, and improper installation may violate firearm laws. For collectors and hunters, prioritizing factory specifications ensures authenticity and avoids unintended compliance risks. Always consult certified instructors or manufacturers when modifying or accessingifying your rifle.
www.lpequity.com
While the 1065 platform offers exceptional versatility, it does not include a built-in K1 component. Responsible owners seek approved suppressor mounts designed for their rifle. Staying informed and compliant protects both performance and legal standing—elevate your shooting experience with verified accessories and expert guidance.

www.yieldstreet.com
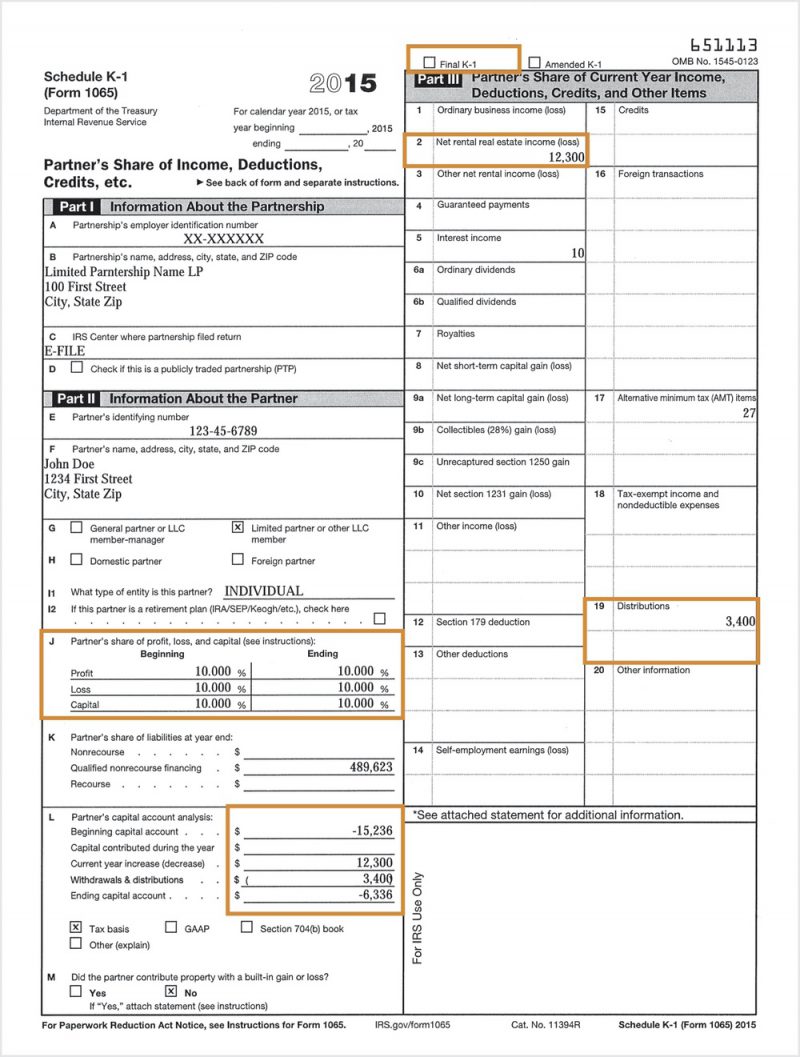
Purpose of Schedule K-1 The partnership uses Schedule K-1 to report your share of the partnership's income, deductions, credits, etc. Keep it for your records. Don't file it with your tax return unless you're specifically required to do so.

www.accountingtoday.com
(See Code O under Box 15, later.) The partnership files a copy of Schedule K-1 (Form 1065) with the IRS. No, a K-1 is not the same as a 1065. A Schedule K-1 reports an individual partner's share of income, deductions, and credits, while Form 1065 is the partnership's overall tax return submitted to the IRS.
www.efile.com
Both are related to partnership taxes but serve different purposes in the tax filing process. But you don't have to go it alone - TaxAct Business can help guide you through the Form 1065 filing process. FAQs about Form 1065 Do I need to file a 1065 if I'm in a partnership? Yes, domestic partnerships and foreign partnerships with U.S.
lili.co
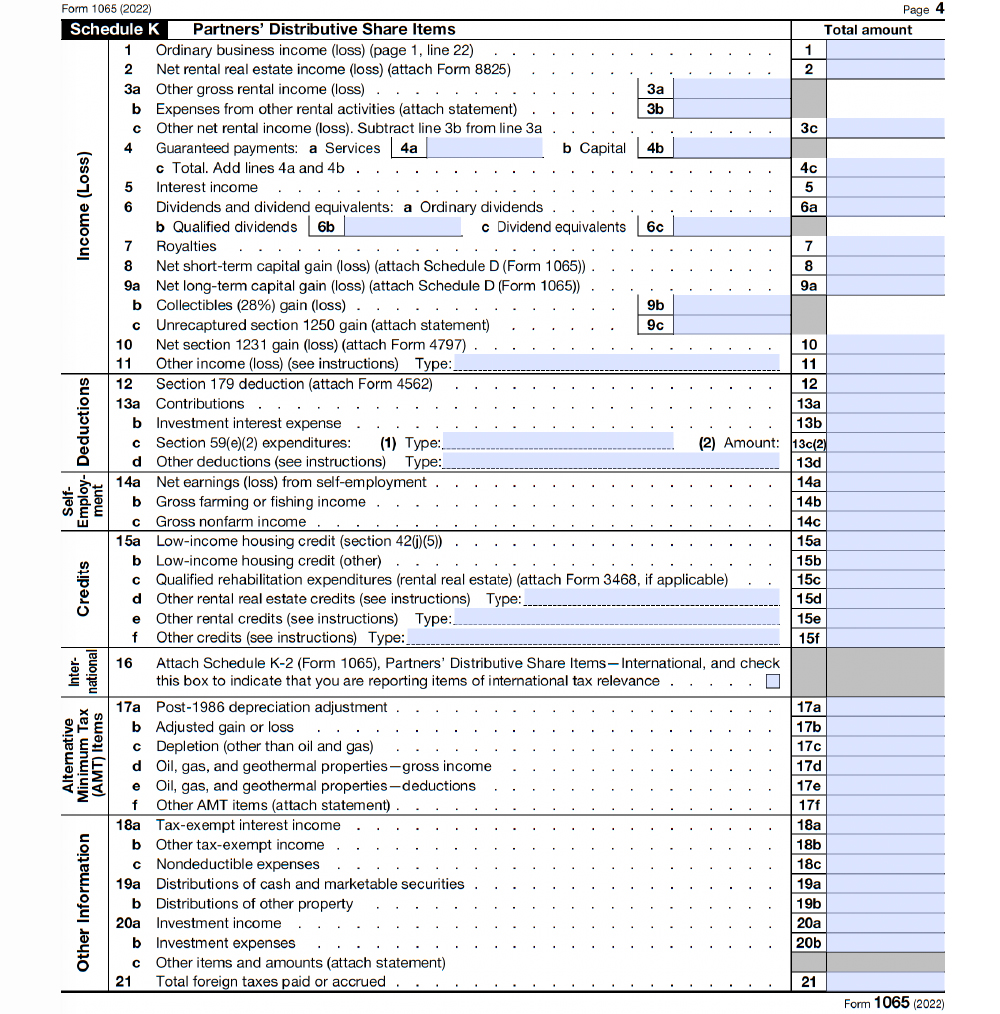
income must file Form 1065 to report their business income and expenses. A practical, box-by-box walkthrough of Schedule K-1 (Form 1065) -how partnership income, deductions, credits, and other items flow through to you, where they go on your individual return, and how to avoid common mistakes. Learn how to properly report partnership income with the Schedule K.
fitsmallbusiness.com
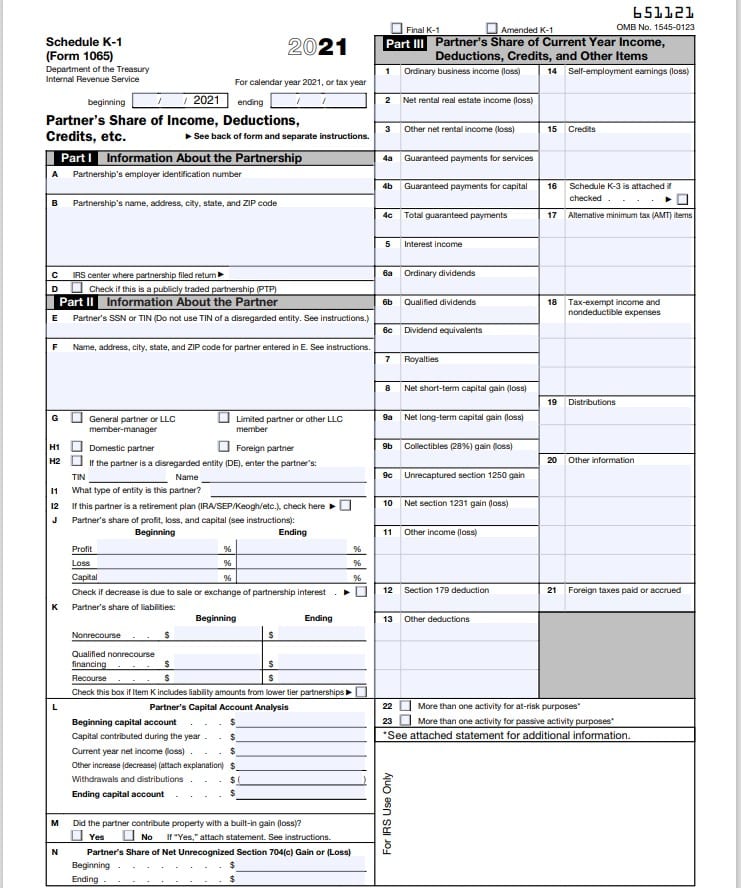
Looking to better understand your tax forms, specifically a Schedule K1 form (also known as Form 1065)? Income, taxes, deductions, and more are covered. There are actually three versions of Form K1, each tied to a specific type of entity: Form 1065 Schedule K-1 for partnerships, Form 1120-S Schedule K-1 for S corporations, and Form 1041 Schedule K-1 for trusts and estates. The deadline to receive a Form K1 is typically March 15 for partnerships and S corps, and April 15 for trusts and estates.
If the income, deductions, credits, or other information provided to any partner on Schedule K-1 or K-3, as applicable, is incorrect, file an amended Schedule K. Partnerships: Schedule K-1 Form 1065 Partnerships use Schedule K-1 Form 1065 to report income, deductions, and credits. This form tells each partner their share of the partnership's profits or losses for the tax year.
It breaks down a partner's distributive share of partnership income. Every partner receives a copy of Schedule K. Yes, all U.S.
partnerships are required to issue a Schedule K-1 (Form 1065) to each partner for tax purposes. Every partner needs this K-1 form to report their share of the partnership's income, losses, and credits on their personal tax return. According to a 2025 National Small Business Association survey, 83% of small businesses are structured as pass-through entities, meaning the majority.