Distributable Net Income Tax Rules For Bypass Trusts
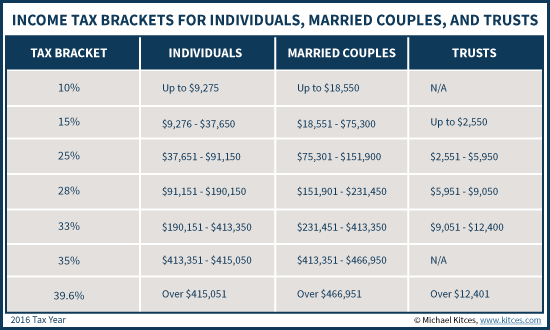
The Distributable Net Income (DNI) rules help to minimize the taxation of a non-grantor bypass trust , by passing through income to the trust beneficiaries.

Understand how Distributable Net Income helps trusts avoid double taxation. Learn the rules for tax -efficient distributions. Read our guide for expert insights.
26 CFR 1.643(a)
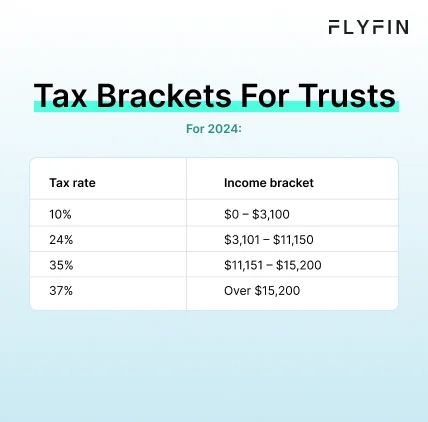
§ 1.643 (a)-0 Distributable net income ; deduction for distributions; in general. The term distributable net income has no application except in the taxation of estates and trusts and their beneficiaries. It limits the deductions allowable to estates and trusts for amounts paid, credited, or required to be distributed to beneficiaries and is used to determine how much of an amount paid ...
Discover how Distributable Net Income (DNI) allocates trust income to beneficiaries, prevents double taxation, and minimizes trust taxes with examples and calculations.
PDF Gains, Distributable Net Income and the 65
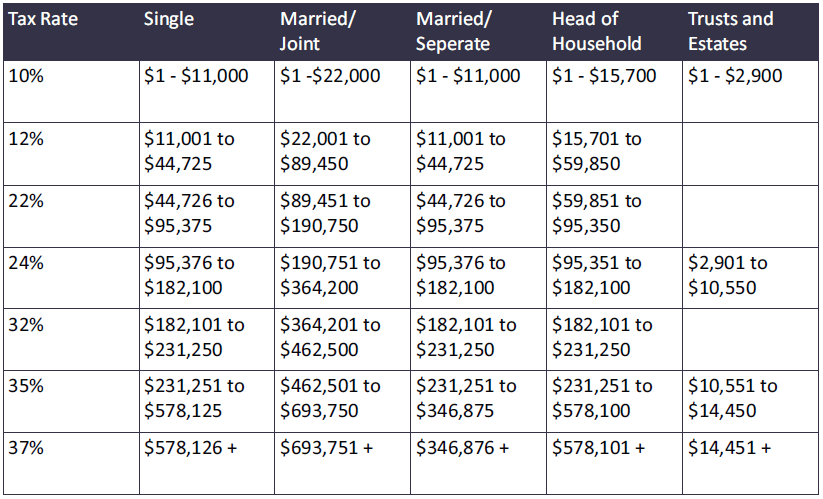
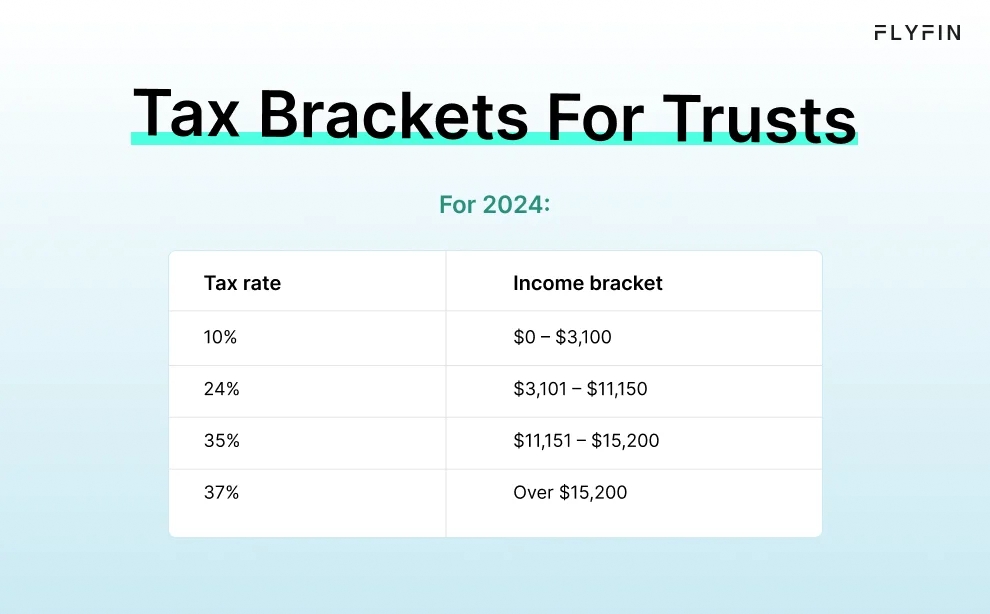
Gains, Distributable Net Income and the 65-Day Rule Quick-Take: Lots of thought must go into whether to leave income in a trust and subject it to confiscatory federal income tax rates, or to distribute that income to trust beneficiaries, exposing the taxable income to a beneficiary's lower marginal federal income tax rate.
If the amount of income required to be distributed currently exceeds the distributable net income , the deduction allowable to the trust is limited to the amount of the distributable net income .
Trust distributions
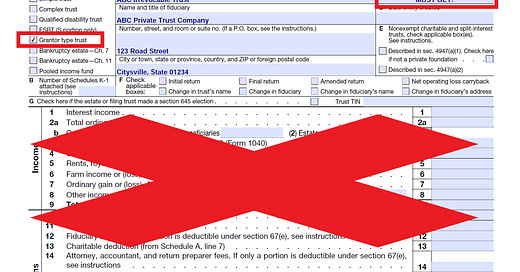
Distributions from a trust to a beneficiary can take many forms and can have widely varying consequences. The timing of the distribution, the type of asset distributed, the requirements under the governing trust instrument, and the intersection of trust accounting income (TAI) and distributable net ...
Items of deduction of a trust that enter into the computation of distributable net income are to be allocated among the items of income in accordance with the following principles: (a) All deductible items directly attributable to one class of income (except dividends excluded under section 116) are allocated thereto. For example, repairs to, taxes on, and other expenses directly attributable ...
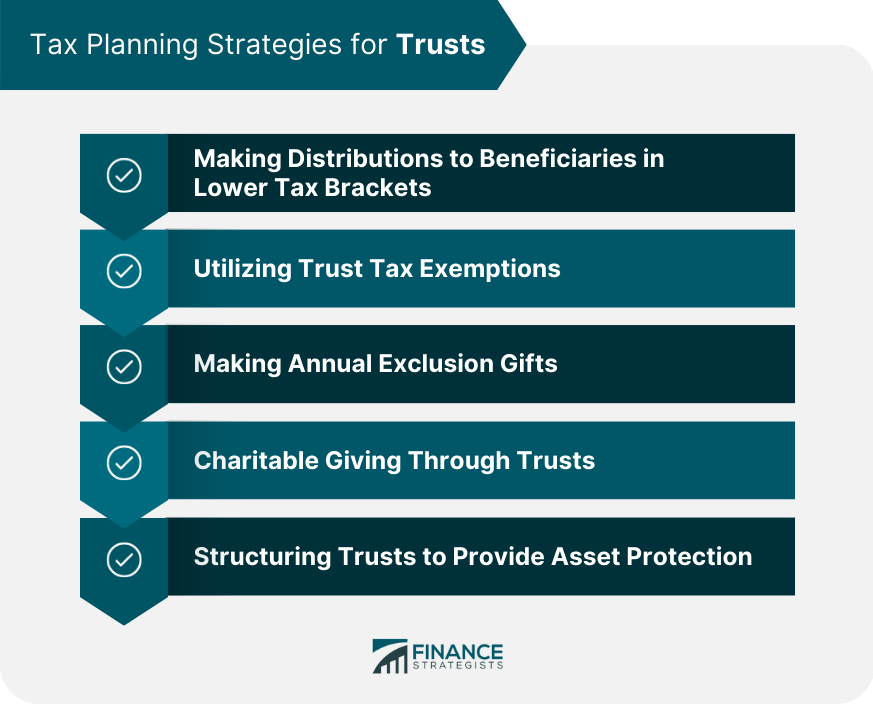
Trust Taxation Basics
In Part 1 of the Trust Taxation series, we introduced how trust distributions can shift the income tax burden from the trust to the beneficiary. The shift in tax from the trust to the beneficiary is not unlimited but instead calculated by a key concept of trust taxation known as Distributable Net Income (DNI). Understanding DNI is essential because it determines both how much income a trust ...
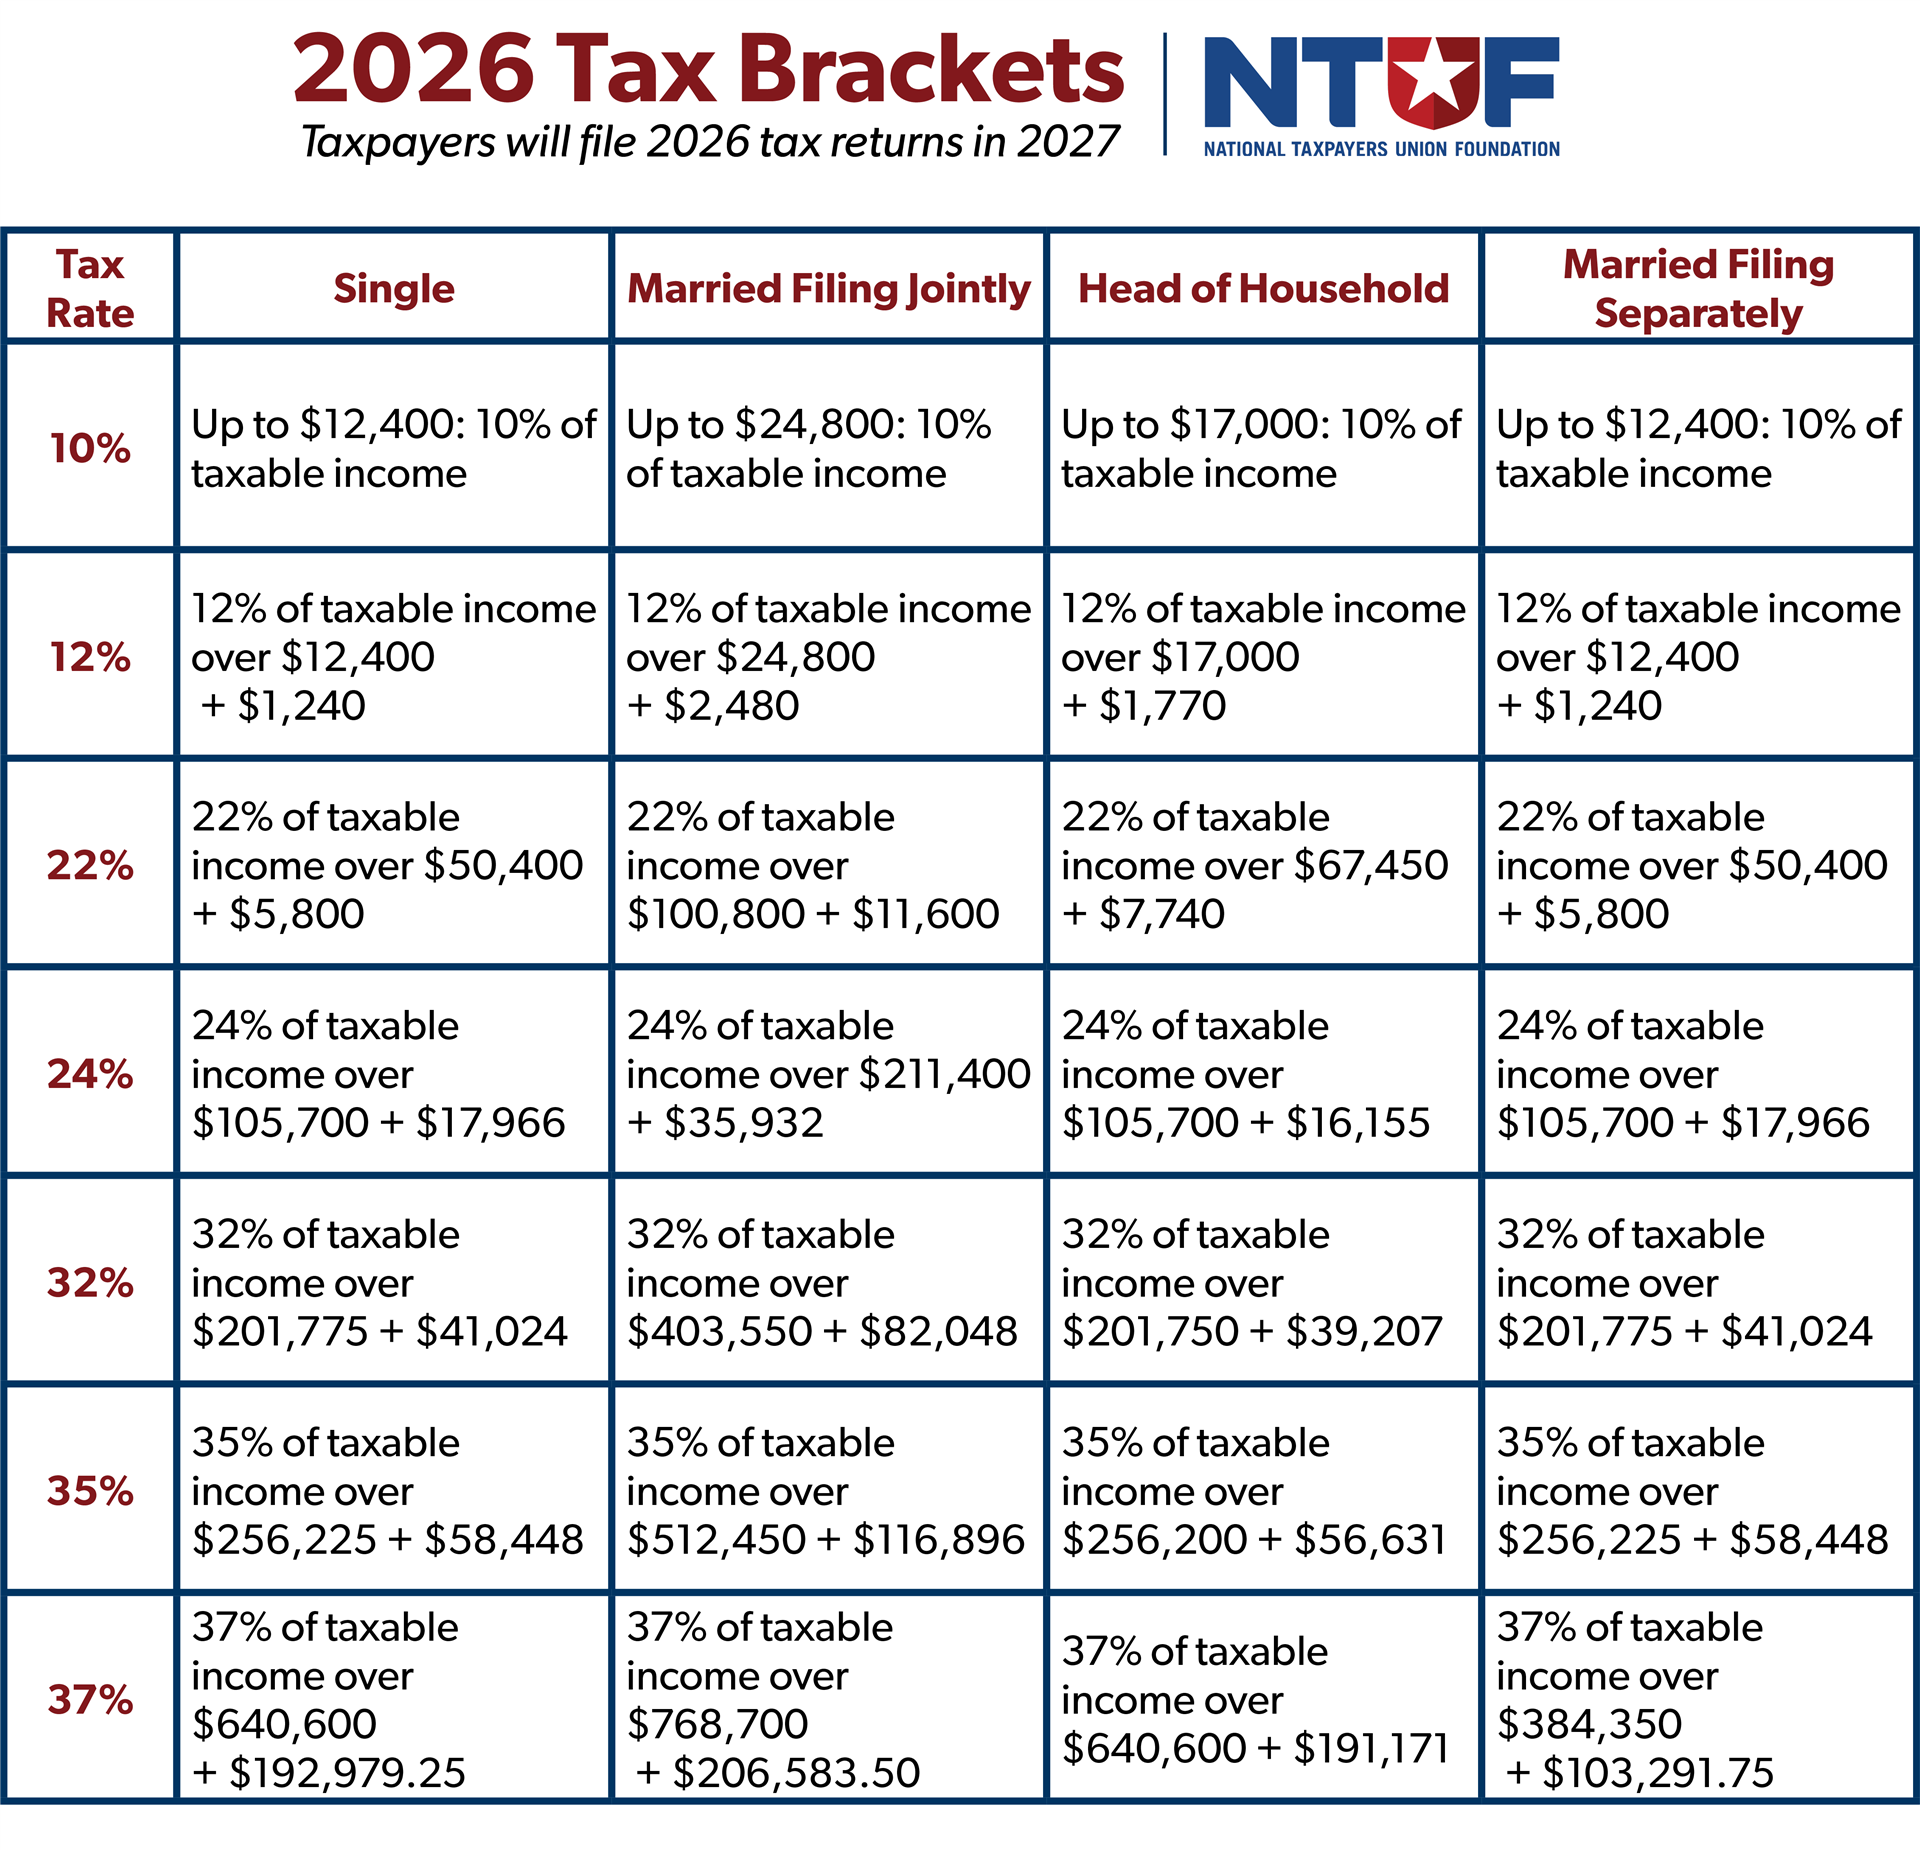

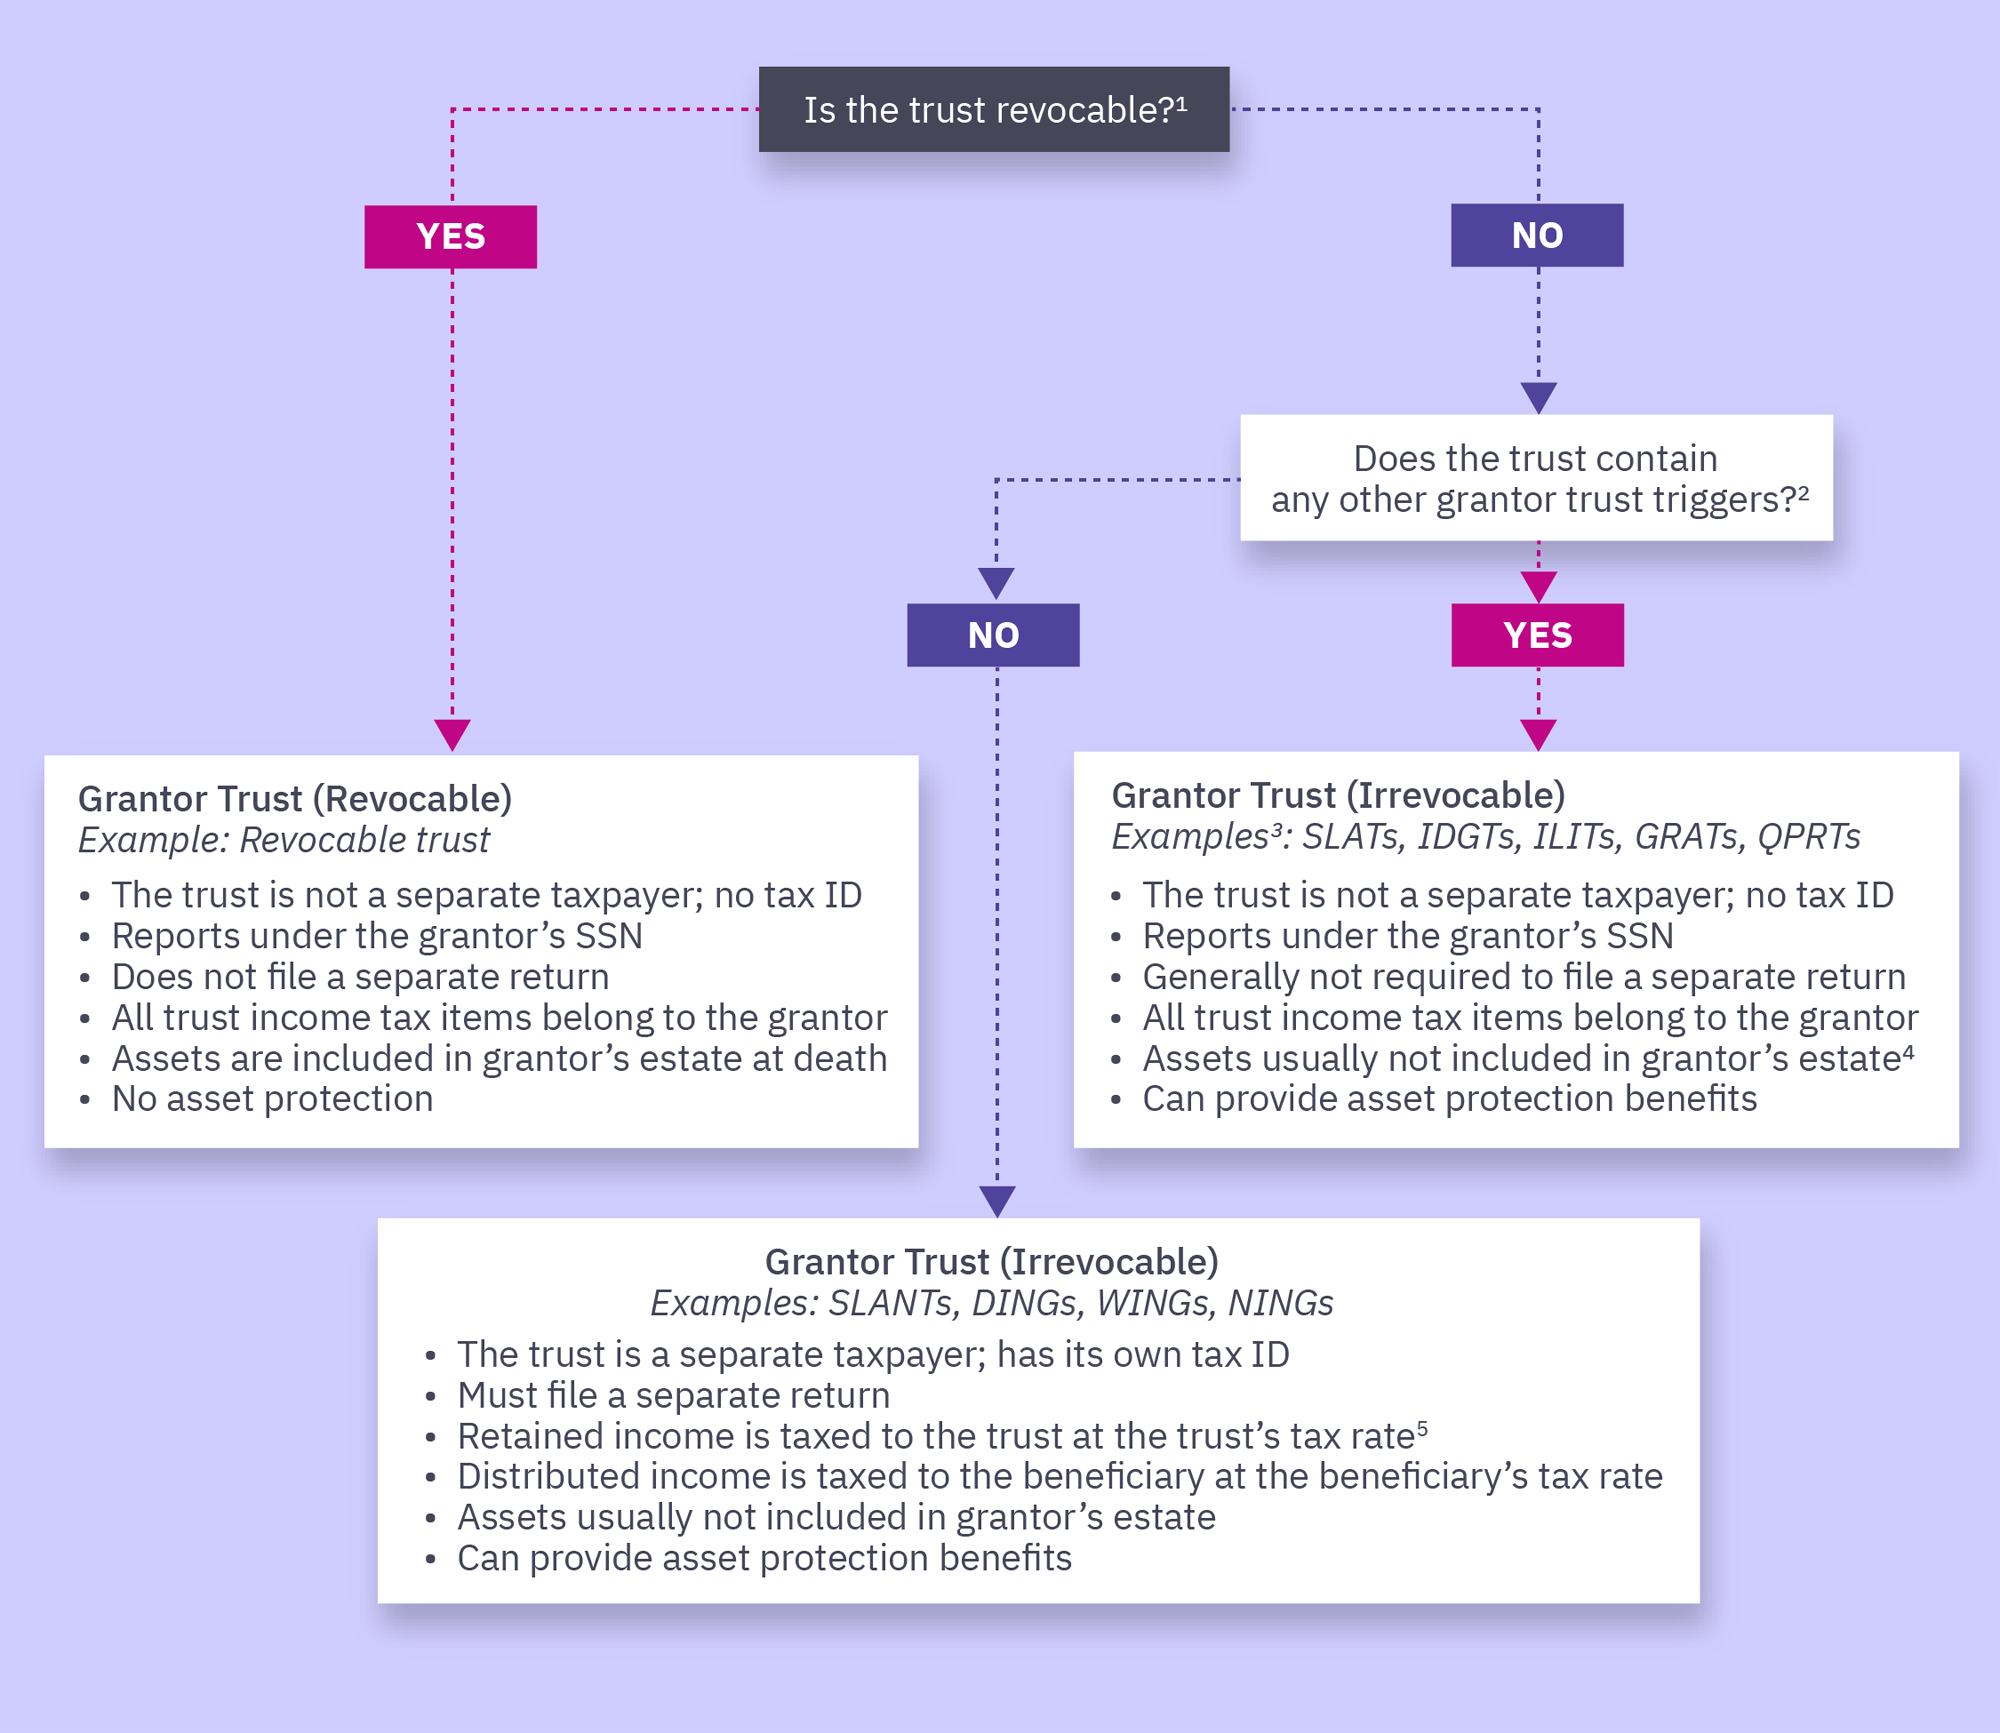

This is the distributable net income or DNI, and this is what generates the deduction to the trust and the income to the beneficiary and ensures that both the trust and the beneficiary do not pay tax on the same income .