Income Tax Reporting Methods for Grantor Trusts
Optional Method 3 is only used when there are two or more grantors or deemed owners who, in the aggregate, are treated as owning all trust income and principal under the grantor trust rules. The procedure is the same as for Optional Method 2, but with the statements to grantors being required even if a grantor is a trustee.
Treasury Regulation 1.671-4 (b) provides three optional reporting methods for grantor trusts that the trustee can utilize for income tax reporting . A one-owner trust can choose between two optional methods .
PDF Grantor Trust Income Tax Reporting Requirements
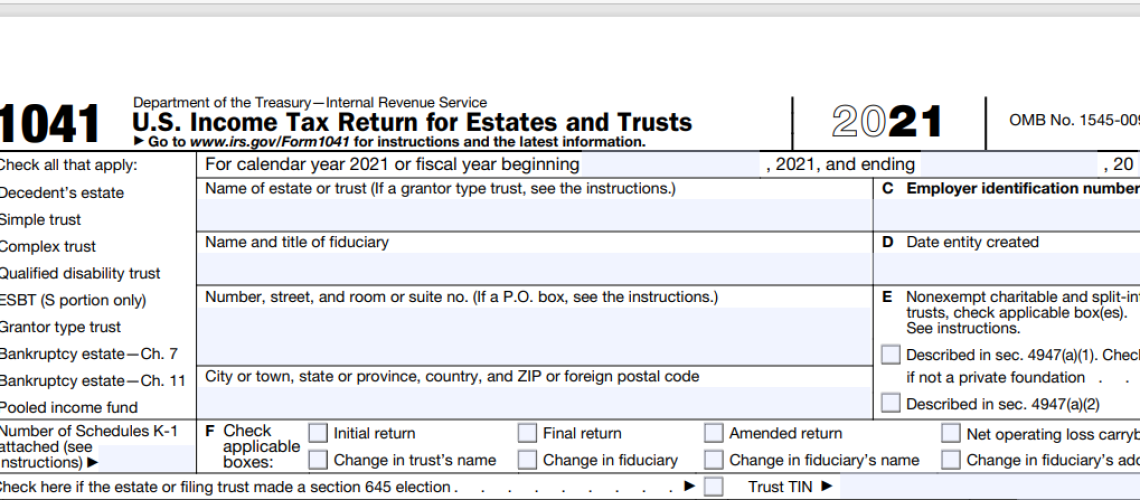
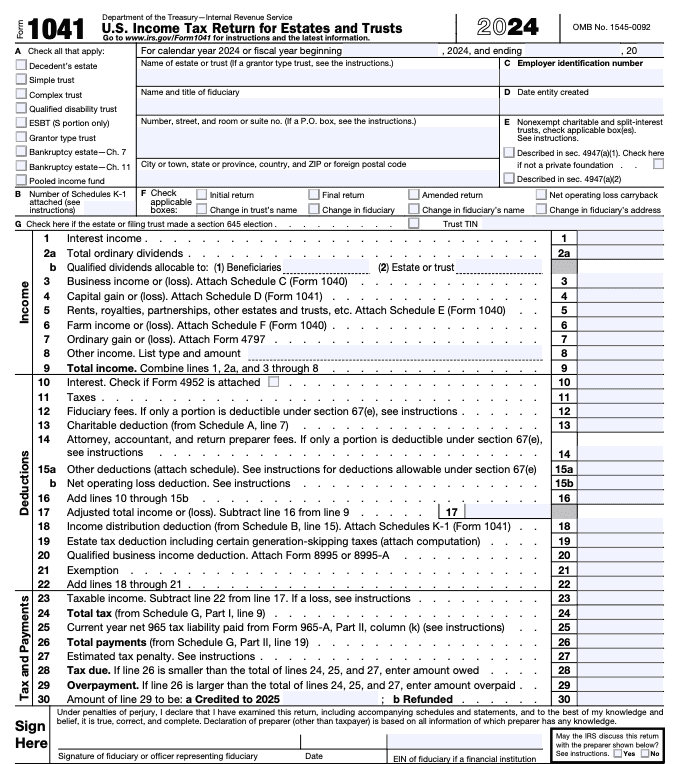
Notwithstanding the general rule, grantor trusts are eligible for simplified reporting procedures. If the trust is a wholly owned grantor trust , the trust's tax return, if required at all, need include only minimal information. If a wholly owned grantor trust files a Form 1041, it is using the "Traditional Method " of reporting . In the Traditional Method of reporting , only the entity ...
An expert estate planning attorney reviews the options available for reporting the income tax from grantor trusts .
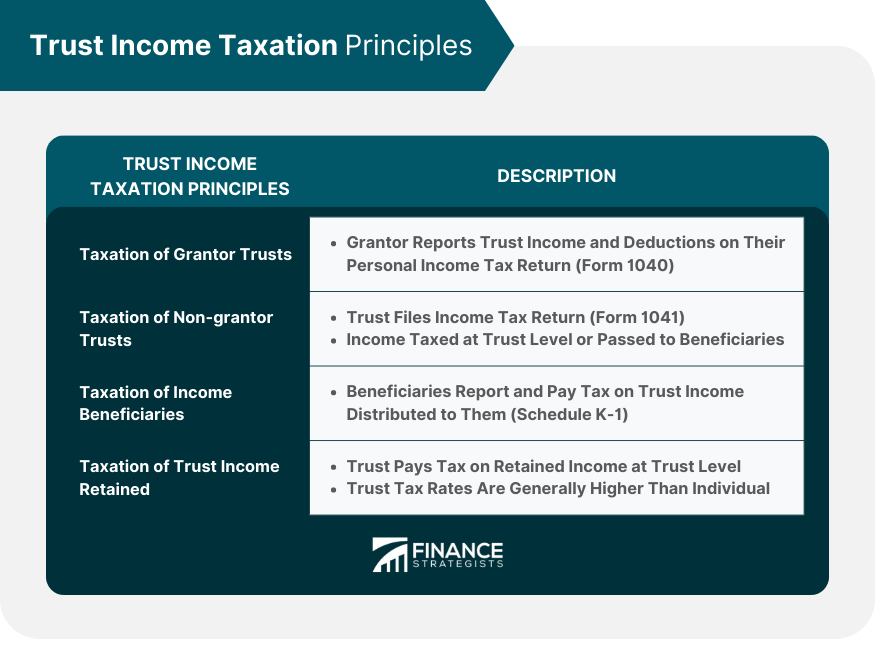
Income Taxation of Grantor Trusts
Thus, no IRS Form 1041 tax return is required. The grantor must give the trustee a signed form W-9 to use this reporting method . Option 2 - TIN obtained and the trust only has one (1) grantor . The trustee must supply the IRS and the grantor with a 1099 reporting the income . No IRS Form 1041 is required for the trust .
General Reporting—Form 1041 Grantor trusts are subject to the same reporting requirements as nongrantor trusts . IRC §§ 6012(a)(4)-(5) require trusts with taxable income of any amount, gross income of $600 or more, or one or more nonresident beneficiaries, to file an income tax return within three and one-half months of the end of its taxable year. For most trusts (that is, those that ...

How Is a Grantor Trust Taxed Differently (wExamples) FAQs
The three ways to report grantor-trust income , including the methods that skip Form 1041 entirely. Worked examples for revocable trusts , IDGTs, and the moment the grantor dies.
This method is most commonly used with revocable trusts which are also grantor trusts for income tax purposes. The second alternative method requires the trust be a reporter of income to the grantor .

26 CFR 1.671
The trustee must file with the Internal Revenue Service the appropriate Forms 1099, reporting the income or gross proceeds paid to the trust during the taxable year, and showing the trust as the payor and the grantor or other person treated as the owner of the trust as the payee.



(a) Portion of trust treated as owned by the grantor or another person. Except as otherwise provided in paragraph (b) of this section and § 1.671-5, items of income , deduction, and credit attributable to any portion of a trust that, under the provisions of subpart E (section 671 and following), part I, subchapter J, chapter 1 of the Internal Revenue Code, is treated as owned by the grantor or ...