Thelimitedliabilitycompanyhas grown to become one of the most prevalent business forms in the United States. Even the use of asinglememberLLCaffords greater protection for the assets of themember, as compared to operating as an unincorporated entity.[19].
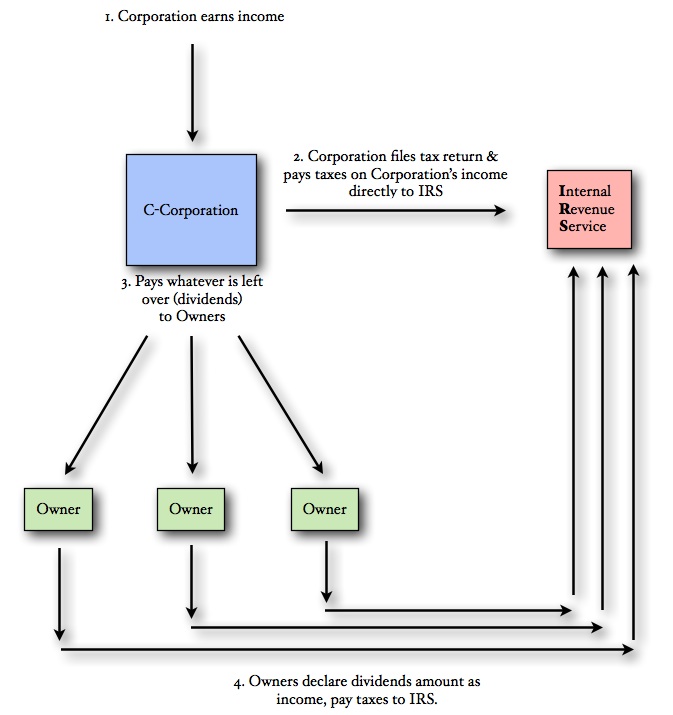
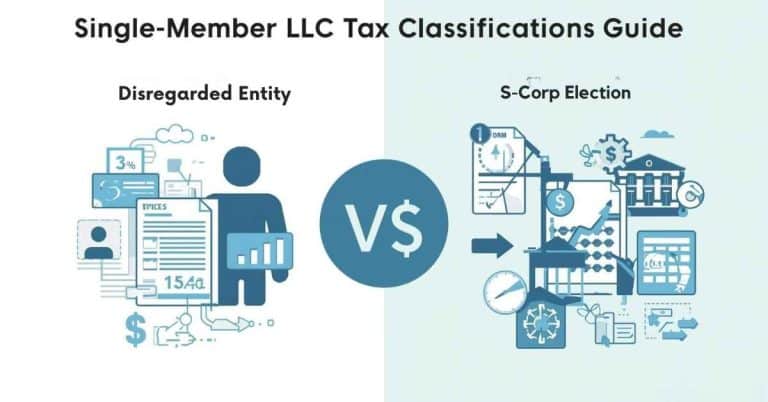
At the same time, you getliabilityprotection similar to a corporation, which shields your personal assets from business debts and lawsuits.Asingle-memberLLCis treated as a sole proprietorship for incometaxpurposes. TheLLCdoes not paytaxesas a separate entity.
ALimitedLiabilityCompany(LLC) is a type of business that is registered with the state and gives personal,limitedliabilityprotection to its owners.IncomeTaxesforSingle-MemberLLCs. AnLLCthat is made up of only asingleowner is considered a disregarded entity by the IRS.

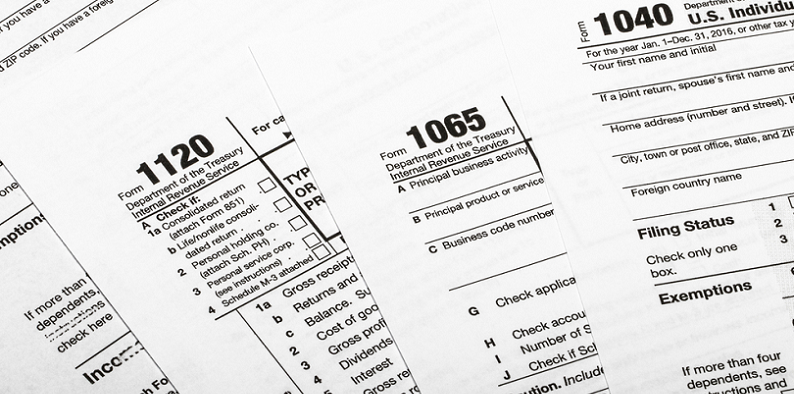
Single-memberLLCowners are treated like sole proprietors fortaxpurposes by default. But anLLCcan instead elect to betaxedas a corporation. With corporate taxation, anLLCowner can be paid as a W-2 employee of thecompany.
Single-memberLLCshave only onemember(owner). Under the so-called "check-the-box regulations" issued by the IRS years ago, you generally ignore the existence of asingle-memberLLCfor federaltaxpurposes.LiabilityProtection forSingle-MemberLLCs.
This particular example perfectly highlights why Single Member Llc Tax Liability is so captivating.
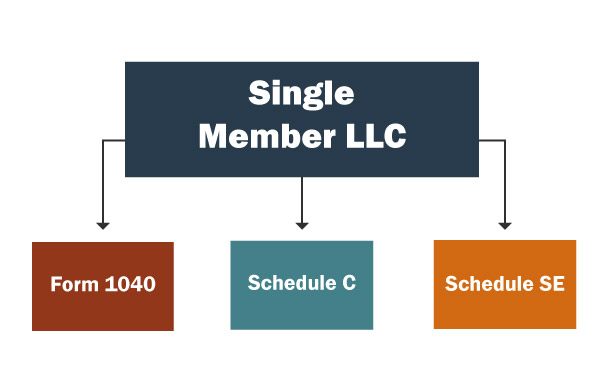
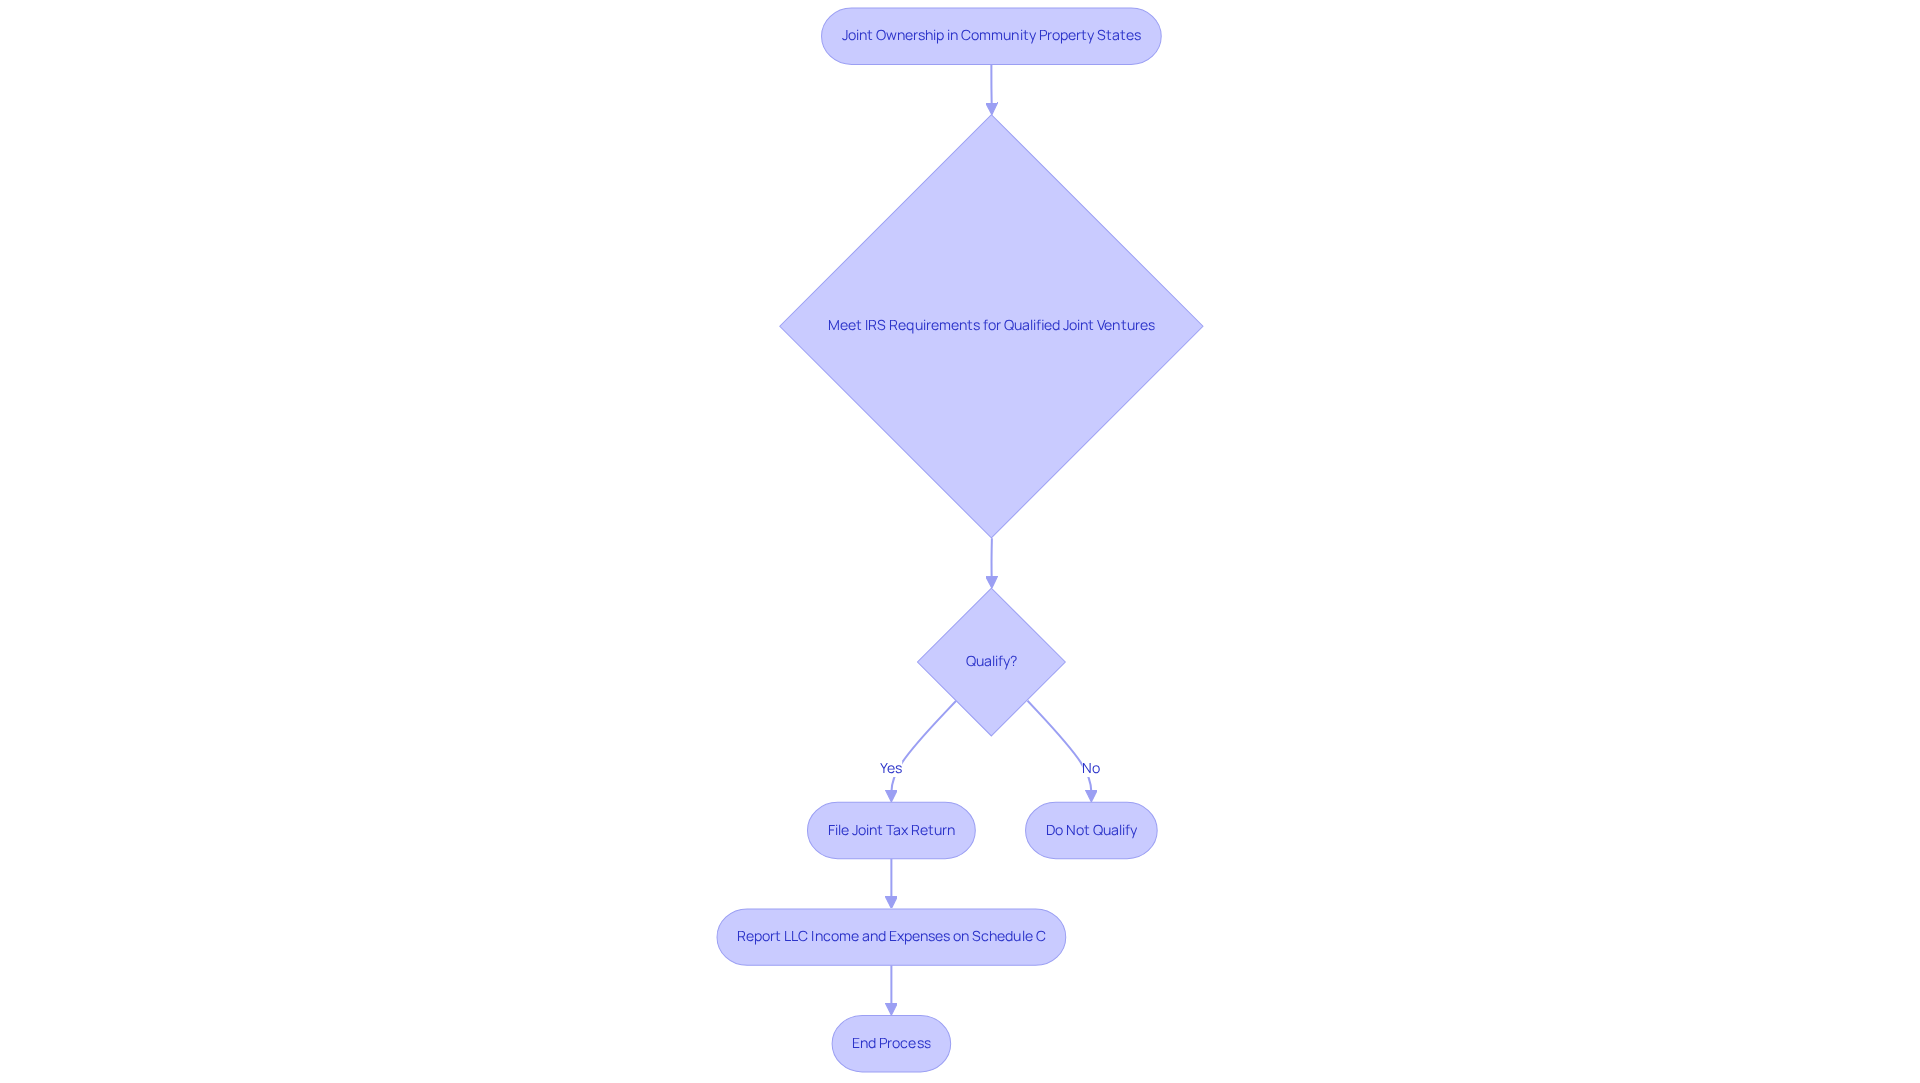
If yourLLCis asingle-memberentity, it's treated like a sole proprietorship. This means you’ll file your business income and expenses on Schedule C, which is part of your personaltaxreturn. For multi-memberLLCs, the IRS treats it as a partnership by default.
Legally, asingle-memberLLCisn't always required to have a separate account, but it's strongly advisable fortaxandliabilityreasons. Commingling personal and business funds makes it harder to identify deductible expenses...