Understanding Pre-1976 Mobile Home Financing
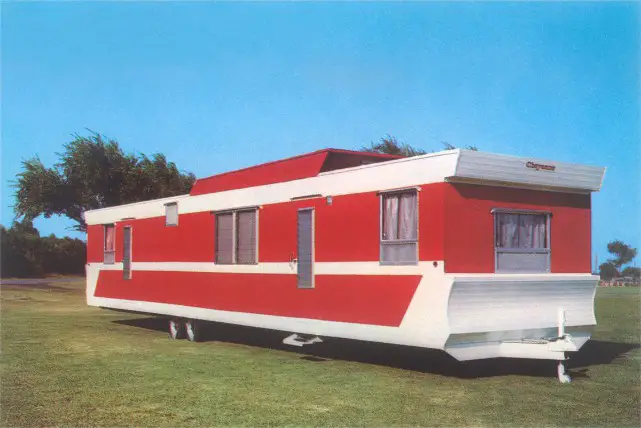
Before the Housing and Community Development Act of 1974, mobile homes were often considered personal property, not real estate. This classification significantly impacted financing options for these homes, especially those built before 1976. Let's delve into the intricacies of pre-1976 mobile home financing, its challenges, and available solutions.
Challenges in Financing Pre-1976 Mobile Homes
Financing a pre-1976 mobile home can be complex due to several reasons:
- Personal Property Status: Before 1976, mobile homes were typically considered personal property, making them ineligible for traditional mortgages.
- Age and Condition: Older mobile homes may require repairs or renovations, which can deter lenders due to the potential risks and costs.
- Appraisal Difficulties: Appraising a mobile home, especially an older one, can be challenging. This uncertainty may make lenders hesitant to provide financing.
Financing Options for Pre-1976 Mobile Homes
Despite the challenges, several financing options are available for pre-1976 mobile homes:

Chattel Loans
Chattel loans are designed specifically for personal property, including mobile homes. These loans typically have shorter terms, higher interest rates, and require the mobile home as collateral. However, they can be a viable option for those who cannot qualify for other types of financing.
FHA Title I Loans
While primarily for manufactured homes built after 1976, some lenders may offer FHA Title I loans for pre-1976 mobile homes. These loans require the mobile home to be permanently affixed to a foundation and the land to be owned by the borrower.
Private Lenders and Credit Unions
Some private lenders and credit unions may offer financing for pre-1976 mobile homes, especially if the home is in good condition and the borrower has a strong credit history. These lenders may have more flexible qualification requirements than traditional banks.
Tips for Securing Financing for a Pre-1976 Mobile Home
To increase your chances of securing financing for a pre-1976 mobile home, consider the following tips:
- Improve your credit score by paying bills on time, reducing debt, and addressing any negative items on your credit report.
- Save for a larger down payment to reduce the loan amount and potentially qualify for better terms.
- Consider hiring a professional appraiser to provide an accurate assessment of the mobile home's value.
- Shop around with different lenders, including private lenders and credit unions, to find the best financing option.
Conclusion
Financing a pre-1976 mobile home can be challenging due to its personal property status and potential age-related issues. However, with the right approach and understanding of available financing options, it's possible to secure the necessary funds to purchase or refinance an older mobile home. By working with a knowledgeable lender and taking steps to improve your financial profile, you can increase your chances of success in the pre-1976 mobile home financing process.