Understanding Promissory Notes Secured by Real Estate
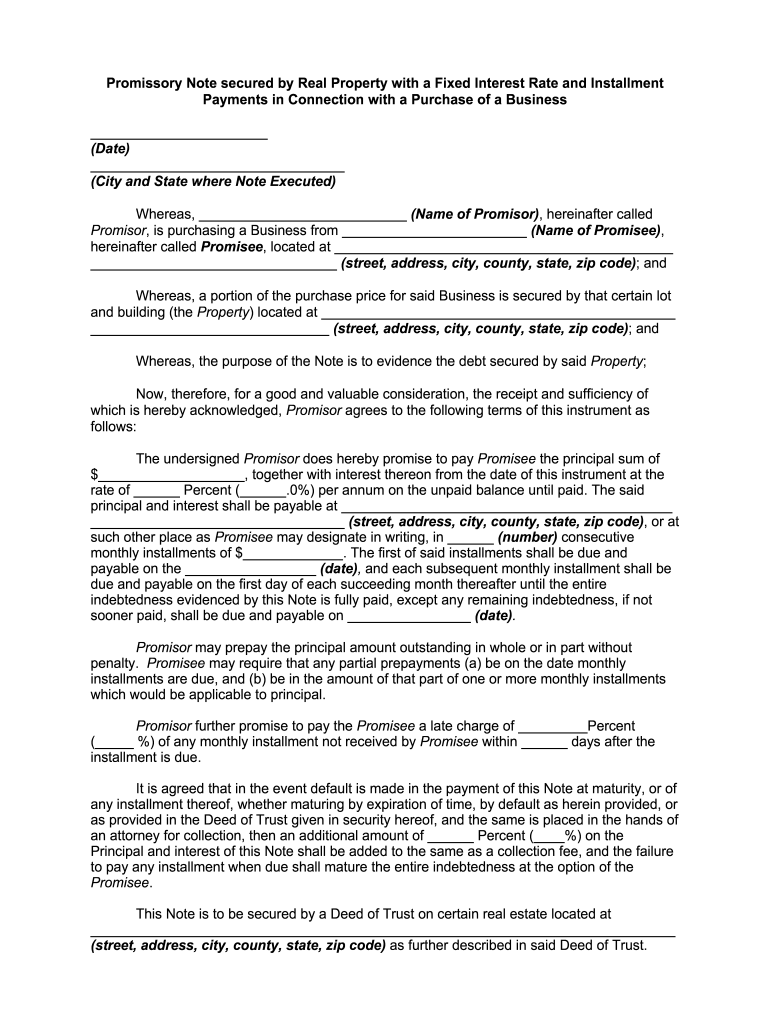
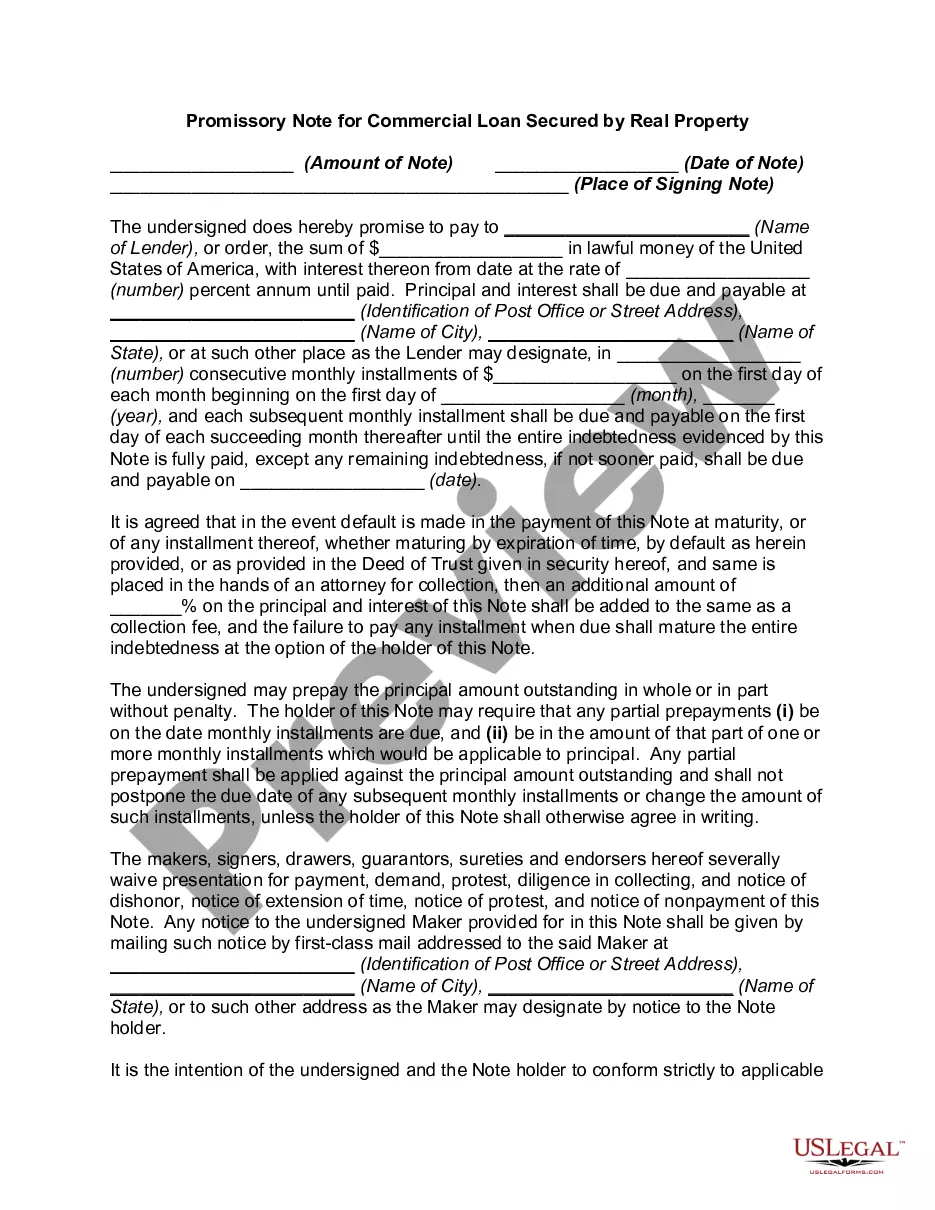
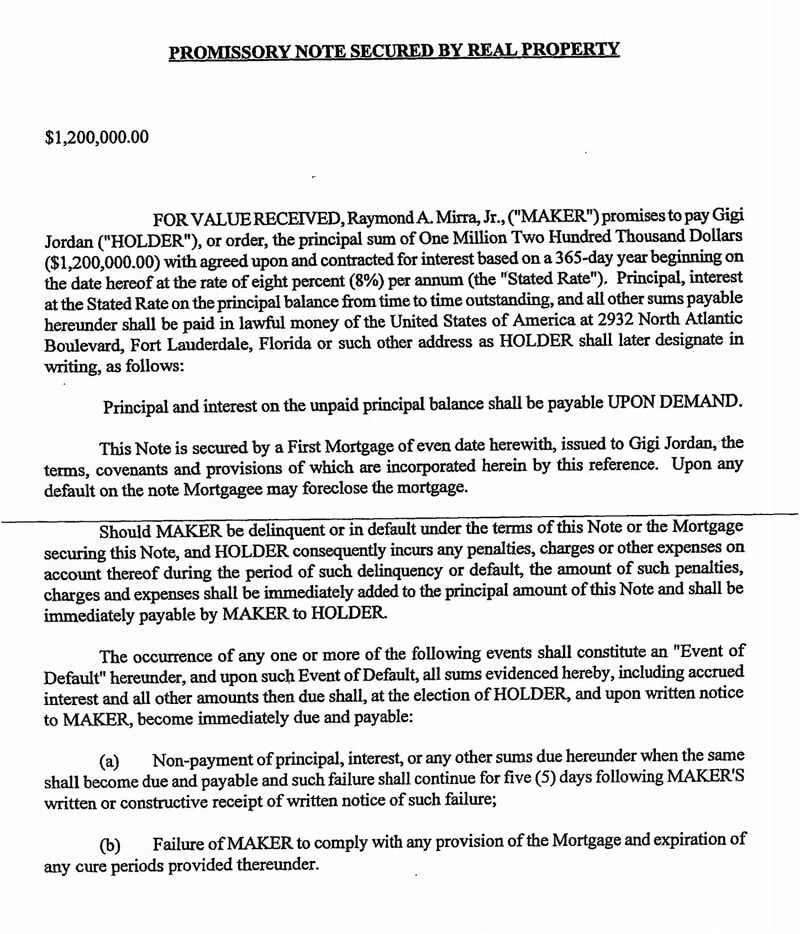
A promissory note secured by real estate is a legal document that outlines a promise to pay a certain sum of money, with the borrower's real estate property serving as collateral. This type of promissory note is often used in mortgage loans, home equity loans, and other real estate financing transactions. Here, we'll delve into the intricacies of promissory notes secured by real estate, their benefits, risks, and the legal aspects that govern them.
How Promissory Notes Secured by Real Estate Work
In a promissory note secured by real estate, the borrower (mortgagor) promises to repay a loan (principal) to the lender (mortgagee) in accordance with specified terms. The real estate property serves as security or collateral for the loan. If the borrower defaults on the loan, the lender can foreclose on the property to recoup their losses.
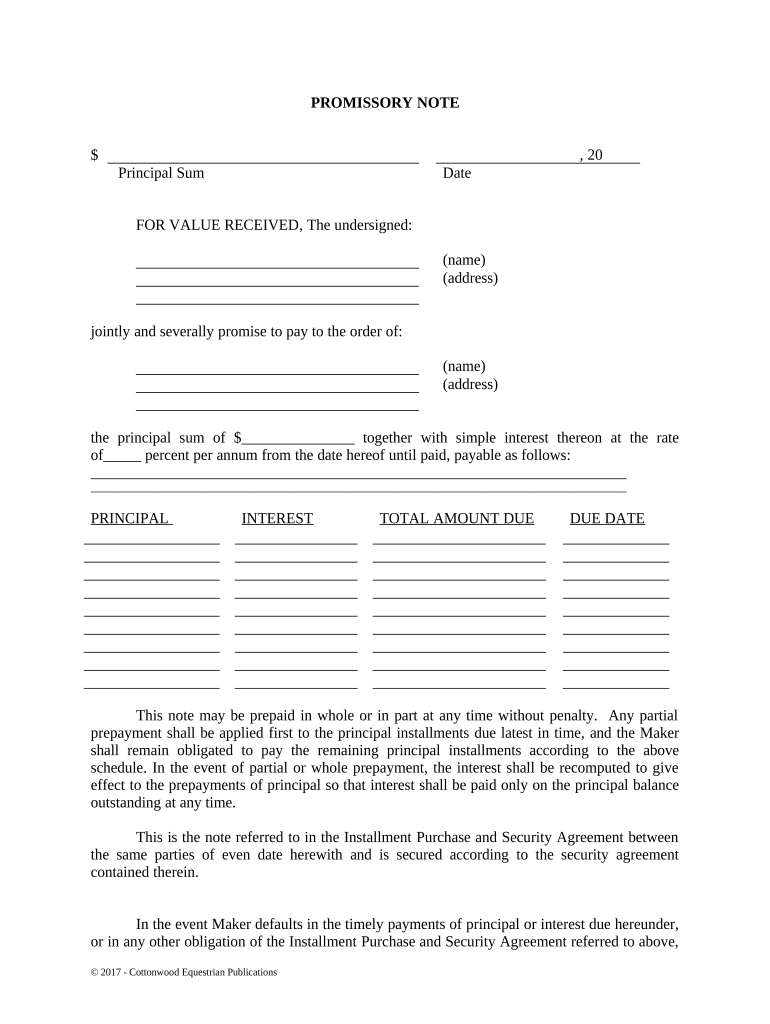
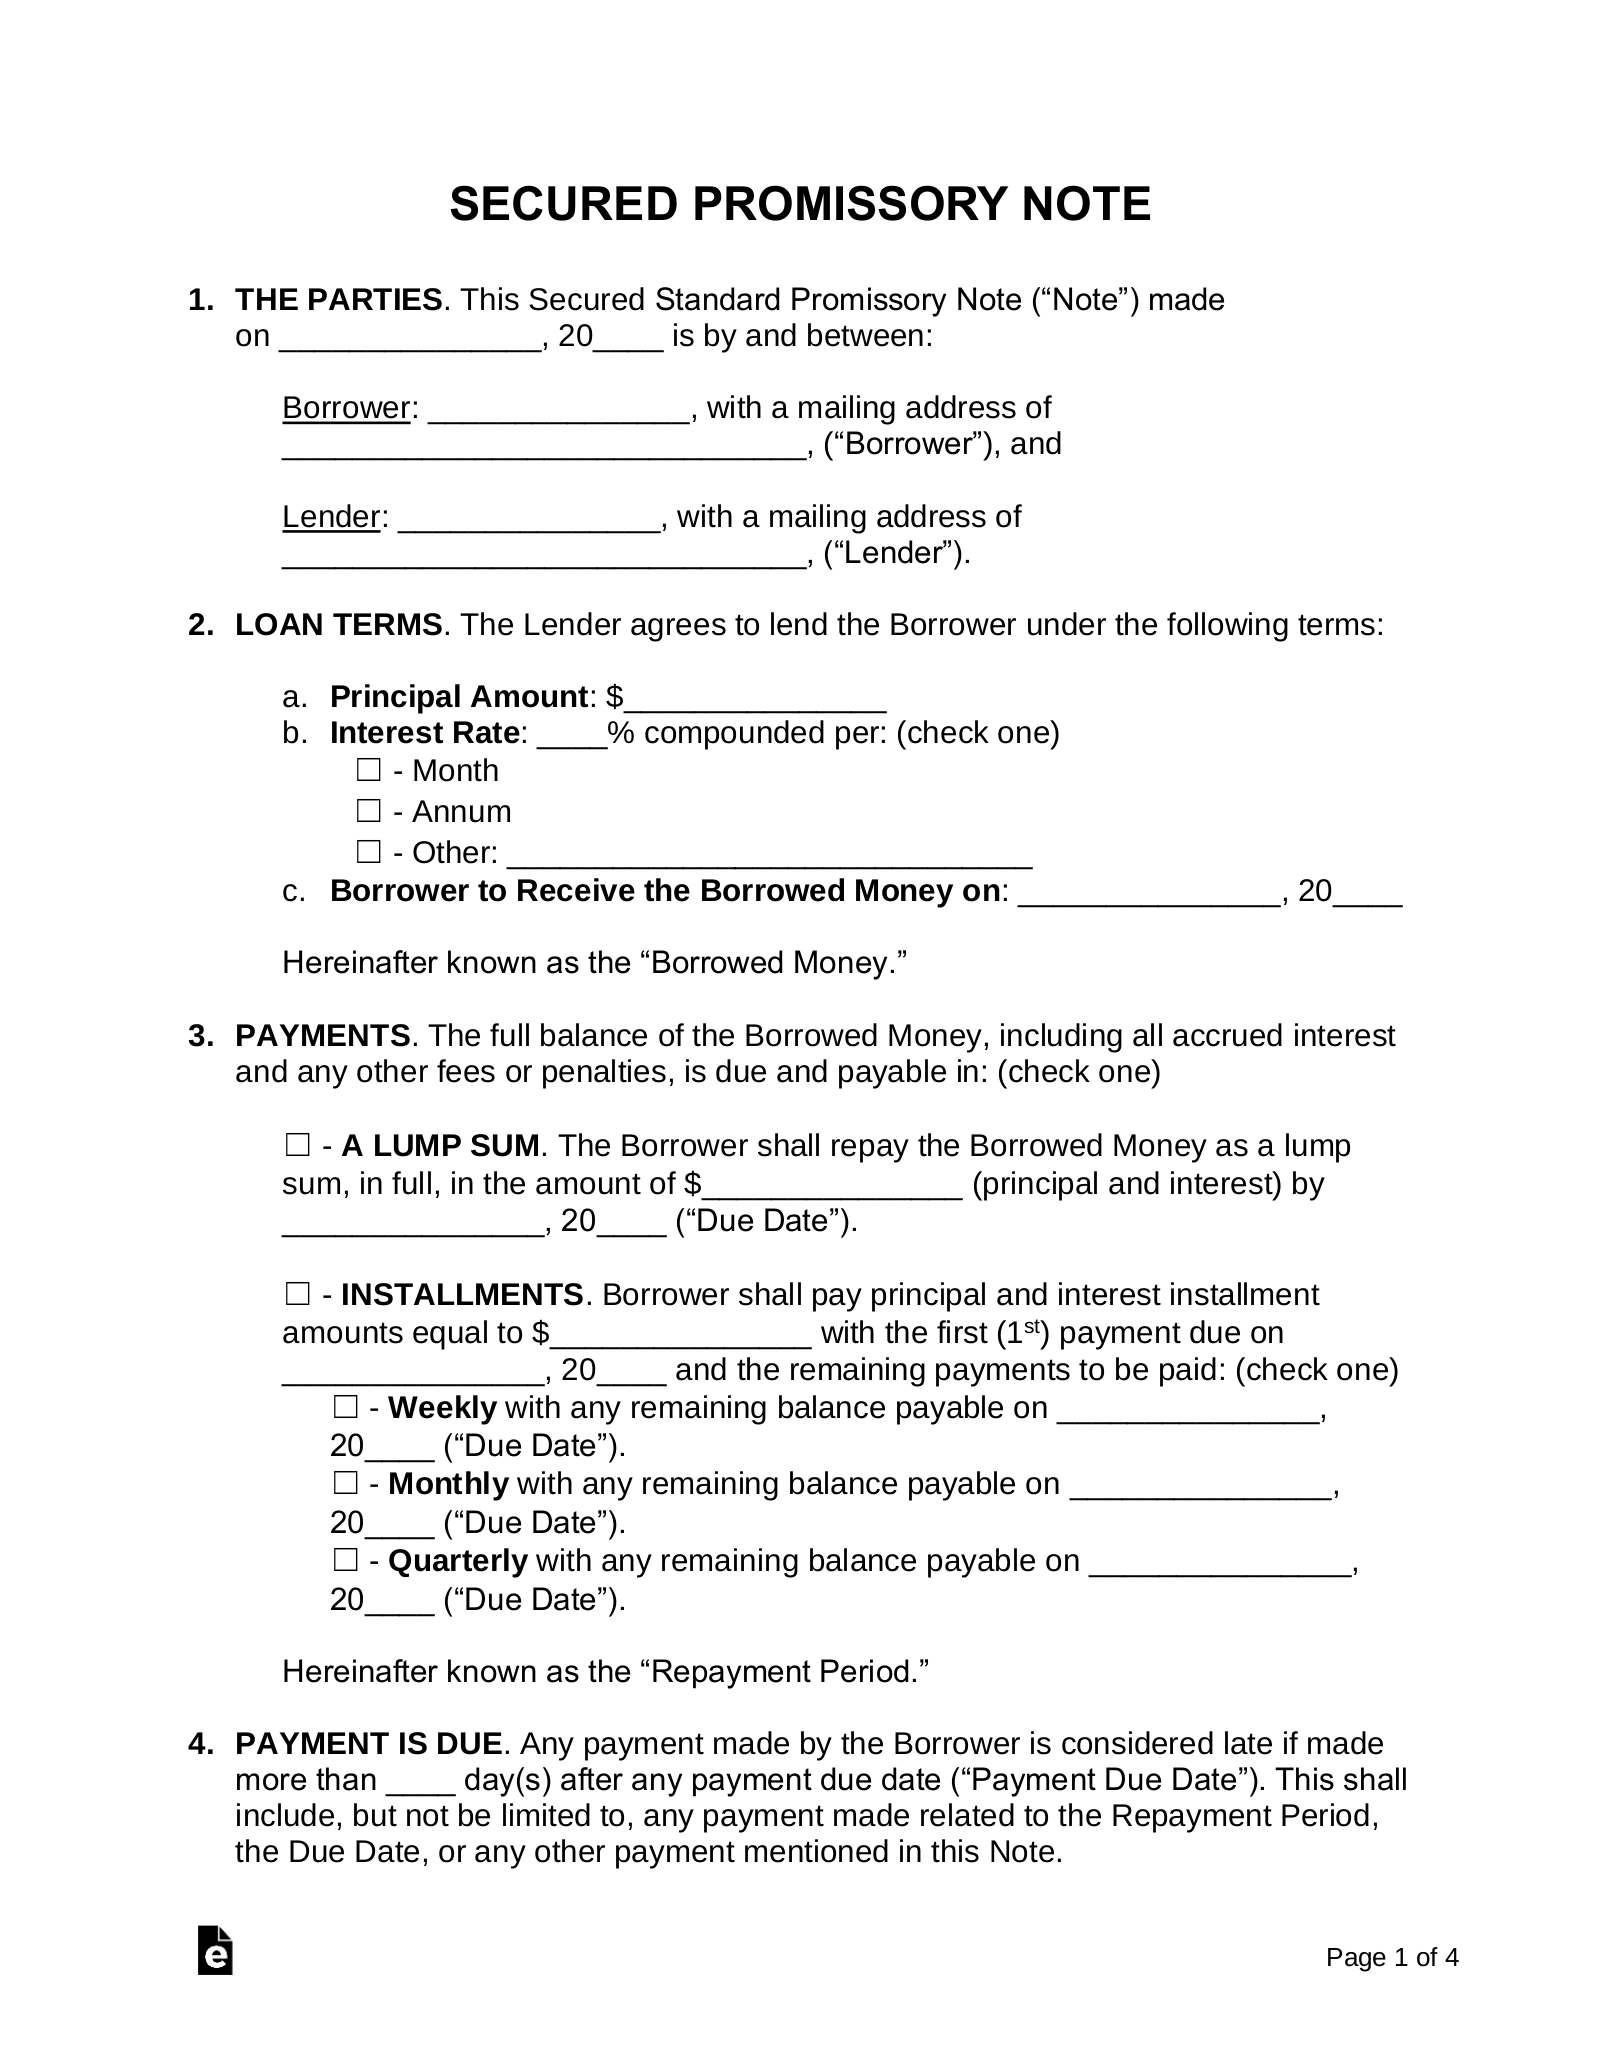
The promissory note typically includes details such as:
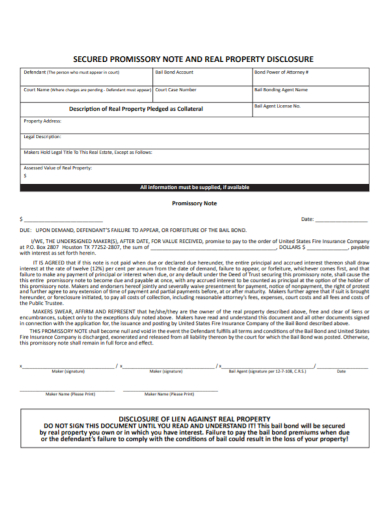
- The names of the borrower and lender
- The principal loan amount
- The interest rate and how it's calculated
- The repayment terms (installment amounts, frequency, and duration)
- Consequences of default, including the lender's right to foreclose
Benefits of Promissory Notes Secured by Real Estate
For lenders, promissory notes secured by real estate offer a high degree of security, as they can foreclose on the property if the borrower defaults. For borrowers, these notes can provide access to larger loan amounts and more favorable interest rates, as the real estate collateral reduces the lender's risk.
Risks and Considerations
While promissory notes secured by real estate can be beneficial, they also come with risks:
- Foreclosure: If you default on the loan, the lender can foreclose on your property.
- Decline in Property Value: If the property's value drops, the lender may not recoup the full loan amount even after foreclosure.
- Additional Costs: Foreclosure can incur additional costs, such as legal fees and maintenance of the property.
Legal Aspects and Protections
Promissory notes secured by real estate are governed by state and federal laws. The Truth in Lending Act (TILA) requires lenders to disclose important loan terms, and the Real Estate Settlement Procedures Act (RESPA) provides consumers with protections during the loan process. Additionally, state laws govern foreclosure procedures and provide borrowers with certain protections.

It's crucial to understand your rights and obligations when entering into a promissory note secured by real estate. Consulting with a real estate attorney can help ensure you're making an informed decision and that your interests are protected.
| State | Foreclosure Process |
|---|---|
| Judicial Foreclosure States | Foreclosure process involves court supervision |
| Non-Judicial Foreclosure States | Foreclosure process is handled outside of court |
Knowing your state's foreclosure process can help you understand what to expect if you find yourself in default.
In conclusion, promissory notes secured by real estate are powerful financial tools that can help borrowers access significant funds while providing lenders with a high degree of security. However, it's essential to understand the risks, legal aspects, and your rights and obligations before entering into such an agreement.