At the heart of every seamless electronic funds transfer lies a pair of essential identifiers: the check routing number and the account number. While often mentioned together, these two distinct elements serve unique purposes in the financial ecosystem, working in tandem to ensure that money moves accurately and securely from one point to another. Understanding the difference between them is not just a matter of financial literacy; it is a fundamental step in protecting your personal finances and ensuring your transactions are processed without delay or error.
Think of the routing number as the address for your financial institution. It is a nine-digit code that identifies the specific bank or credit union responsible for holding your account. This standardized code, established by the American Bankers Association, allows the complex network of banks, credit unions, and clearinghouses to determine exactly where a check originates or where an electronic payment should be routed. Without this directional code, the financial system would lack the necessary infrastructure to automate the billions of transactions that occur daily, forcing a return to inefficient manual processing.
Breaking Down the Routing Number
While it may look like a random string of digits, a routing number is a carefully structured identifier with specific information embedded within its nine digits. The first four digits represent the Federal Reserve Routing Symbol, which indicates the geographic region where the bank was located. The next four digits specify the financial institution itself, acting like a unique identifier within that region. Finally, the ninth digit is a checksum, a mathematical calculation used to validate the authenticity of the entire number. This structure helps prevent processing errors and ensures the integrity of the transaction path.
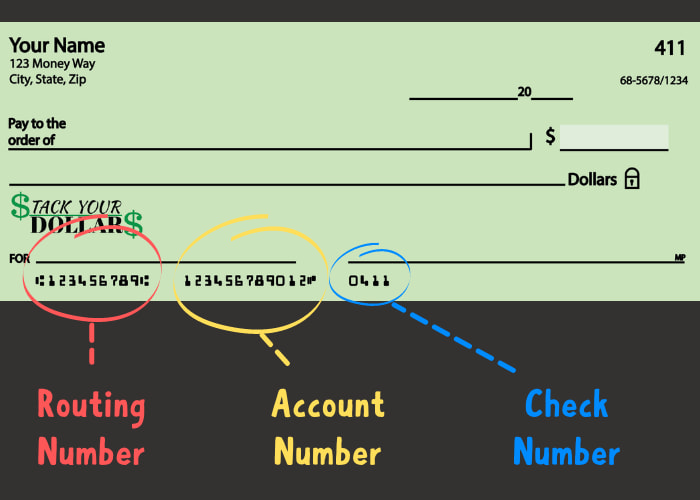
How Routing Numbers Are Used
You will encounter routing numbers in a variety of common financial scenarios, often without realizing it. They are the silent workhorses behind the following processes:
- Direct Deposit: Employers and government agencies use your routing number to deposit your salary or benefits directly into your bank account.
- Electronic Transfers: When you pay a bill online or transfer money between accounts, the routing number directs the funds to the correct financial institution.
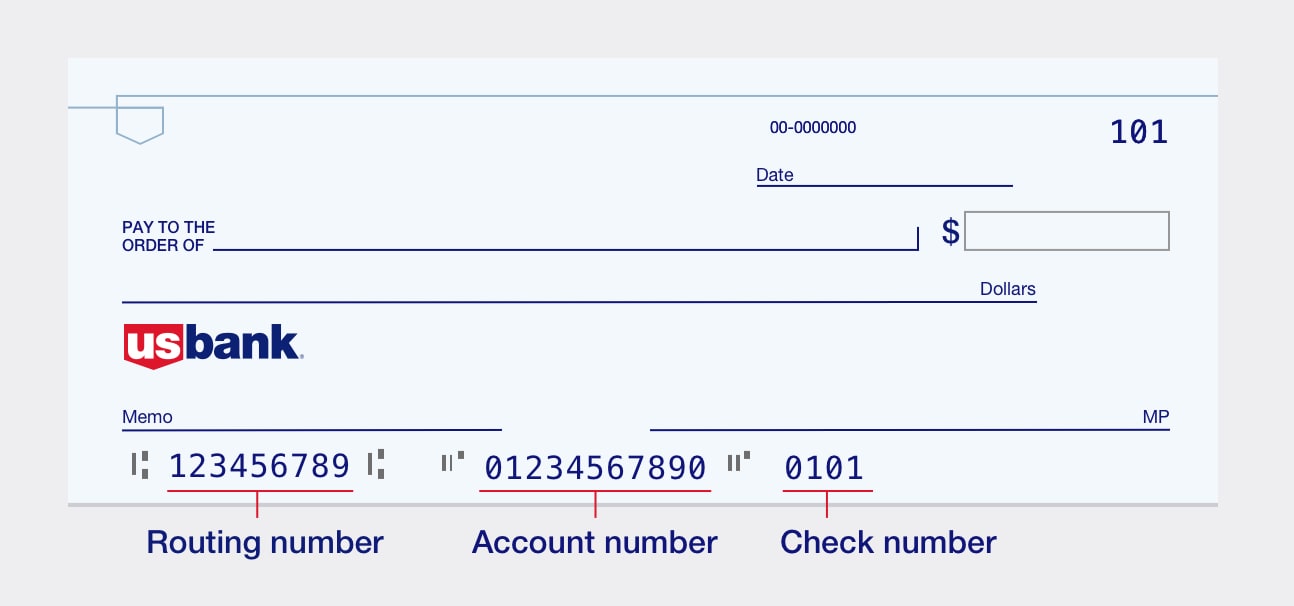
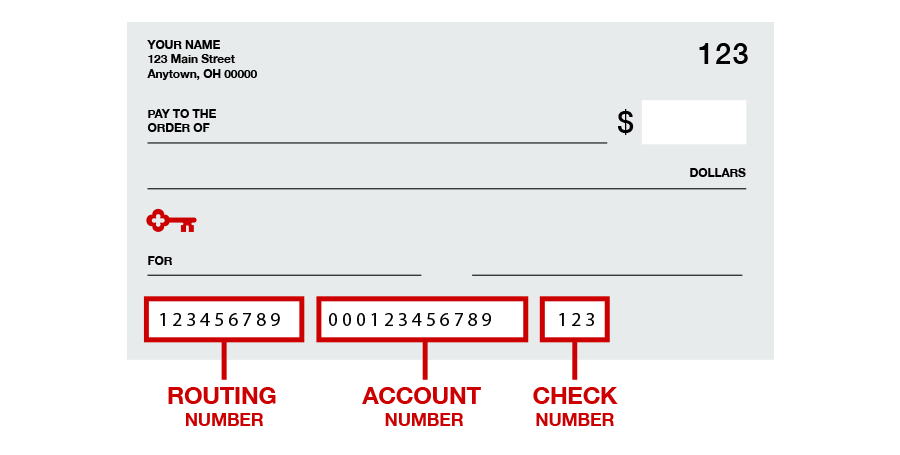
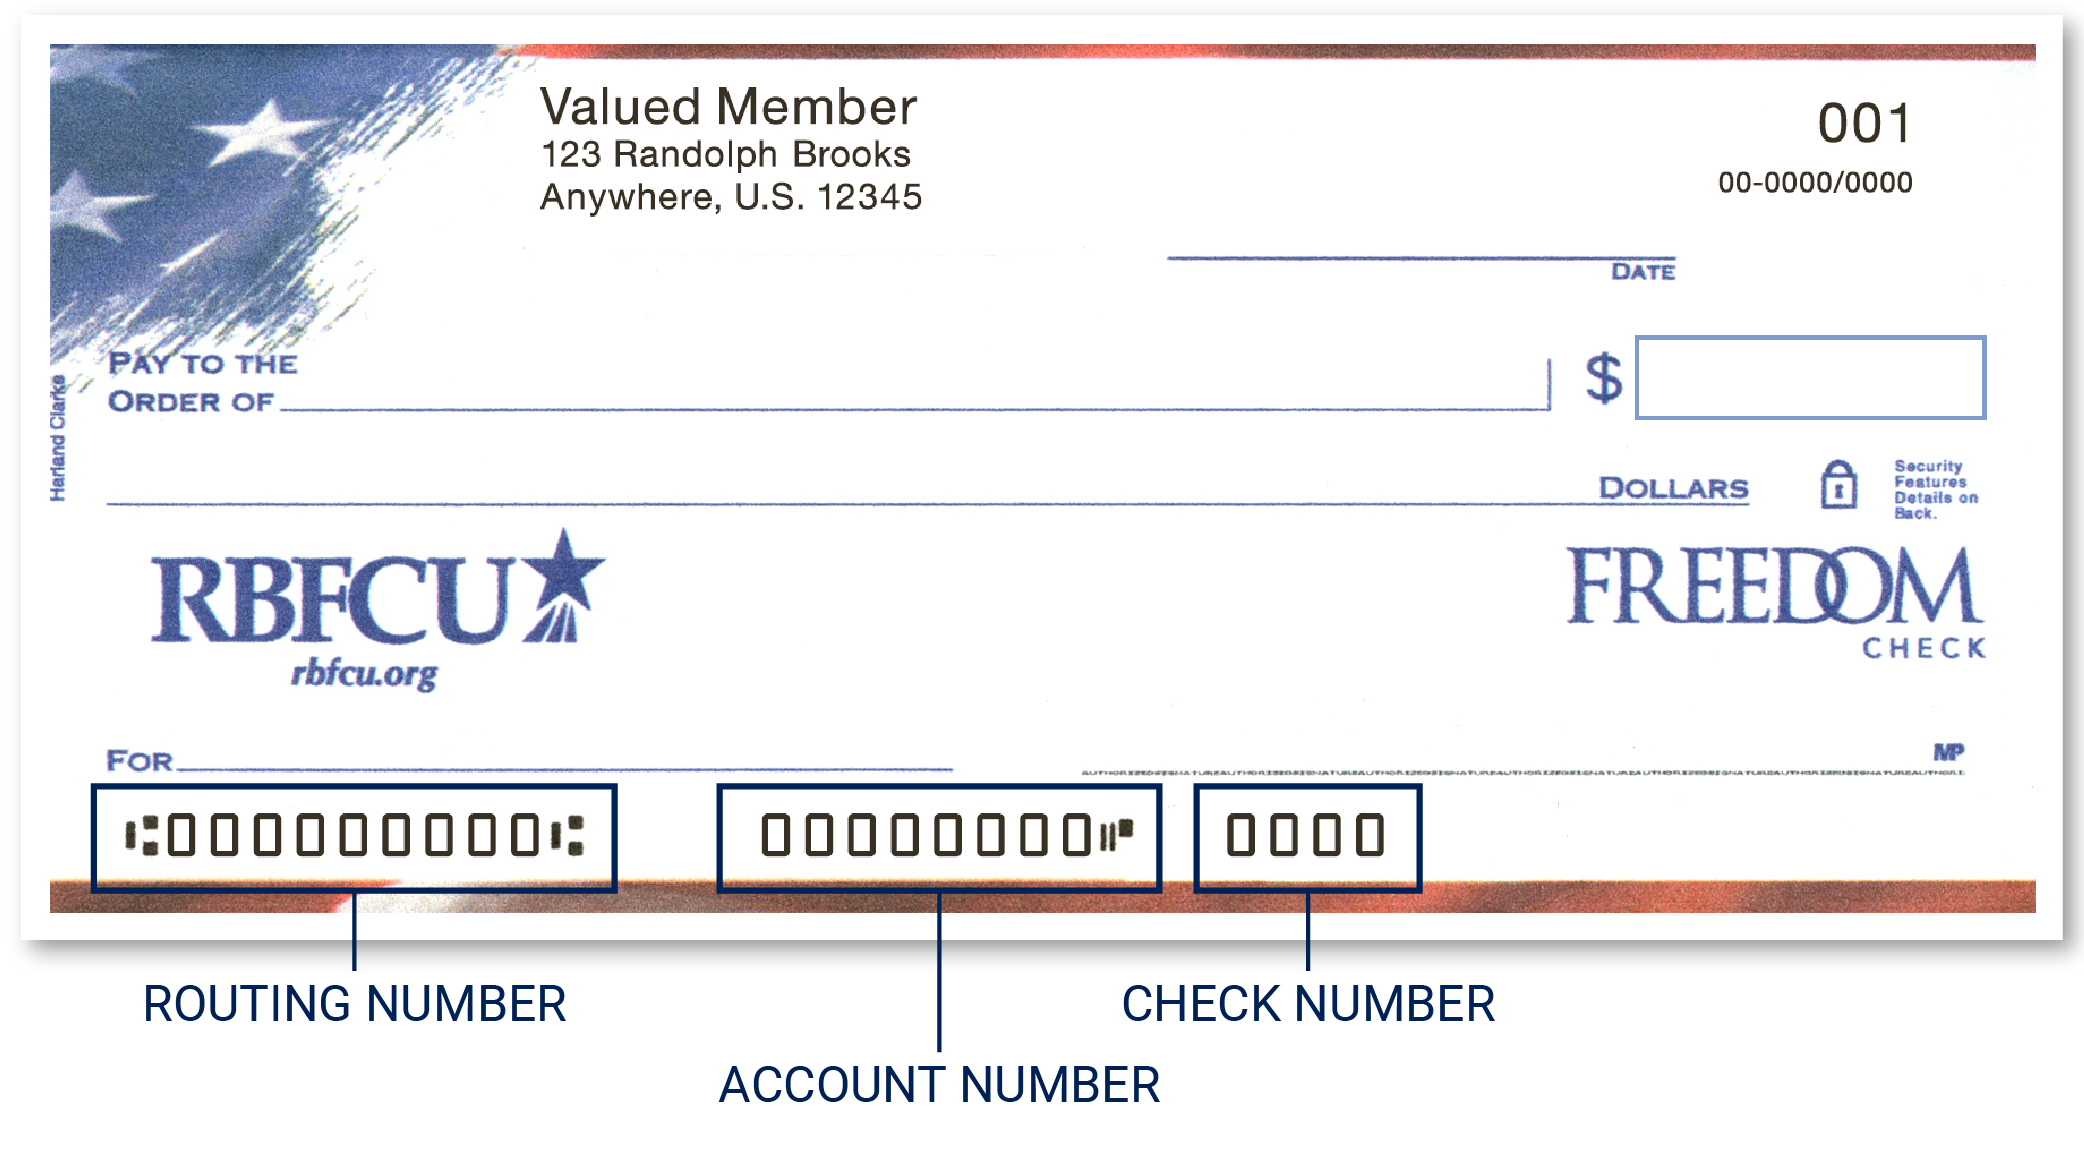
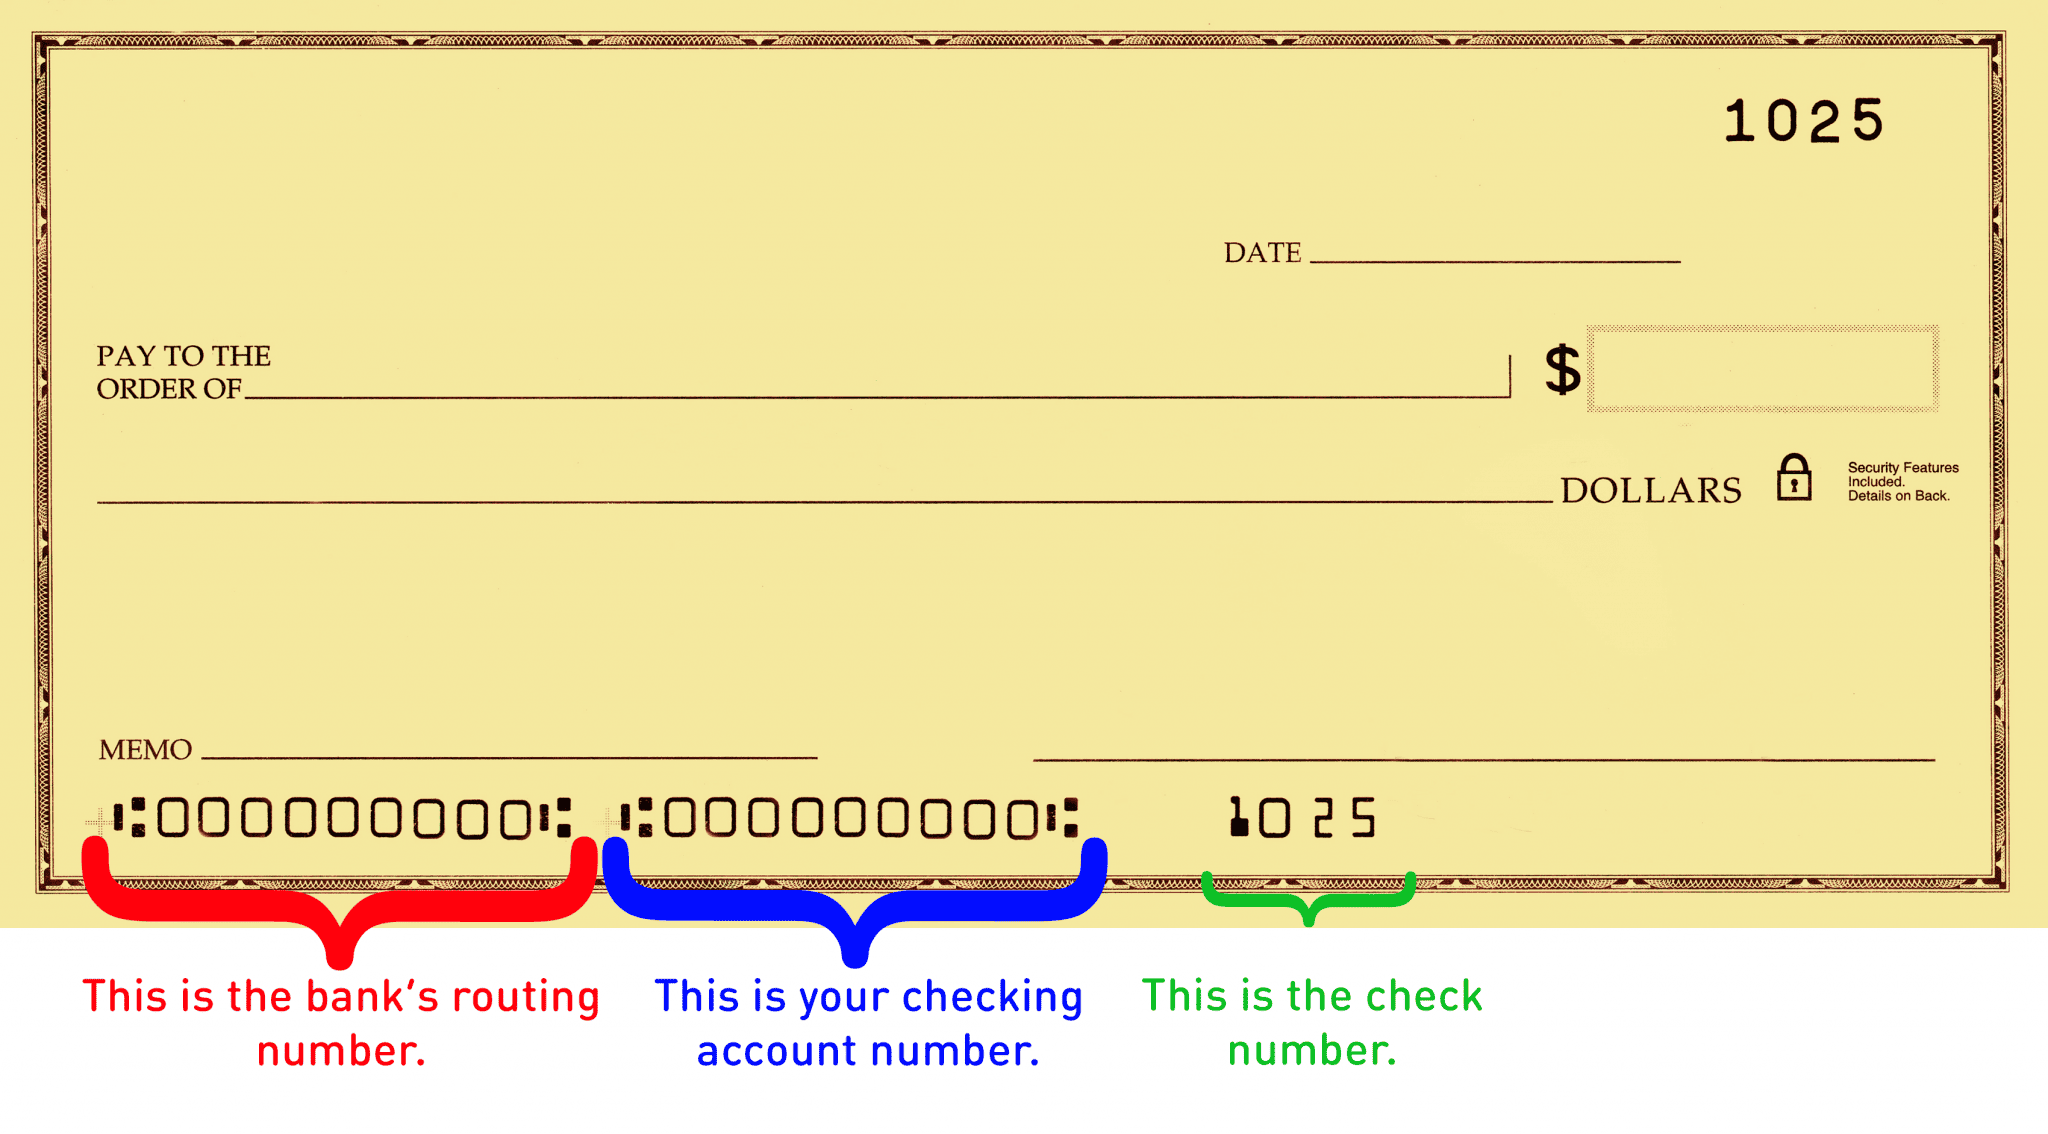
- Check Processing: The bottom of your personal checks features the routing number, allowing merchants and banks to clear payments efficiently.
The Role of the Account Number
If the routing number is the address, the account number is the specific mailbox within that address. This unique identifier is assigned directly to you by your financial institution and is used to distinguish your personal holdings from the millions of other accounts held at the same bank. While the routing number ensures the transaction reaches the right institution, the account number ensures the transaction is applied to the correct individual ledger. This distinction is crucial for maintaining the accuracy of your financial records and the security of your balance.
Account numbers are typically longer than routing numbers, ranging from 10 to 12 digits, though they can sometimes be shorter. Unlike routing numbers, which are standardized across an entire institution, your account number is entirely unique to you. You might share your bank's routing number with friends or billers, but your account number is highly sensitive information that should be guarded carefully. Sharing this number indiscriminately could potentially allow others to initiate unauthorized deposits or, in rare cases, attempts to debit funds, making it a key component of your personal financial identity.
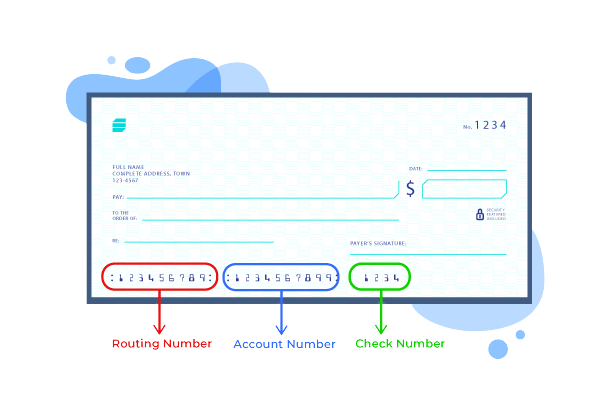
Protecting Your Financial Identifiers
Because both routing and account numbers are essential for moving money, they are prime targets for fraud and error. While routing numbers are generally public information found on checks and bank websites, account numbers require strict confidentiality. To protect your finances, it is wise to review your bank statements regularly, shred checks or documents containing this information before disposal, and verify the legitimacy of requests for this data. Being vigilant about where and how you share these details is the most effective way to prevent unauthorized access and ensure your transactions remain secure.
| Feature | Routing Number | Account Number |
|---|---|---|
| Length | 9 digits | 10-12 digits (varies) |
| Purpose | Identifies the financial institution | Identifies the specific account holder |
| Privacy Level | Generally public | Highly sensitive and private |
| Location on Check | First set of numbers at the bottom | Second set of numbers at the bottom |
Check Account And Routing Number Location at Justin Kim blog
Understanding The Bank Account Routing Number
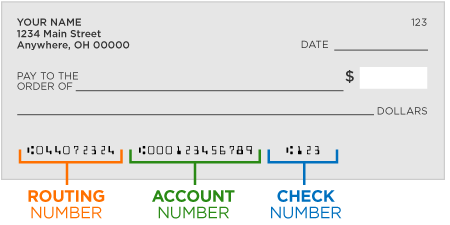
Routing number vs. account number: Where to find each | PayPal US

First Horizon Bank Routing Number
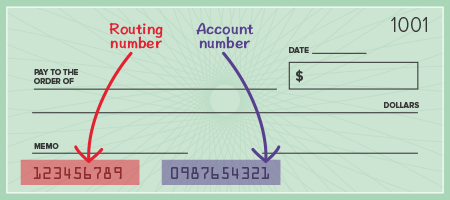
Example Of Check Routing And Account Number
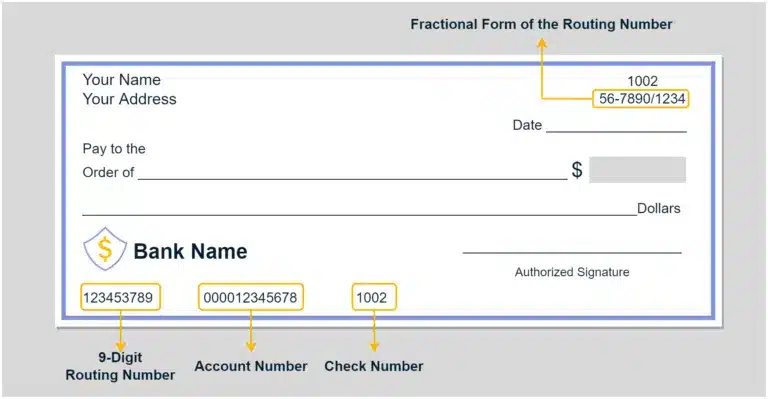
Routing Number vs. Account Number: The Quick Answer

Routing Number - 265270413 - IBERIABANK
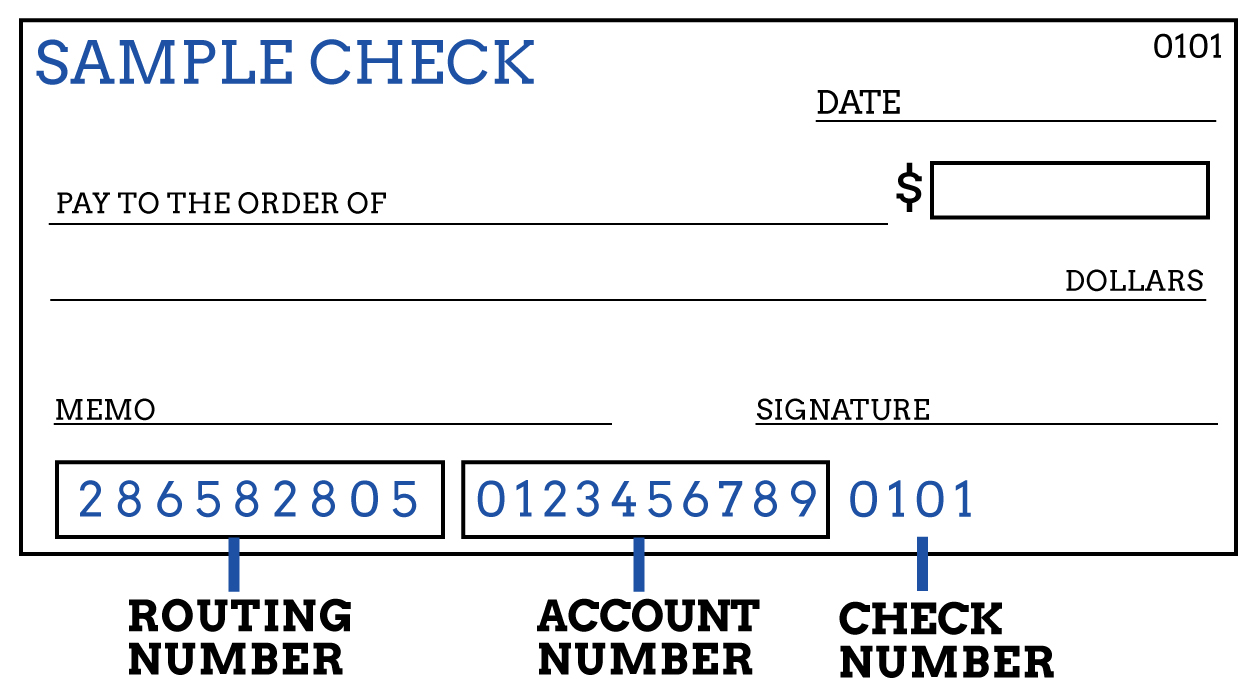
Find your Routing Number - First Utah Bank
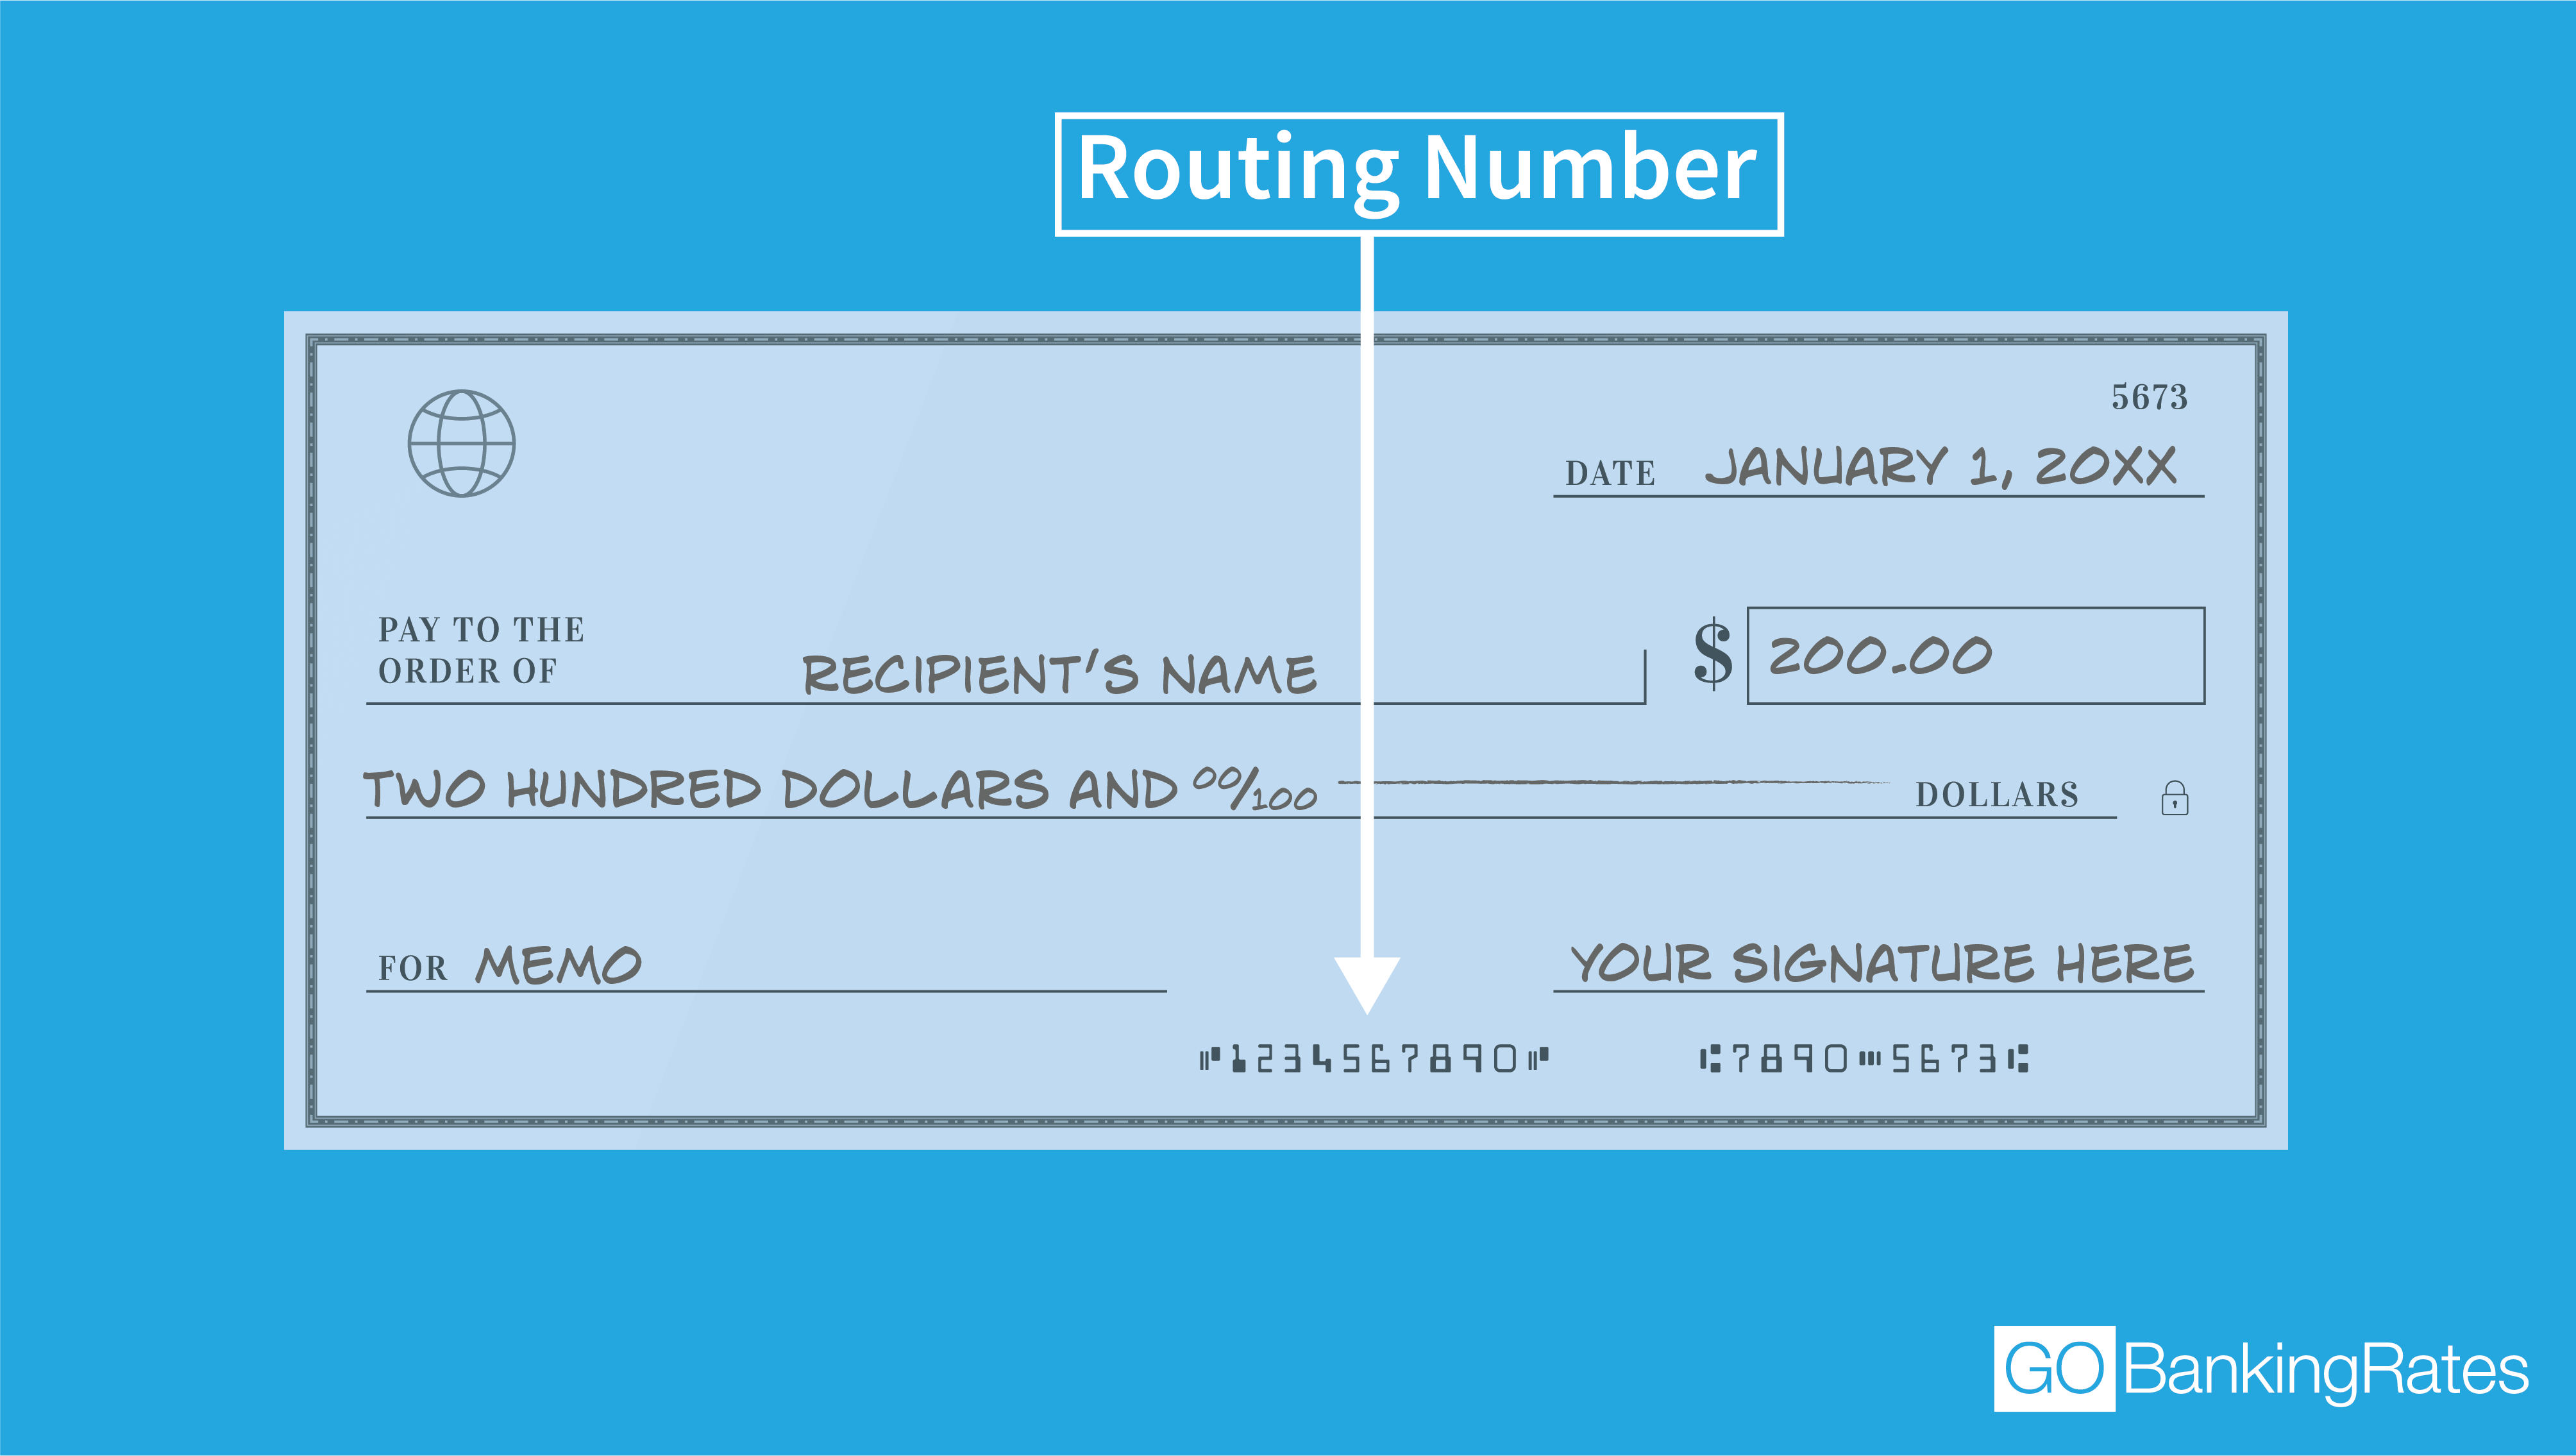
Check Routing And Account Numbers Show

Check Bank Account Number
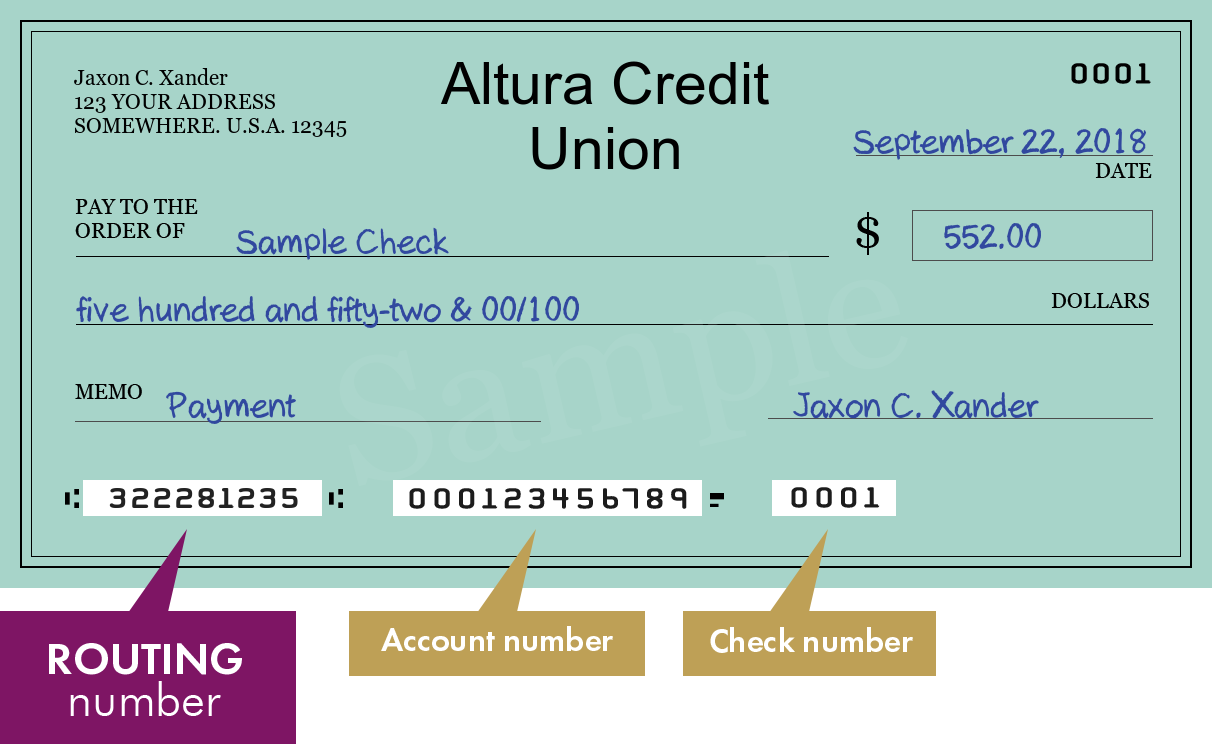
Altura Credit Union - search routing numbers, addresses and phones of ...
Where Is Your Account Number On A Check
Routing Number | What is it and Where to Find It | Benzinga

Routing Numbers Checker

Check Account And Routing Number Location at Justin Kim blog
Check Account And Routing Number Location at Justin Kim blog
Check your numbers
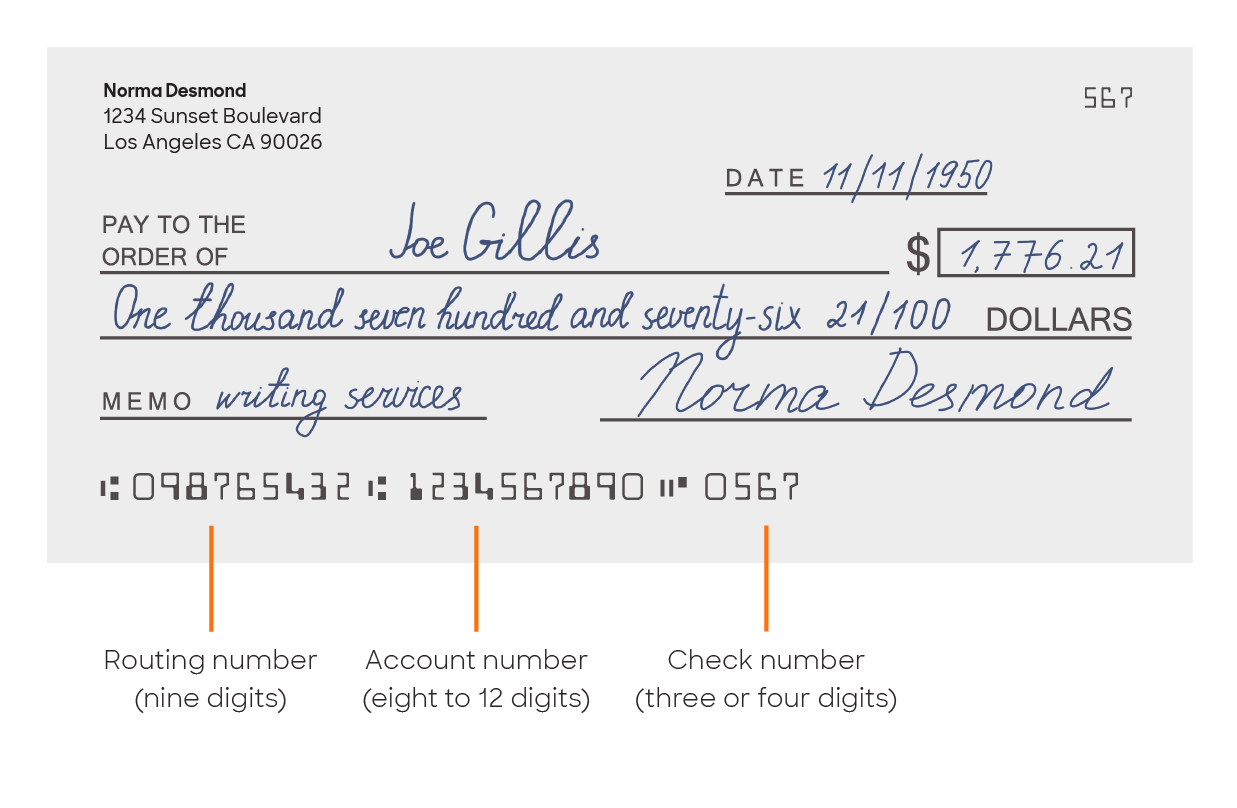
Where Do I Find the Routing Number on a Check? Why Do I Need It?

Routing Number vs. Account Number on Checks
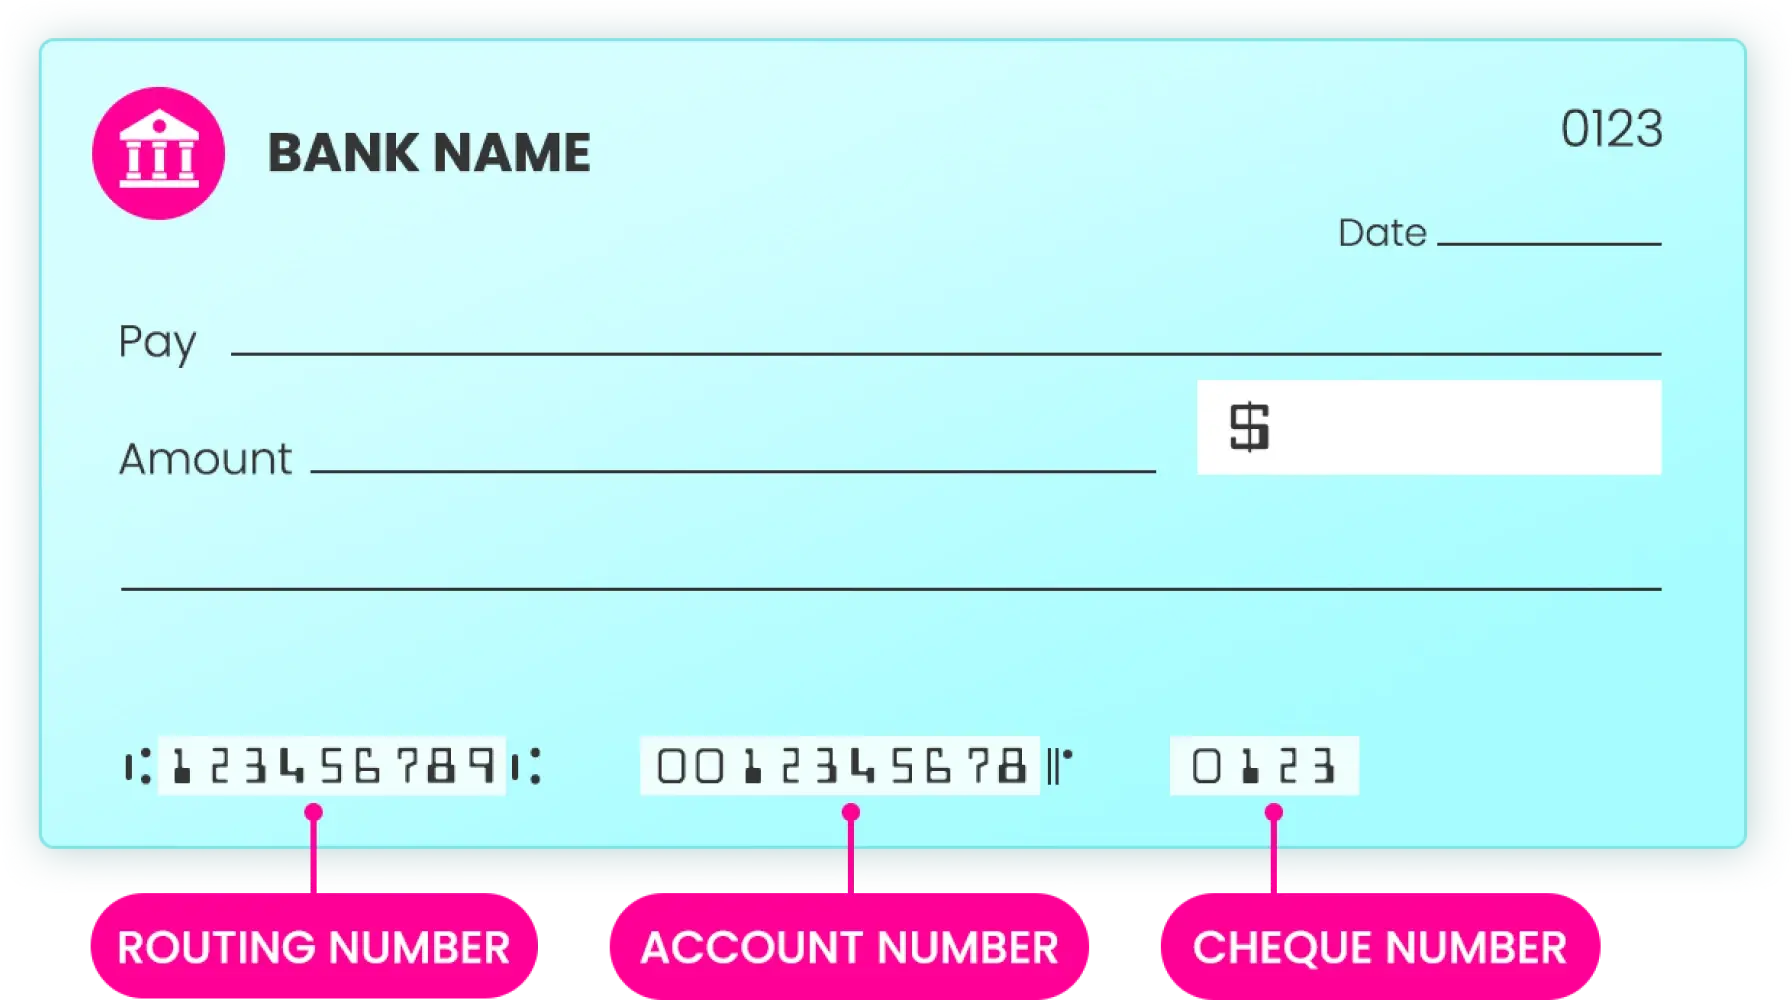
Addition Financial Routing Number | Complete List and FAQs