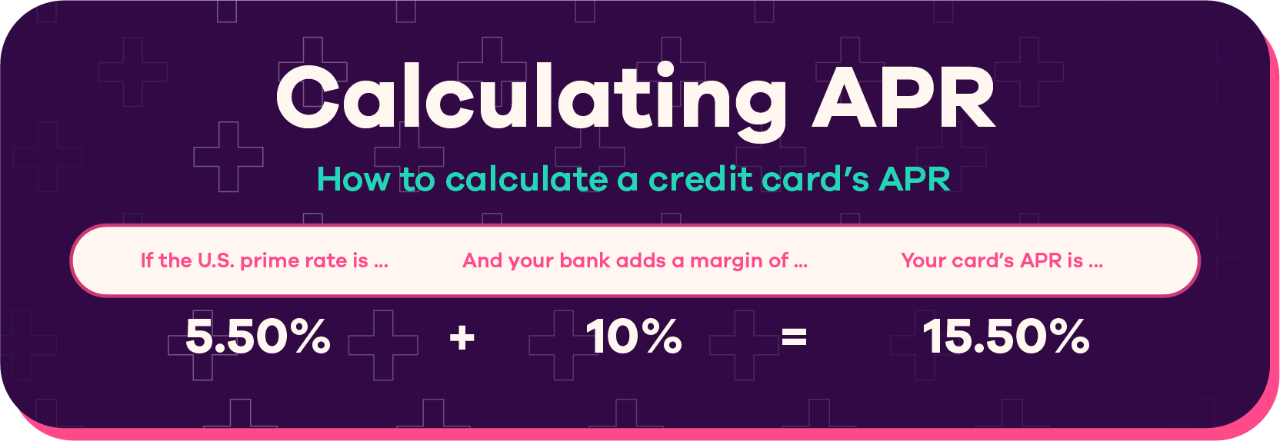
Understanding how to calculate APR, or Annual Percentage Rate, is essential for anyone navigating loans, credit cards, or investment returns. This figure represents the true cost of borrowing money or the true yield of an investment over a year, combining the interest rate with any associated fees. While the nominal interest rate tells you the base cost, the APR reveals the full financial picture by accounting for points, origination fees, and other charges. This transparency, mandated by law in many regions, empowers consumers to make accurate comparisons between different financial products. Mastering this calculation allows you to see beyond misleading low monthly payment ads and identify the most cost-effective option.
At its core, the APR calculation synthesizes the interest rate and the cost of obtaining the loan into a single, standardized percentage. Unlike a simple interest rate, which might only reflect the periodic charge on the principal, the APR spreads the total upfront costs across the life of the loan. This provides a more accurate measure of the annual cost, assuming the loan runs its full term. However, it is crucial to remember that the standard calculation assumes you keep the loan or investment until maturity, which may not always reflect real-world scenarios like early refinancing or prepayment.
The Core Formula and Its Logic
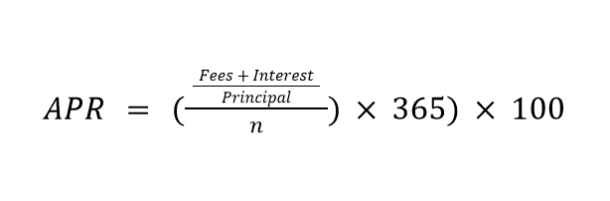
The fundamental method for how to calculate APR involves solving for the interest rate in a mathematical equation that equates the present value of all future cash flows to the initial loan amount. In essence, you are finding the interest rate that makes the net present value (NPV) of all payments (principal repaid plus interest paid) equal to the amount of cash you initially received. This complex algebraic process typically requires an iterative numerical method, such as the Newton-Raphson method, because the APR is embedded within the payment formula in a non-linear way. While the logic is straightforward, the computation is rarely done by hand due to its complexity.
Breaking Down the Components
To grasp the calculation, you must first identify the key variables. These include the principal loan amount, the total number of payment periods, the fixed payment amount for each period, and the total upfront costs or fees. For example, imagine a $10,000 loan with $500 in origination fees, resulting in the borrower receiving $9,500 but repaying a total of $12,000 over 5 years. The calculation would use the $9,500 as the present value, the $12,000 as the sum of all outflows, and the 60 monthly payments as the timeline. The goal is to find the rate that discounts those 60 outflows back to $9,500.
| Input Variable | Definition | Example Value |
|---|---|---|
| Principal (Loan Amount) | The total sum borrowed. | $10,000 |
| Upfront Fees | Costs charged at closing, subtracted from the principal. | -$500 |
| Net Disbursement | The amount the borrower actually receives. | $9,500 |
| Total Repayment | The sum of all interest and principal paid. | $12,000 |
| Payment Schedule | The frequency and duration of repayments. | 60 months |
Modern Calculation Methods and Tools
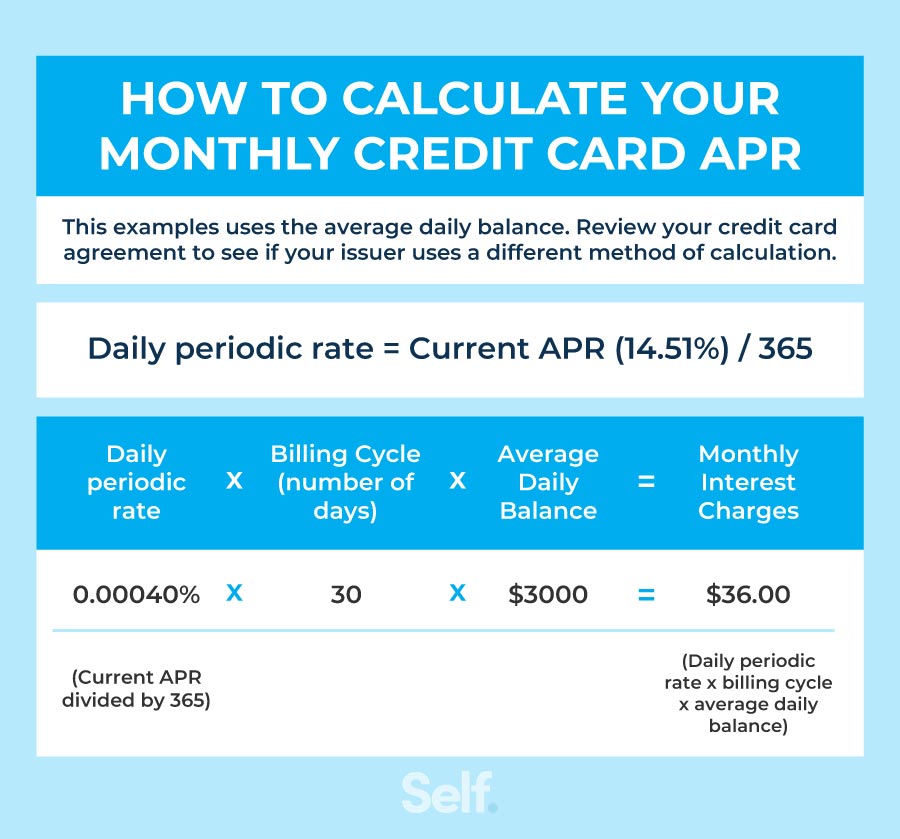
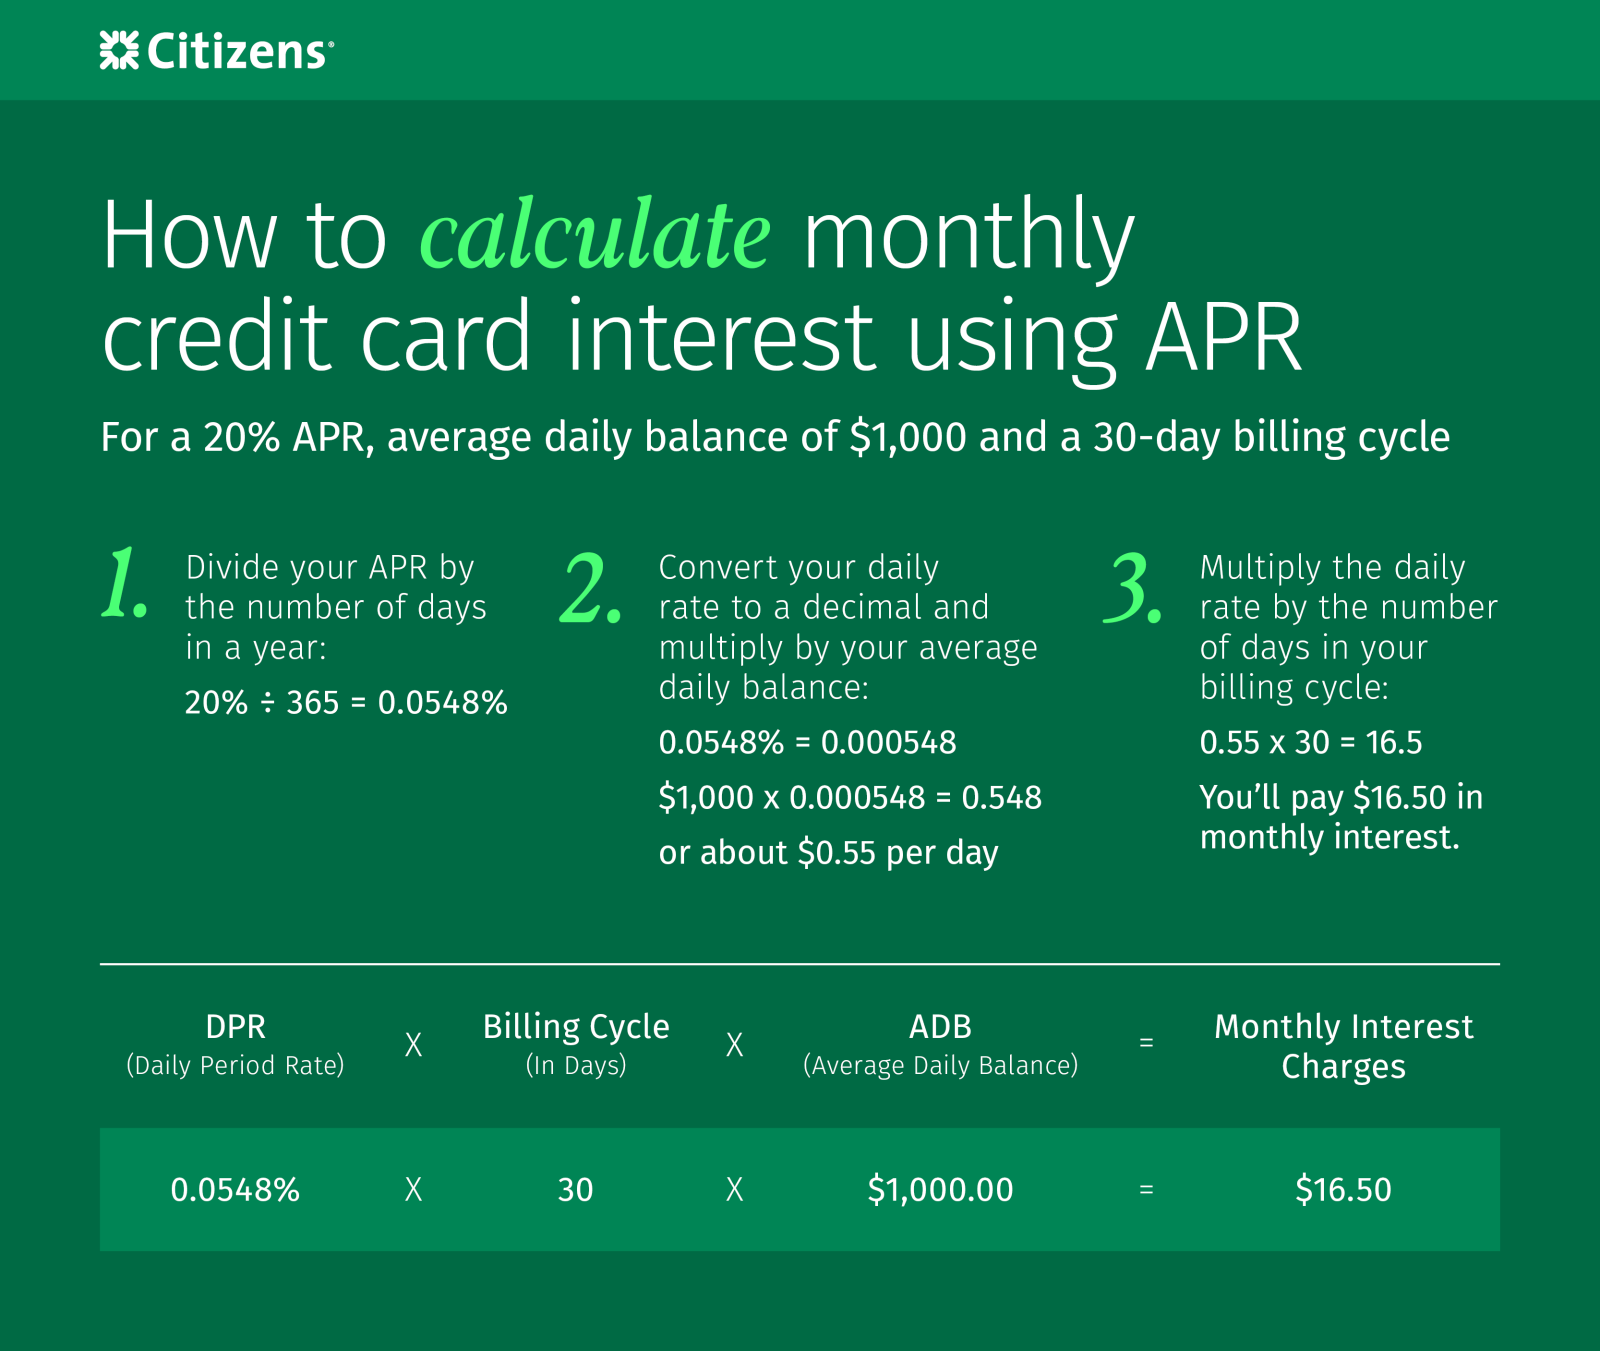
Given the complexity of the iterative process, most people rely on financial calculators, spreadsheet software, or online tools to determine how to calculate APR efficiently. In Microsoft Excel or Google Sheets, the `RATE` function is the standard tool for this task. You input the number of periods, the periodic payment (as a negative number representing cash outflow), and the present value (the net cash inflow), and the function outputs the periodic rate. Multiplying this rate by the number of periods in a year (e.g., 12 for monthly payments) provides the annualized APR. This digital approach delivers rapid and accurate results without manual error.
Regulatory standards, such as those enforced by the Consumer Financial Protection Bureau in the United States, dictate how APR must be calculated and disclosed. These rules ensure consistency so that comparing a mortgage from one bank to another is meaningful. They mandate that the APR includes not only the interest rate but also points, broker fees, and certain closing costs. However, it is important to be aware of its limitations. APR typically does not account for prepayment penalties or variable rate adjustments, and differences in how lenders calculate ancillary fees can still lead to slight variations. Therefore, while learning how to calculate APR is a powerful tool for financial literacy, it should be used in conjunction with a careful review of the full loan estimate documentation.

Annual Percentage Rate (APR) Formula Calculator, 54% OFF
Annual Percentage Rate Formula

Annual Percentage Rate Formula
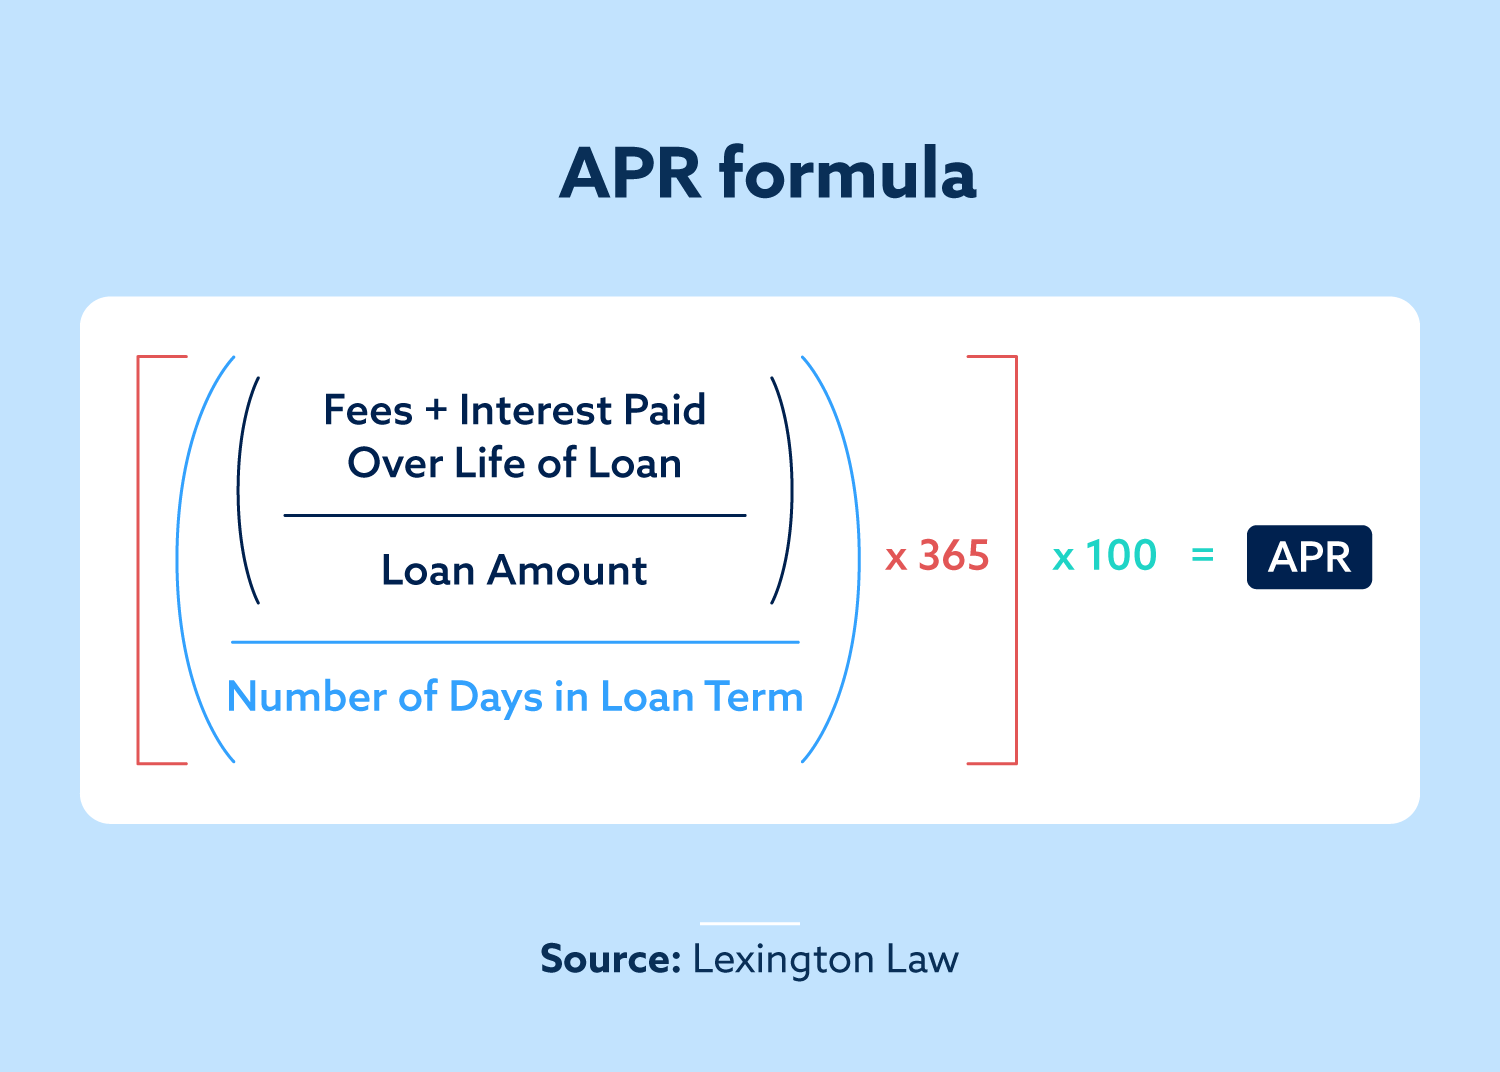
How Do I Calculate Apr From Interest Rate
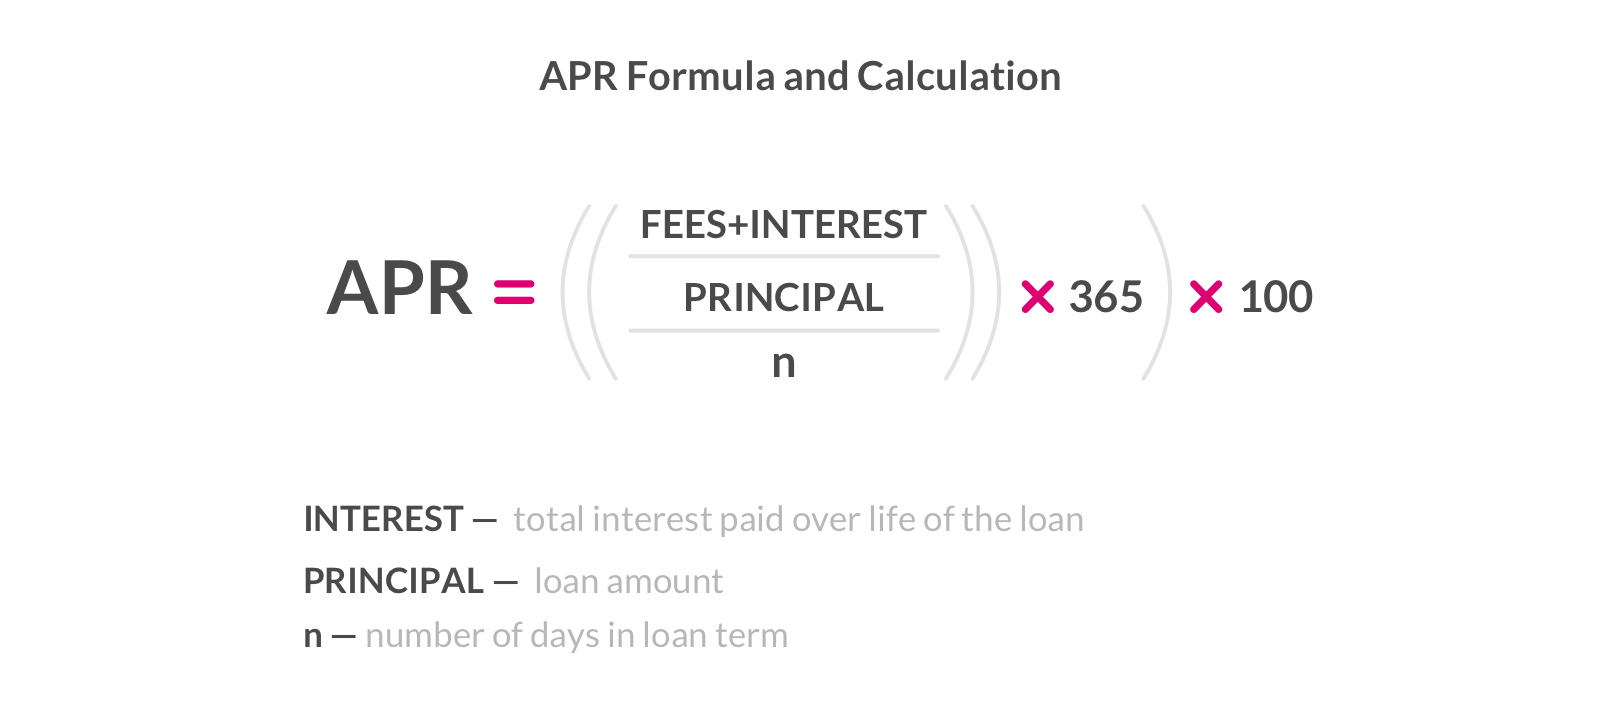
Apr Interest Rate Calculator
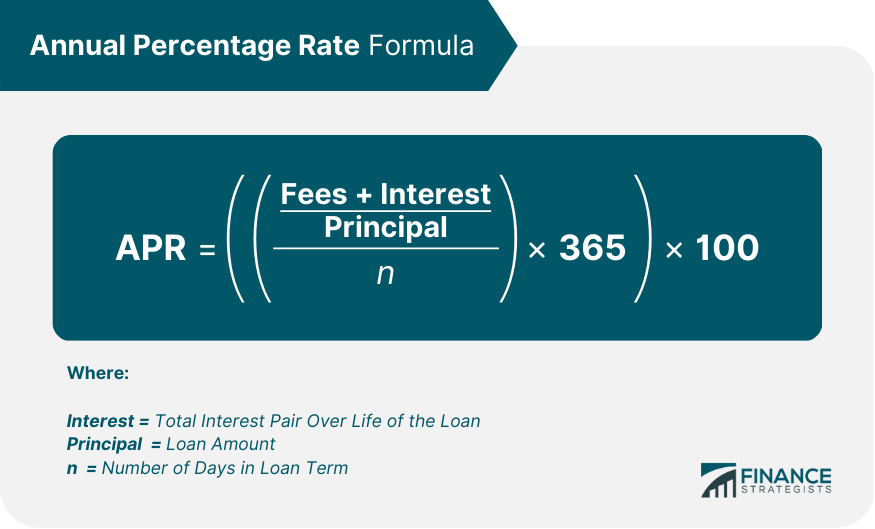
Annual Percentage Rate Formula

How to Calculate APR on Money You Borrow | Capital One
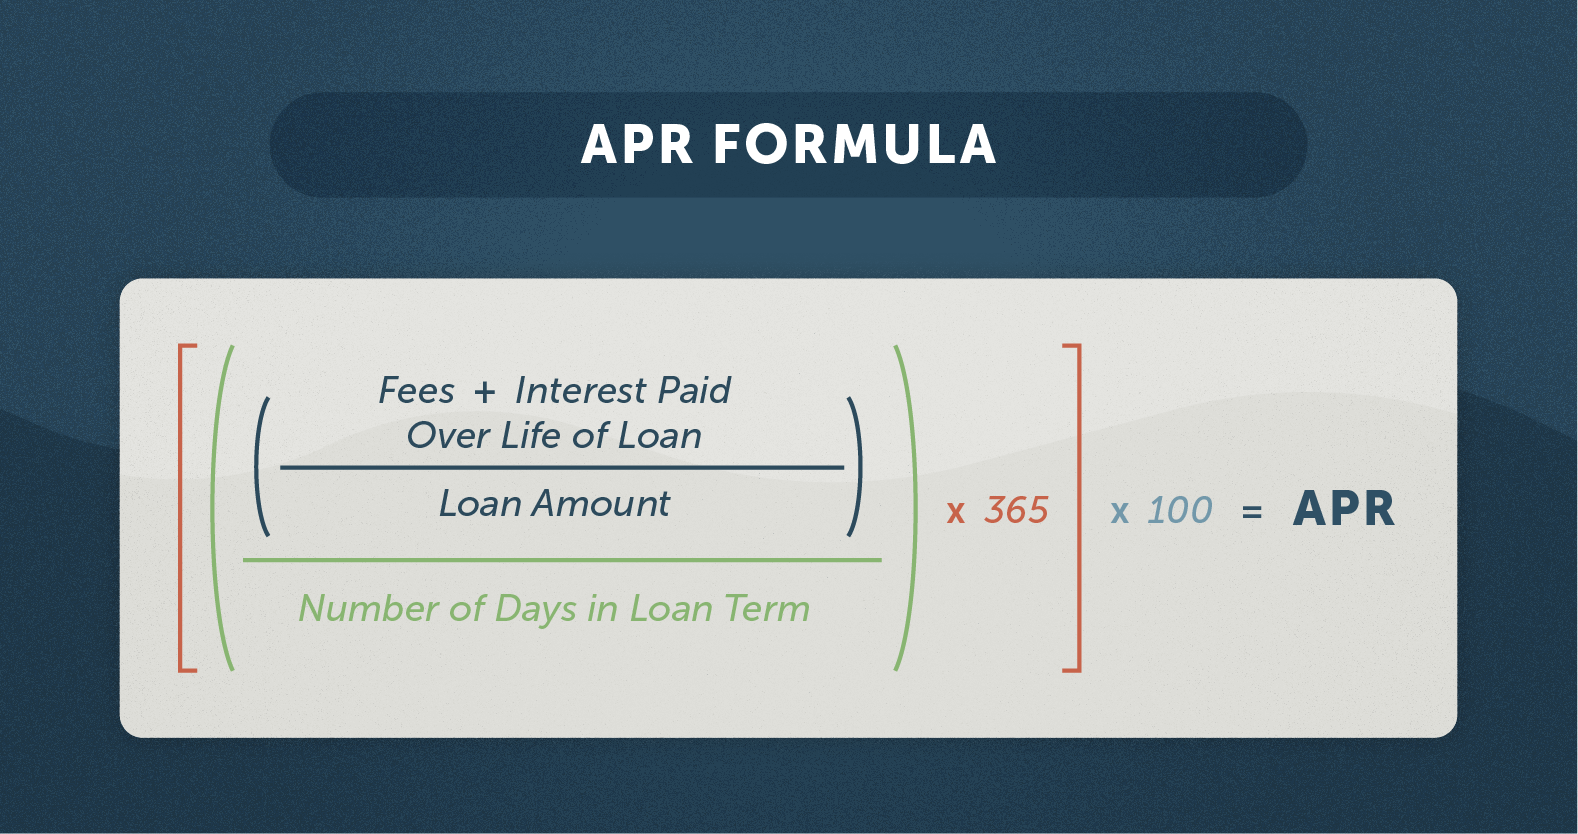
What is APR and How Does It Affect The Cost of a Loan? - GoldenFS.org
How to Calculate Annual Percentage Rate (APR) In Microsoft Excel

Annual Percentage Rate Formula

Annual Percentage Rate (APR) | LendingClub Glossary
What is APR and How Does It Work? - Self. Credit Builder.

How to Calculate APR on Money You Borrow | Capital One

How to Calculate APR in Excel - Earn and Excel
What Is APR and How Does It Work? | Ally

How to Calculate APR in Excel - Earn and Excel
How APR Works and Your Credit Score Impact | Citizens

How to Calculate APR in Excel - HowtoExcel.net

Apr Loan
How to Calculate APR on Money You Borrow