In the intricate world of accounting, the debits and credits chart stands as a foundational pillar, ensuring that every financial transaction is recorded with precision and balance. This essential tool is not merely a list of numbers; it is the structural framework that maintains the integrity of the double-entry bookkeeping system. Understanding how to interpret and apply this chart is critical for any business, from the smallest startup to the largest multinational corporation, as it directly impacts the accuracy of financial reports and strategic decision-making.
The Core Mechanics of Double-Entry Bookkeeping
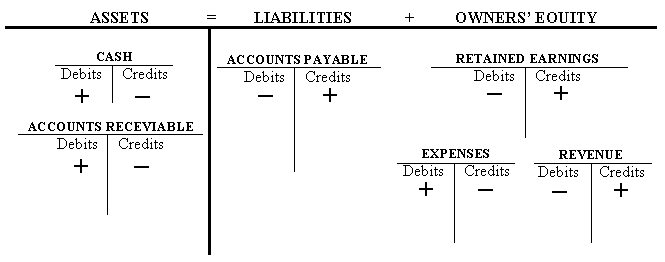
The principle behind the debits and credits chart is rooted in the fundamental equation of accounting: Assets = Liabilities + Equity. This equation must always remain in balance, and the double-entry system ensures that every transaction affects at least two accounts. For every financial entry, one account is increased (or another is decreased) by a debit, while another account is increased (or decreased) by a credit. This creates a self-regulating mechanism where the total debits must always equal the total credits, preventing errors and providing a robust audit trail.
Debits: The Left Side of the Ledger
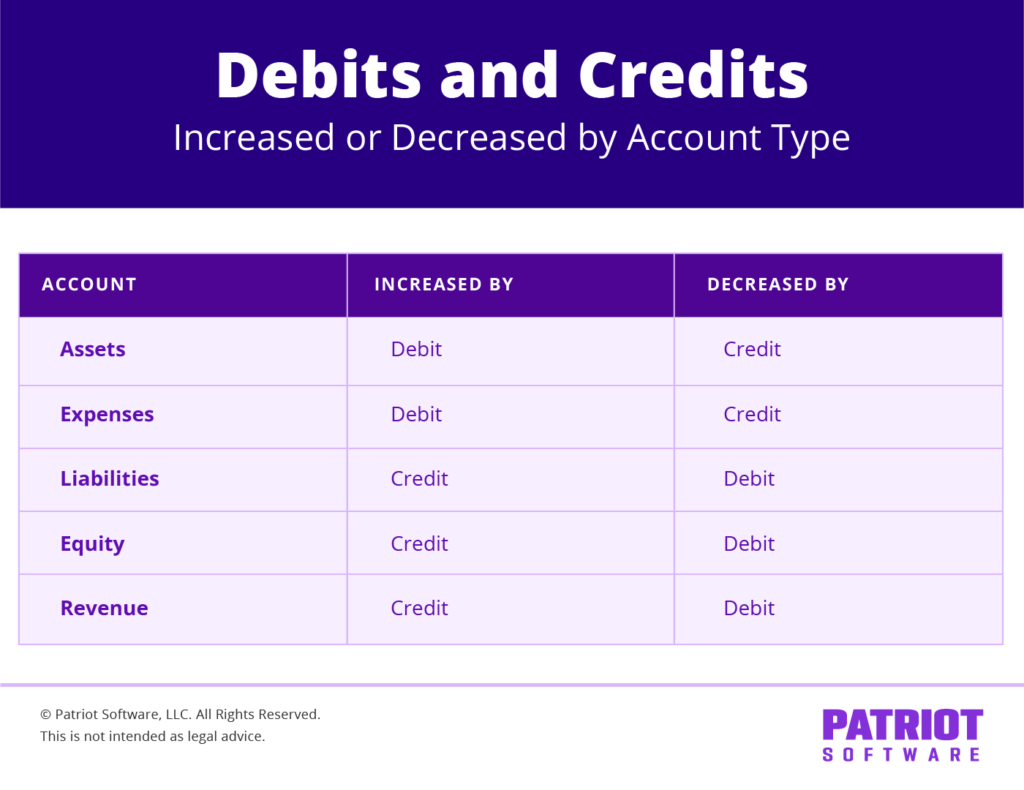
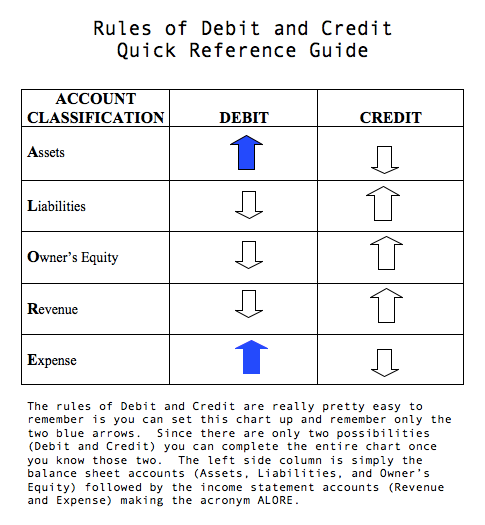
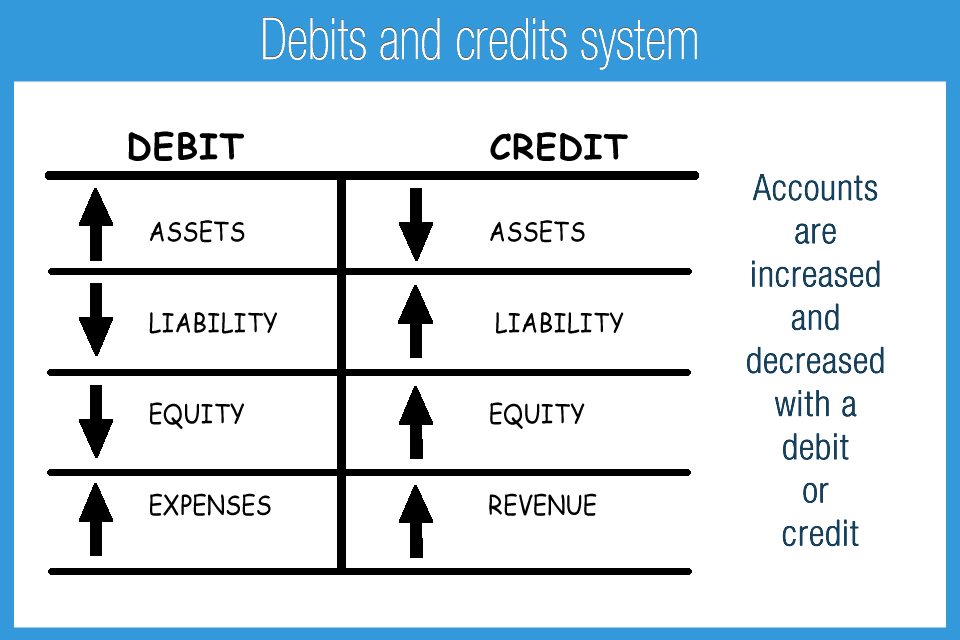
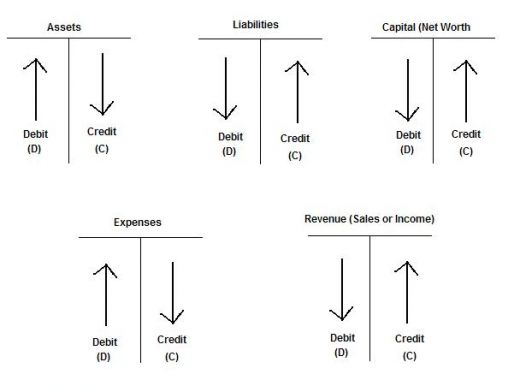
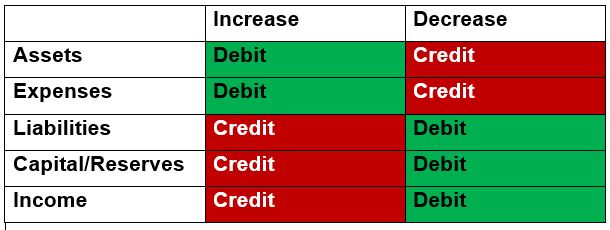
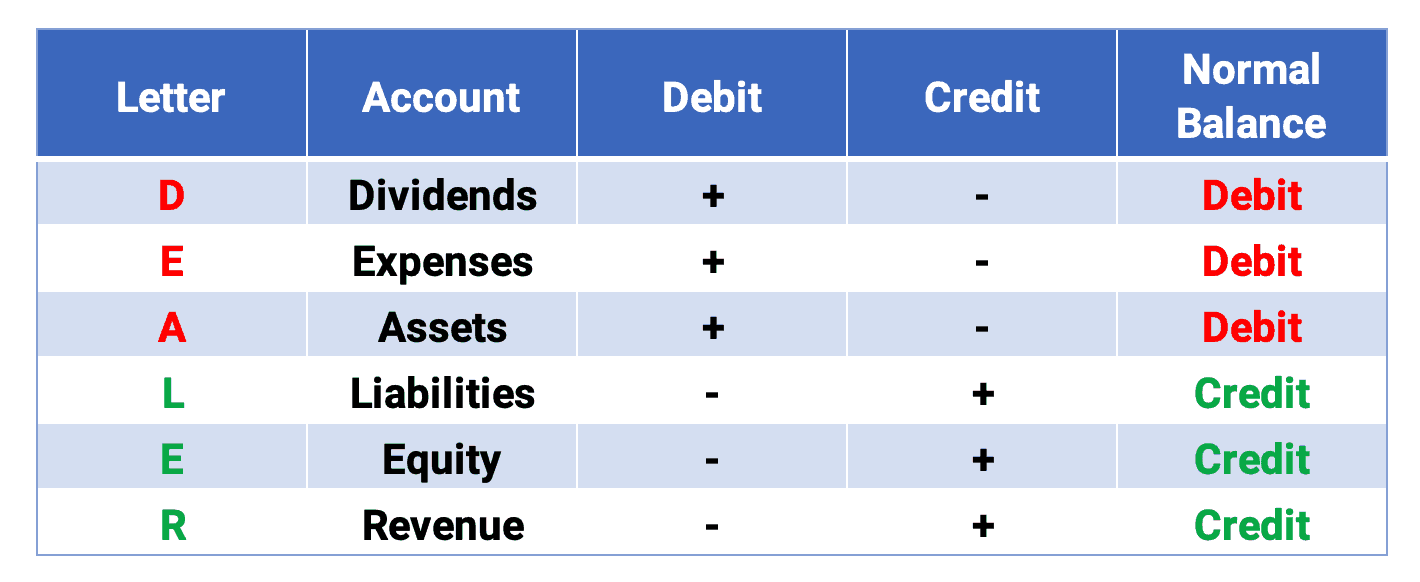
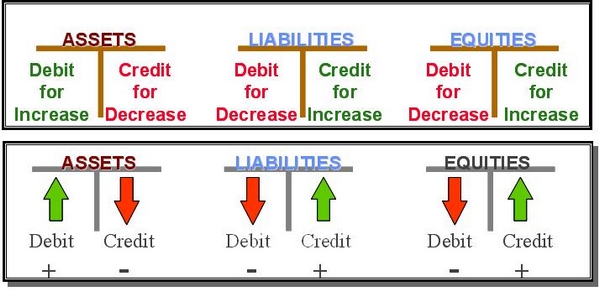
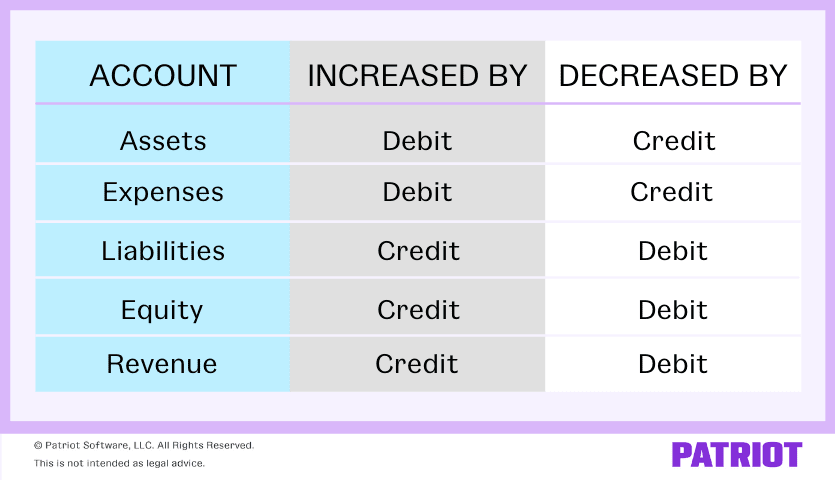
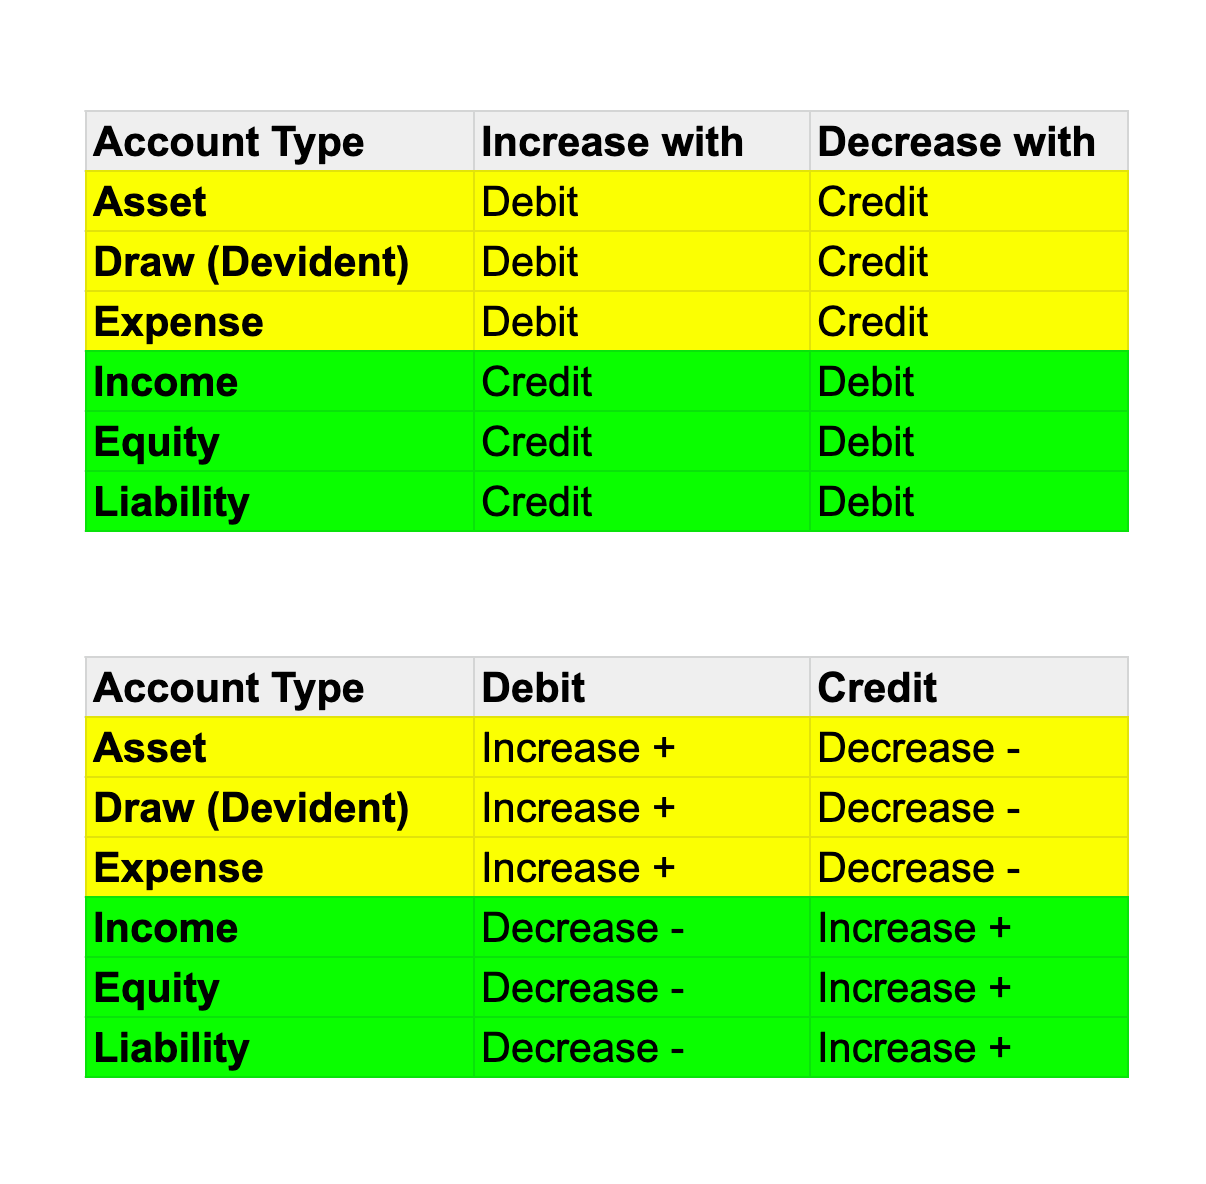
Debits are entries recorded on the left side of a T-account and serve to increase asset and expense accounts. Conversely, they decrease liability, equity, and revenue accounts. When a company receives cash, its asset account increases through a debit. Similarly, when a business incurs an expense, the expense account is debited to reflect the cost of operations. Mastering the application of debits allows businesses to accurately track the inflow and utilization of resources, providing a clear picture of financial health.
Credits: The Right Side of the Ledger
Credits are entries recorded on the right side of a T-account and function in the opposite manner to debits. They increase liability, equity, and revenue accounts while decreasing asset and expense accounts. For instance, when a company takes out a loan, the liability account is credited to acknowledge the obligation. When sales are made, the revenue account is credited to record the income. The disciplined use of credits ensures that the sources of funds are properly documented and categorized.
Navigating the Debits and Credits Chart
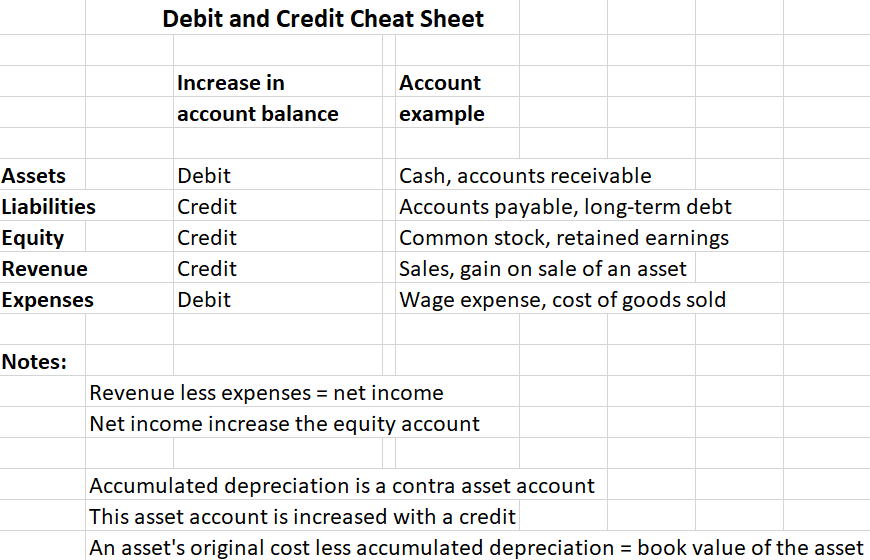
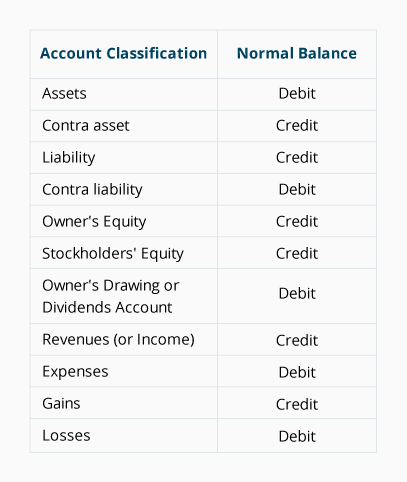
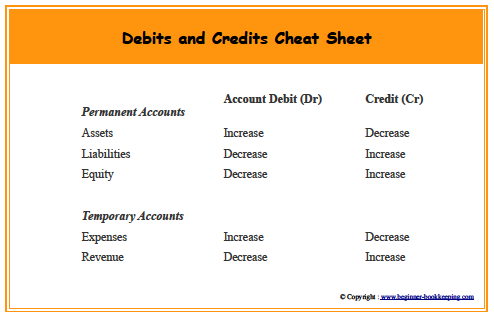
A comprehensive debits and credits chart typically categorizes accounts into key financial sections, including Assets, Liabilities, Equity, Revenue, and Expenses. This chart acts as a quick reference for bookkeepers and accountants, helping them determine the correct side of the ledger for any transaction. Rather than relying on memorization, professionals can use the chart to understand the inherent nature of each account type and apply the rules consistently to maintain accuracy.
| Account Type | Normal Balance | Effect of a Debit | Effect of a Credit |
|---|---|---|---|
| Assets | Debit | Increases | Decreases |
| Liabilities | Credit | Decreases | Increases |
| Equity | Credit | Decreases | Increases |
| Revenue | Credit | Decreases | Increases |
| Expenses | Debit | Increases | Decreases |
Practical Application and Common Scenarios
Applying the debits and credits chart to real-world scenarios demystifies the process for learners. Consider a business purchasing office equipment with cash; the asset account for equipment is debited to reflect the acquisition, while the cash asset account is credited to show the outflow. In another scenario, when a company pays off a portion of its bank loan, the liability account is debited to reduce the balance, and the cash account is credited. These practical examples reinforce how the system provides a logical structure for complex financial activities.
Ensuring Accuracy and Compliance
Beyond simple tracking, the debits and credits chart is a vital instrument for ensuring regulatory compliance and preparing accurate financial statements. By rigorously following the chart, companies can generate a trial balance that verifies the equality of debits and credits. This step is crucial before finalizing reports like the balance sheet and income statement. Auditors and stakeholders rely on this structural integrity to assess the validity of the financial data, making the chart an indispensable tool for transparency and corporate governance.
Conclusion: The Bedrock of Financial Clarity
Mastering the debits and credits chart transforms abstract financial data into a clear and actionable narrative of a company’s performance. It eliminates ambiguity and provides a universal language for accountants, financiers, and business owners. By adhering to these fundamental rules, organizations ensure that their financial records are not only accurate but also reliable, laying a solid groundwork for sustainable growth and informed strategic planning.