If you're in the market for a manufactured home built before 1976, you're likely aware of the unique charm and history these homes possess. However, financing such a home can present its own set of challenges. This article aims to guide you through the process of financing a pre-1976 manufactured home, helping you understand the intricacies and navigate the path to homeownership.
Understanding Pre-1976 Manufactured Homes
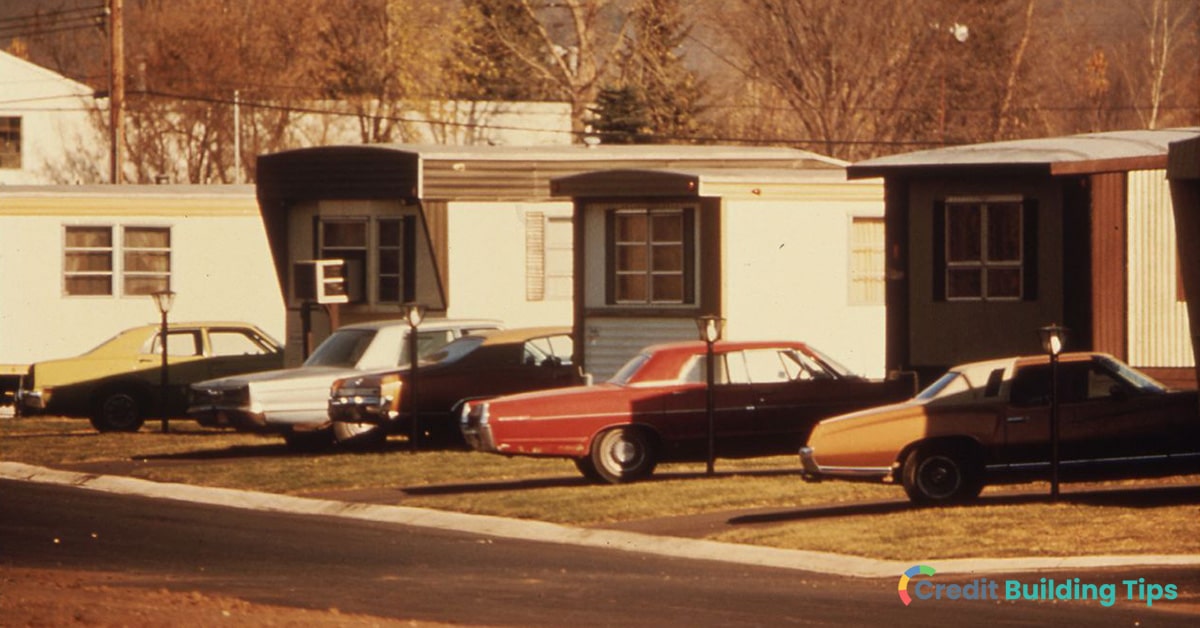
Manufactured homes built before 1976, often referred to as mobile homes, were constructed under different building codes and standards than those in use today. The HUD (U.S. Department of Housing and Urban Development) Code, which sets the standards for manufactured homes, was implemented in 1976. Homes built before this date may not comply with these modern standards, which can impact financing options.
Challenges in Financing Pre-1976 Manufactured Homes
Financing a pre-1976 manufactured home can be challenging due to several reasons:

- Lack of Appraisal Value: Pre-1976 homes may not hold the same resale value as newer homes, making them less attractive to lenders.
- Age and Condition: Older homes may require more maintenance and repairs, which can be costly and deter lenders.
- Location: If the home is not located in a permanent foundation, it may be considered personal property rather than real estate, further complicating financing.
FHA Loans: A Viable Option
While traditional mortgage loans may be difficult to secure, FHA (Federal Housing Administration) loans can be a viable option for financing pre-1976 manufactured homes. FHA loans are government-backed and designed to make homeownership more accessible. Here's what you need to know:
- FHA loans require the home to be on a permanent foundation and meet certain HUD standards.
- The home must be your primary residence.
- You'll need to make a down payment of at least 3.5% of the loan amount.
Other Financing Options
Besides FHA loans, there are other financing options to consider:
- Chattel Loans: These are personal property loans designed specifically for manufactured homes. However, they typically have higher interest rates and shorter repayment terms than traditional mortgages.
- Private Lenders: Some private lenders may be willing to finance pre-1976 manufactured homes, but they may charge higher interest rates and fees.
Preparing Your Home for Financing
To increase your chances of securing financing, it's crucial to prepare your home. This may involve:
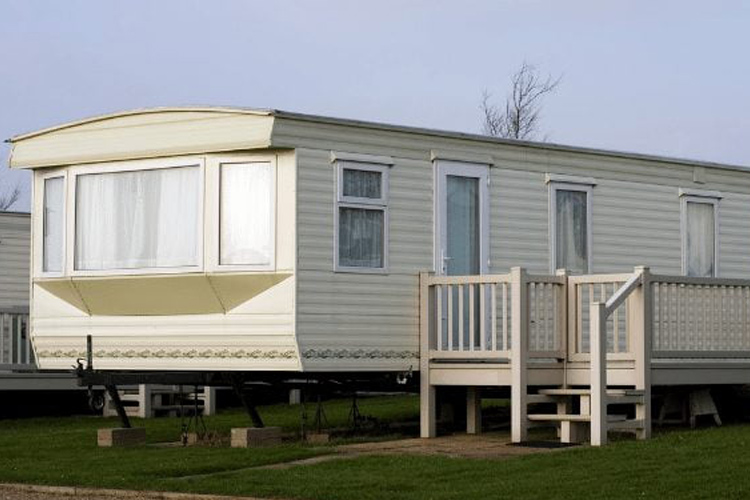
- Making necessary repairs and updates to ensure the home is in good condition.
- Installing a permanent foundation, if possible, to meet FHA loan requirements.
- Gathering documentation about the home's history, including any improvements or renovations.
Working with a Lender
When working with a lender, it's essential to be transparent about the home's age and condition. Provide as much information as possible to help the lender understand the value and potential of your home. A reputable lender should be able to guide you through the process and help you find the best financing option for your situation.
In the world of manufactured homes, age isn't just a number—it's a story. With the right knowledge and preparation, you can turn the unique history of your pre-1976 manufactured home into a compelling narrative that secures your path to homeownership.