In the dynamic world of real estate investing, understanding the down payment requirements for investment properties is crucial. This article delves into the investment property down payment landscape in 2018, providing a comprehensive guide to help you make informed decisions.
Understanding Investment Property Down Payments
When purchasing an investment property, the down payment is the initial amount you pay upfront, with the remaining balance financed through a mortgage. Unlike primary residences, investment properties typically require higher down payments due to the increased risk they pose to lenders. Let's explore the down payment landscape in 2018.
Conventional Loans for Investment Properties
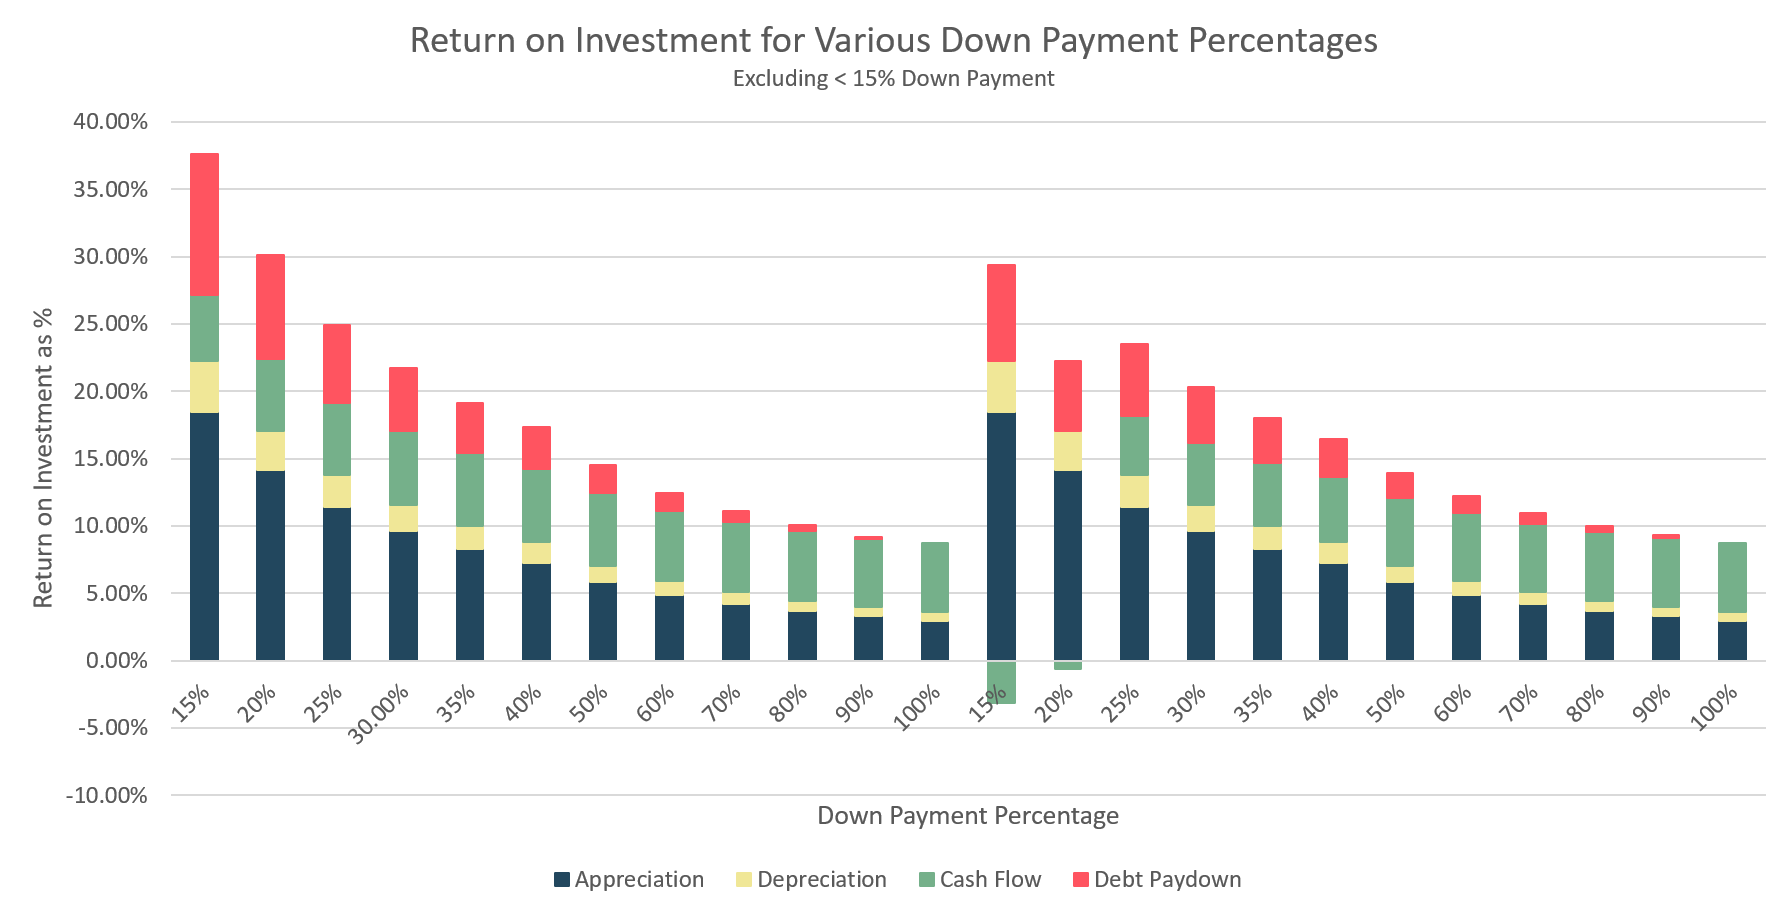
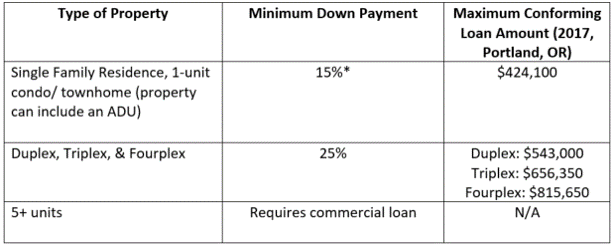
Conventional loans, backed by Fannie Mae or Freddie Mac, are popular choices for investment property purchases. In 2018, the minimum down payment for a conventional investment property loan was 15% to 20%, depending on the loan-to-value (LTV) ratio and the borrower's credit score. A higher down payment could help you secure a lower interest rate and avoid private mortgage insurance (PMI).

FHA Loans for Investment Properties
While FHA loans are primarily designed for primary residences, they can also be used for investment properties, albeit with stricter guidelines. In 2018, FHA loans required a minimum down payment of 3.5% for investment properties, making them an attractive option for investors with limited funds. However, keep in mind that FHA loans for investment properties come with additional requirements, such as a minimum credit score of 640 and a maximum LTV ratio of 75%.
Down Payment Assistance Programs
For investors struggling to come up with the necessary down payment, various programs offered by state and local governments, as well as non-profit organizations, can provide assistance. These programs often take the form of grants, low-interest loans, or tax credits. In 2018, many of these programs remained active, helping investors overcome the down payment hurdle.
State and Local Programs
State and local governments often offer down payment assistance programs to encourage homeownership and stimulate economic growth. These programs can provide significant financial help, with some offering assistance of up to $20,000 or more. To find state and local programs in your area, consult your state's housing finance agency or look up local government websites.

National Programs
Several national programs also provide down payment assistance. For example, the National Homebuyers Fund (NHF) offers down payment grants to eligible homebuyers, including investors, purchasing properties in targeted areas. The U.S. Department of Agriculture (USDA) and the U.S. Department of Housing and Urban Development (HUD) also provide loan programs with low or no down payment requirements for investment properties located in rural or targeted urban areas.
Alternative Financing Options
If traditional mortgage options don't meet your needs, consider alternative financing methods to fund your investment property down payment. These options can provide flexibility and faster access to funds but may come with higher costs or unique requirements.
Hard Money Loans
Hard money loans, provided by private lenders or specialized hard money lenders, can offer quick funding and flexible underwriting criteria. However, these loans typically come with higher interest rates and shorter repayment terms. In 2018, hard money loans remained an attractive option for investors seeking fast funding for fix-and-flip projects or long-term rental properties.
Crowdfunding Platforms
Real estate crowdfunding platforms allow investors to pool their resources to fund real estate projects, including down payments for investment properties. These platforms can provide access to capital without the need for traditional bank financing. In 2018, several crowdfunding platforms focused on real estate investing gained popularity, offering investors new avenues for funding their projects.
Understanding the investment property down payment landscape in 2018 is essential for real estate investors seeking to grow their portfolios. By exploring conventional loans, FHA loans, down payment assistance programs, and alternative financing options, investors can make informed decisions and secure the necessary funds to purchase their desired investment properties.