Money orders, a convenient and secure way to send money, have also been exploited by criminal elements for illicit activities, including money laundering. This article delves into the nexus of money orders and money laundering, exploring how they are used, the risks involved, and the measures in place to combat this abuse.
Understanding Money Orders and Money Laundering
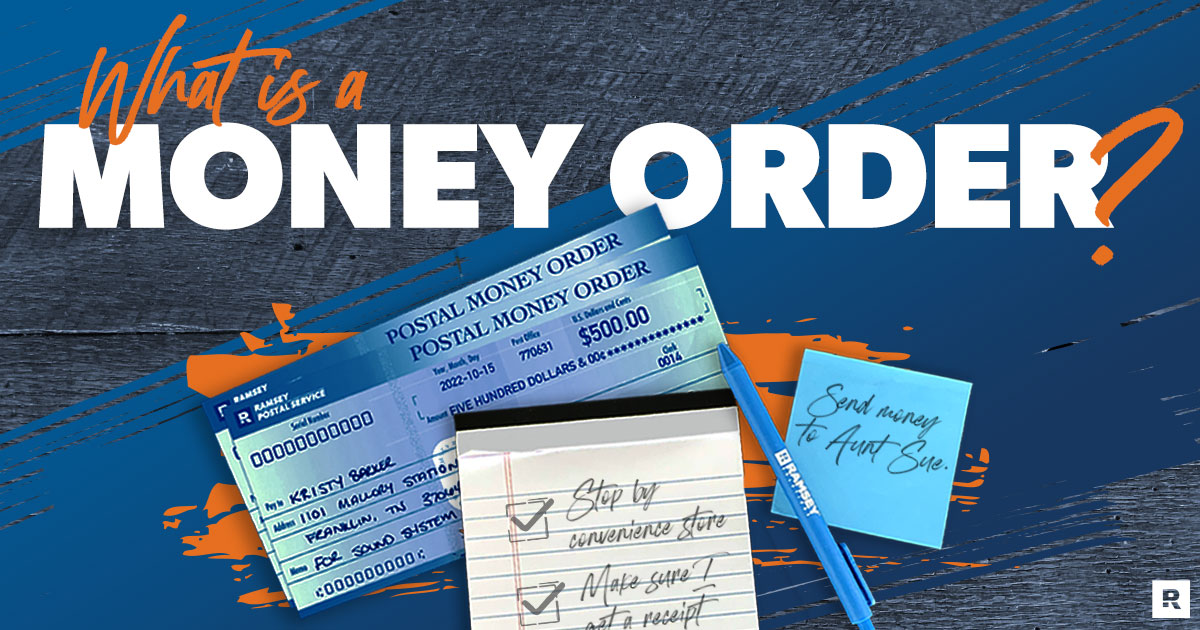
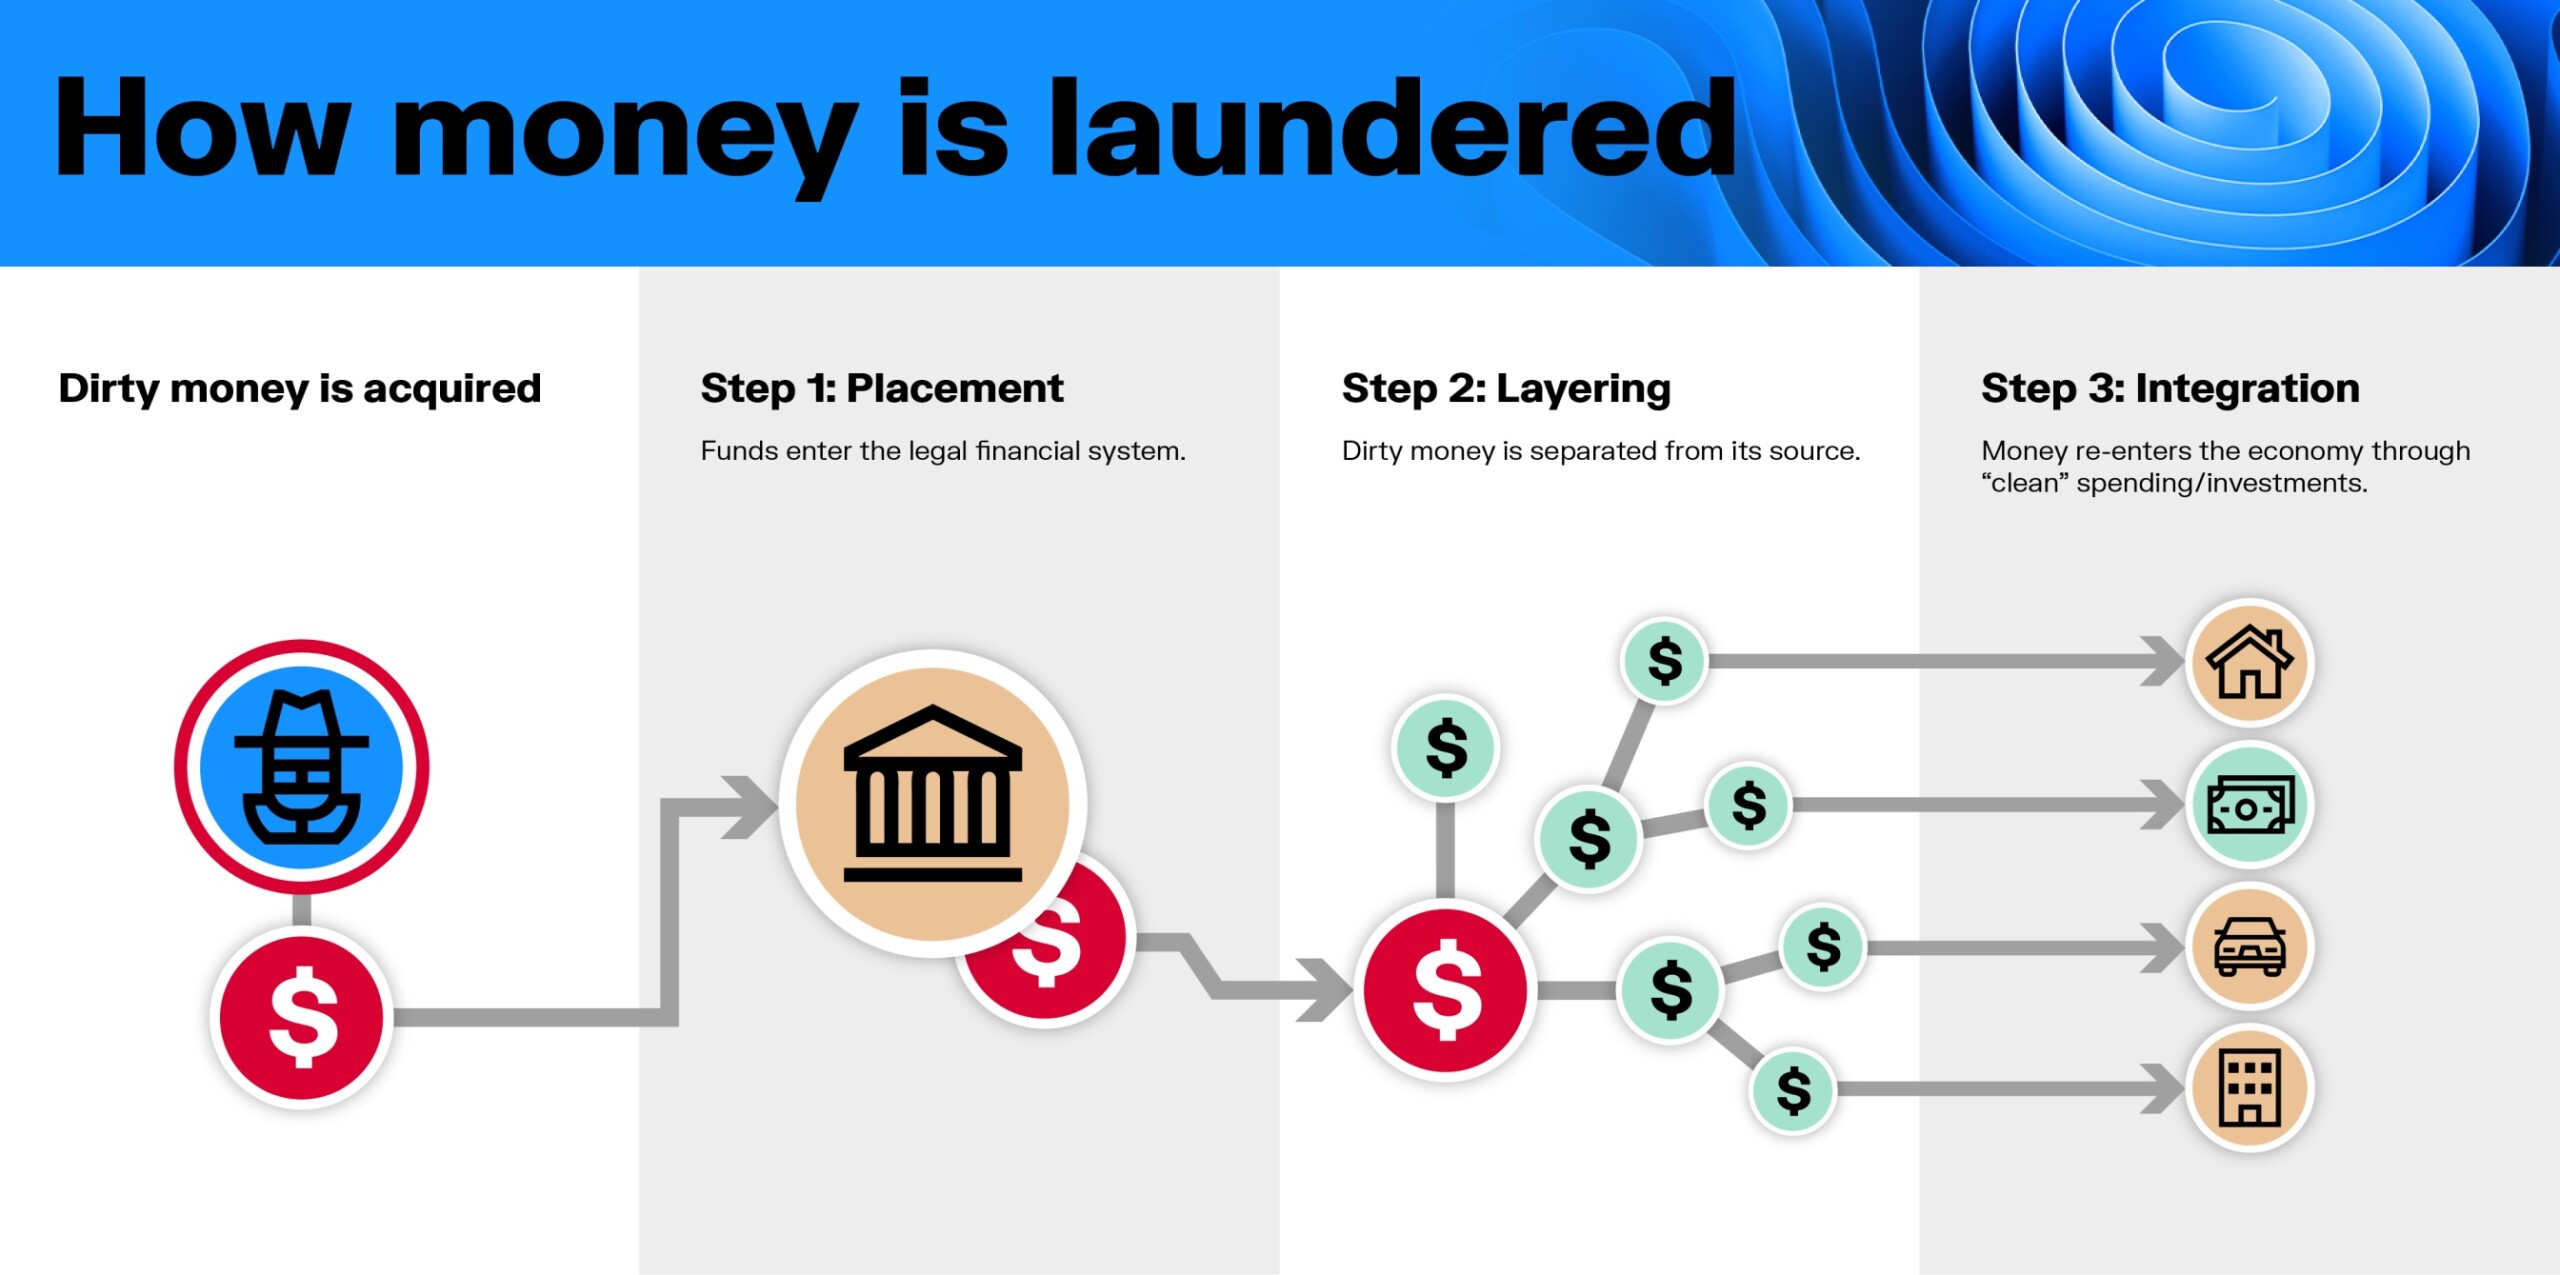
Money orders are a form of payment where the sender purchases a document from a financial institution, such as a bank or a store, that acts as a substitute for cash. The recipient can then exchange this document for the specified amount of money. Money laundering, on the other hand, is the process of making illegally obtained money (dirty money) appear legal (clean).
How Money Orders Facilitate Money Laundering
Money orders can be used in money laundering schemes due to their anonymity and ease of use. Here are a few ways this is done:
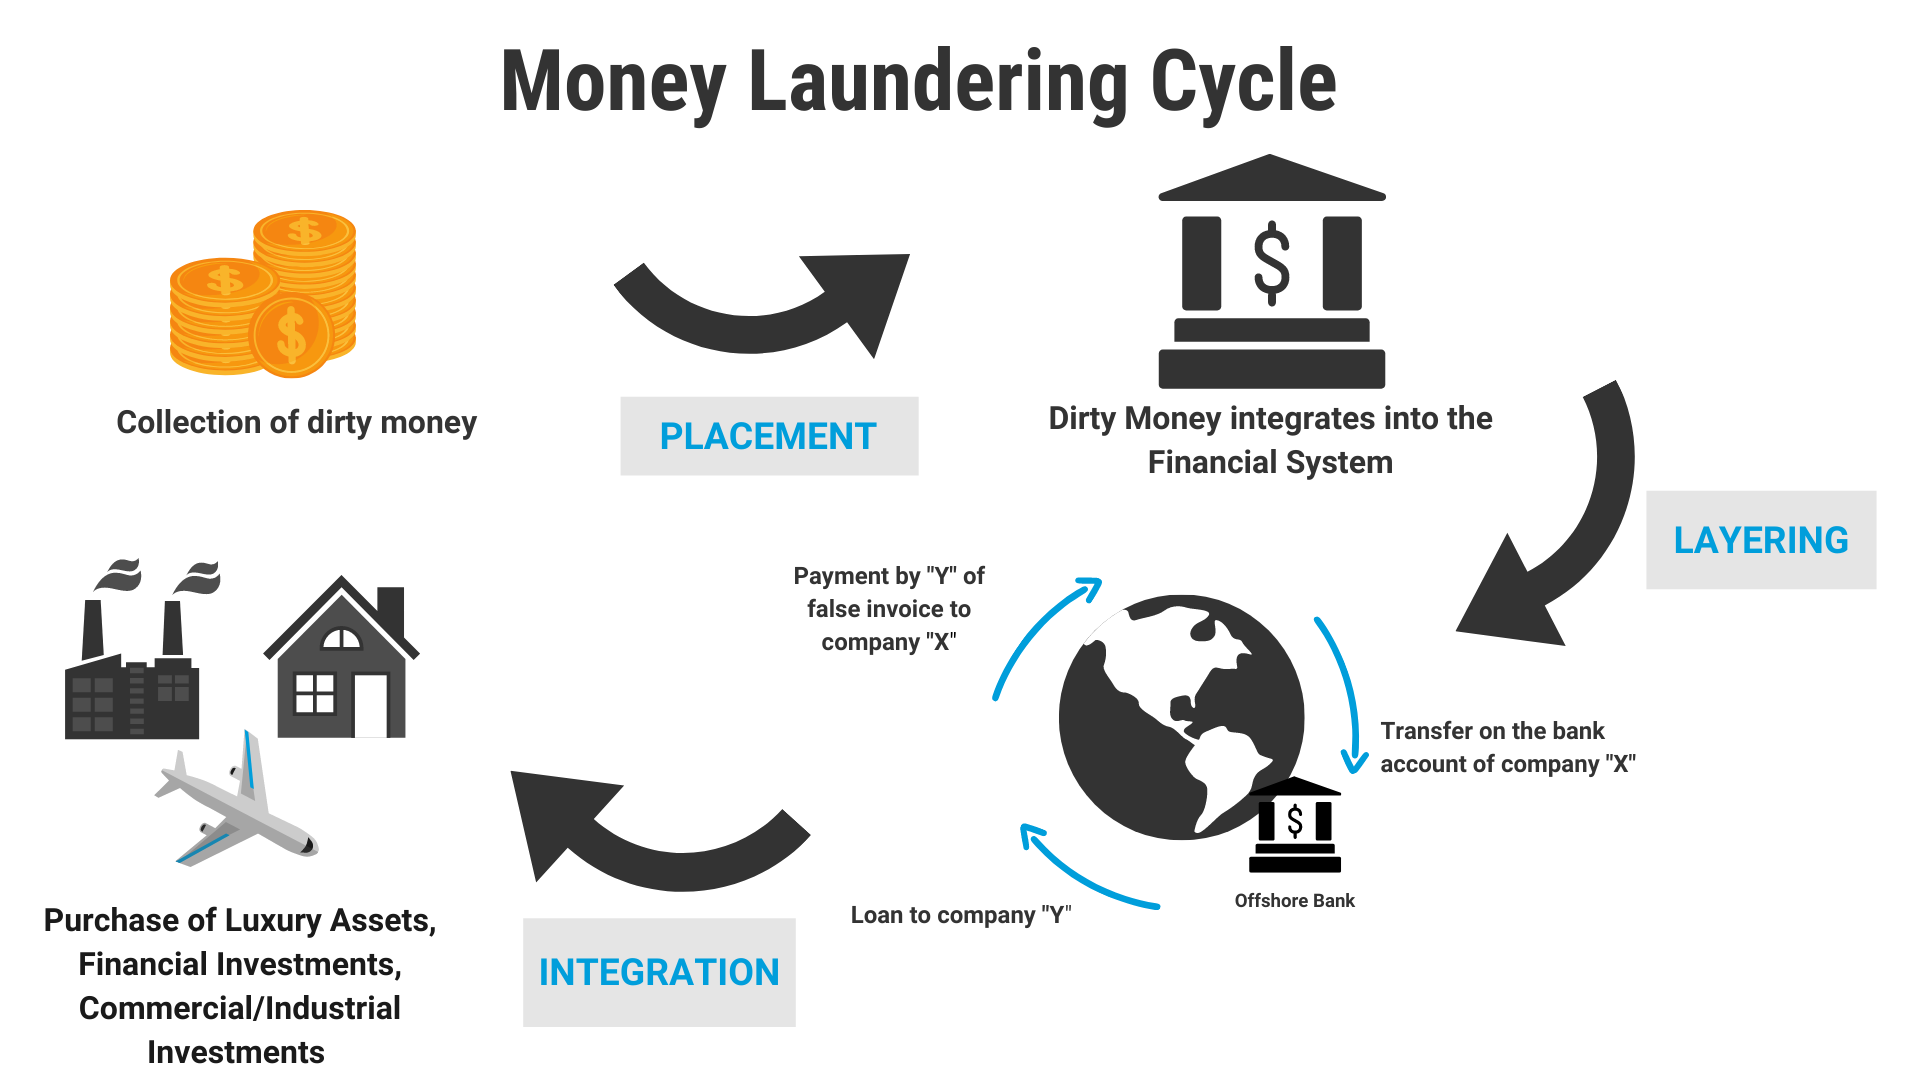
- Structuring: Launderers break down large amounts of illicit money into smaller transactions, often using money orders, to avoid detection.
- Trade-Based Laundering: Launderers use money orders in international trade transactions to disguise the origin of funds.
- Cash-Out: Launderers use money orders to convert illicit funds into legitimate currency.
Risks and Red Flags
Money order money laundering poses several risks, including:
- Damage to a financial institution's reputation if associated with money laundering activities.
- Legal and financial penalties for non-compliance with anti-money laundering (AML) regulations.
- Potential involvement in other criminal activities, such as fraud or drug trafficking.
Some red flags that may indicate money order money laundering include:
- Frequent, large money order transactions from a single customer.
- Money orders purchased with cash, especially in large amounts.
- Money orders sent to or received from high-risk locations or individuals.
Regulations and Prevention Measures
To combat money order money laundering, several regulations and prevention measures are in place:
| Regulation/Measure | Description |
|---|---|
| Bank Secrecy Act (BSA) | Requires financial institutions to report certain money order transactions and maintain records to prevent money laundering. |
| Customer Identification Program (CIP) | Requires financial institutions to verify the identity of money order customers. |
| Suspicious Activity Reporting (SAR) | Requires financial institutions to report suspicious money order transactions to the Financial Crimes Enforcement Network (FinCEN). |
Financial institutions also employ internal controls, such as transaction monitoring and staff training, to prevent and detect money order money laundering.
Role of Law Enforcement and Collaboration
Law enforcement agencies play a crucial role in investigating and prosecuting money order money laundering cases. Collaboration between financial institutions, law enforcement, and other stakeholders is essential to effectively combat this type of financial crime.