Maximizing Your Investment: Rules for Using 529 Funds
529 plans are a popular and powerful tool for saving and investing for future education expenses. They offer tax advantages and flexibility, but like any financial instrument, they come with rules and guidelines. Understanding these rules is key to making the most of your 529 fund. Let's dive into the key aspects you need to know.
Understanding the Basics of 529 Funds
Before we delve into the rules, let's ensure we're on the same page regarding what 529 funds are. These are tax-advantaged investment vehicles designed to encourage saving for future education expenses. They are named after Section 529 of the Internal Revenue Code. There are two types: prepaid tuition plans and education savings plans. The latter is more common and allows you to invest in mutual funds.
Contribution Limits and Gift Taxes
One of the first rules to understand is the contribution limit. The annual contribution limit for 529 plans is $15,000 per year, per beneficiary, or $30,000 for married couples filing jointly. However, these contributions are considered gifts for tax purposes, and you can elect to treat them as if they were made over a five-year period to avoid gift taxes.
For instance, if you contribute $75,000 in one year, you would file a gift tax return treating it as if you had made contributions of $15,000 for five years. This allows you to take advantage of the annual gift tax exclusion ($15,000 in 2021) without incurring gift taxes.
Tax Advantages and Withdrawals
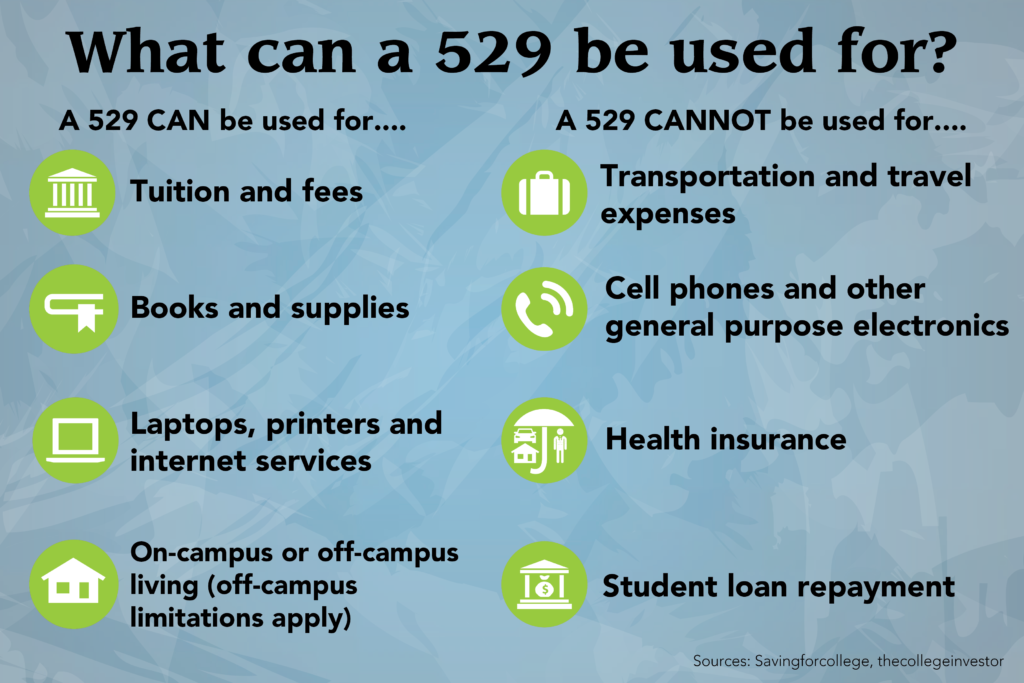
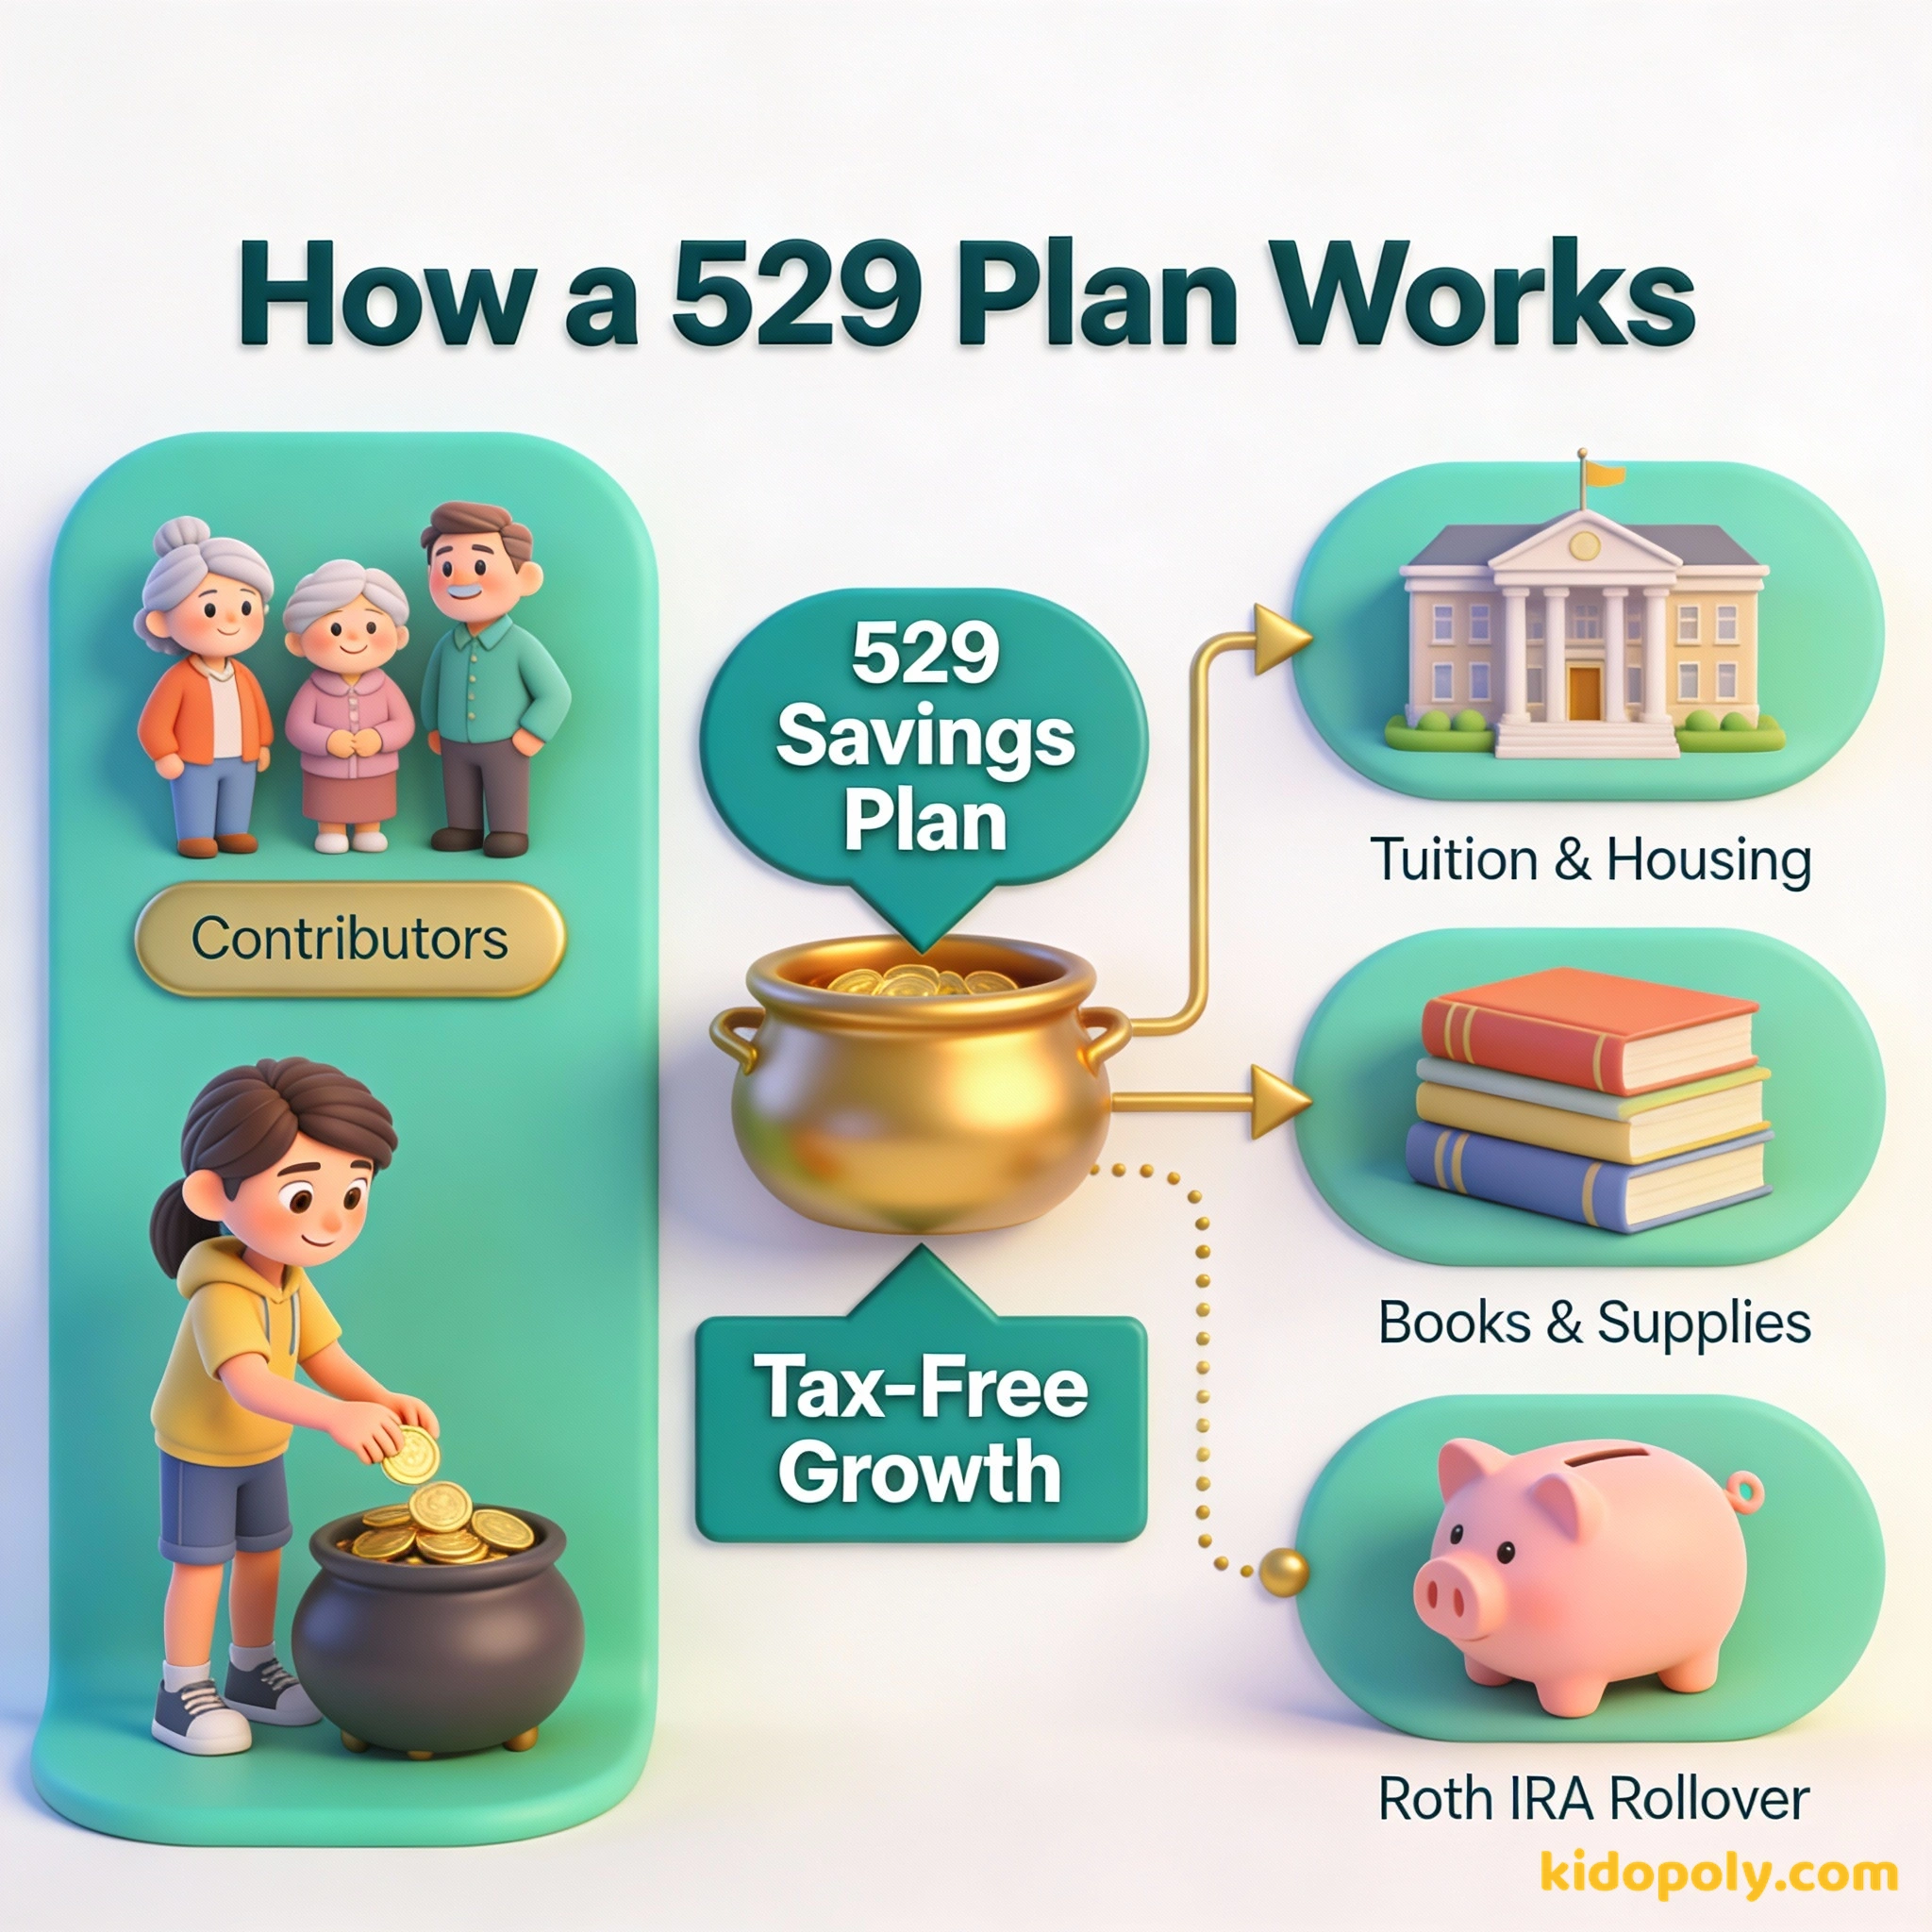
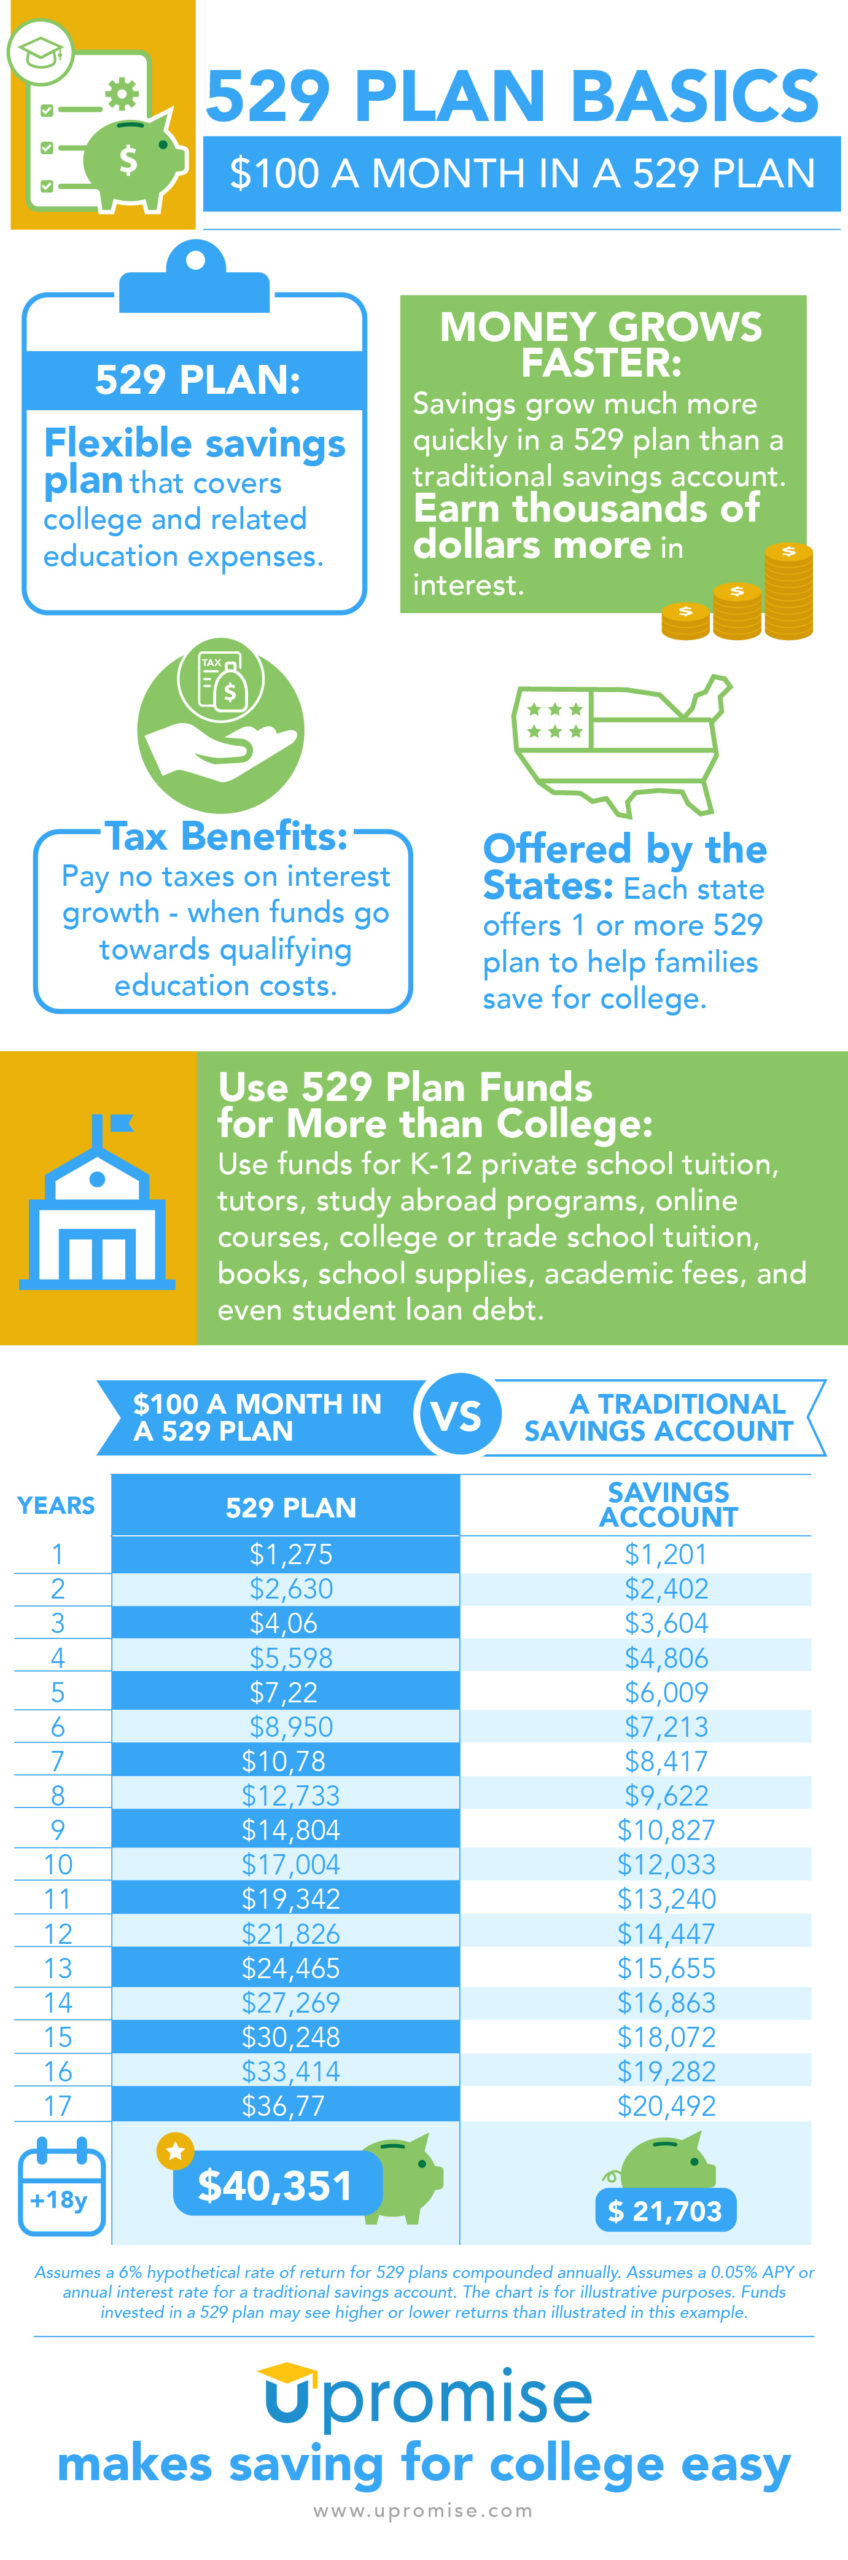
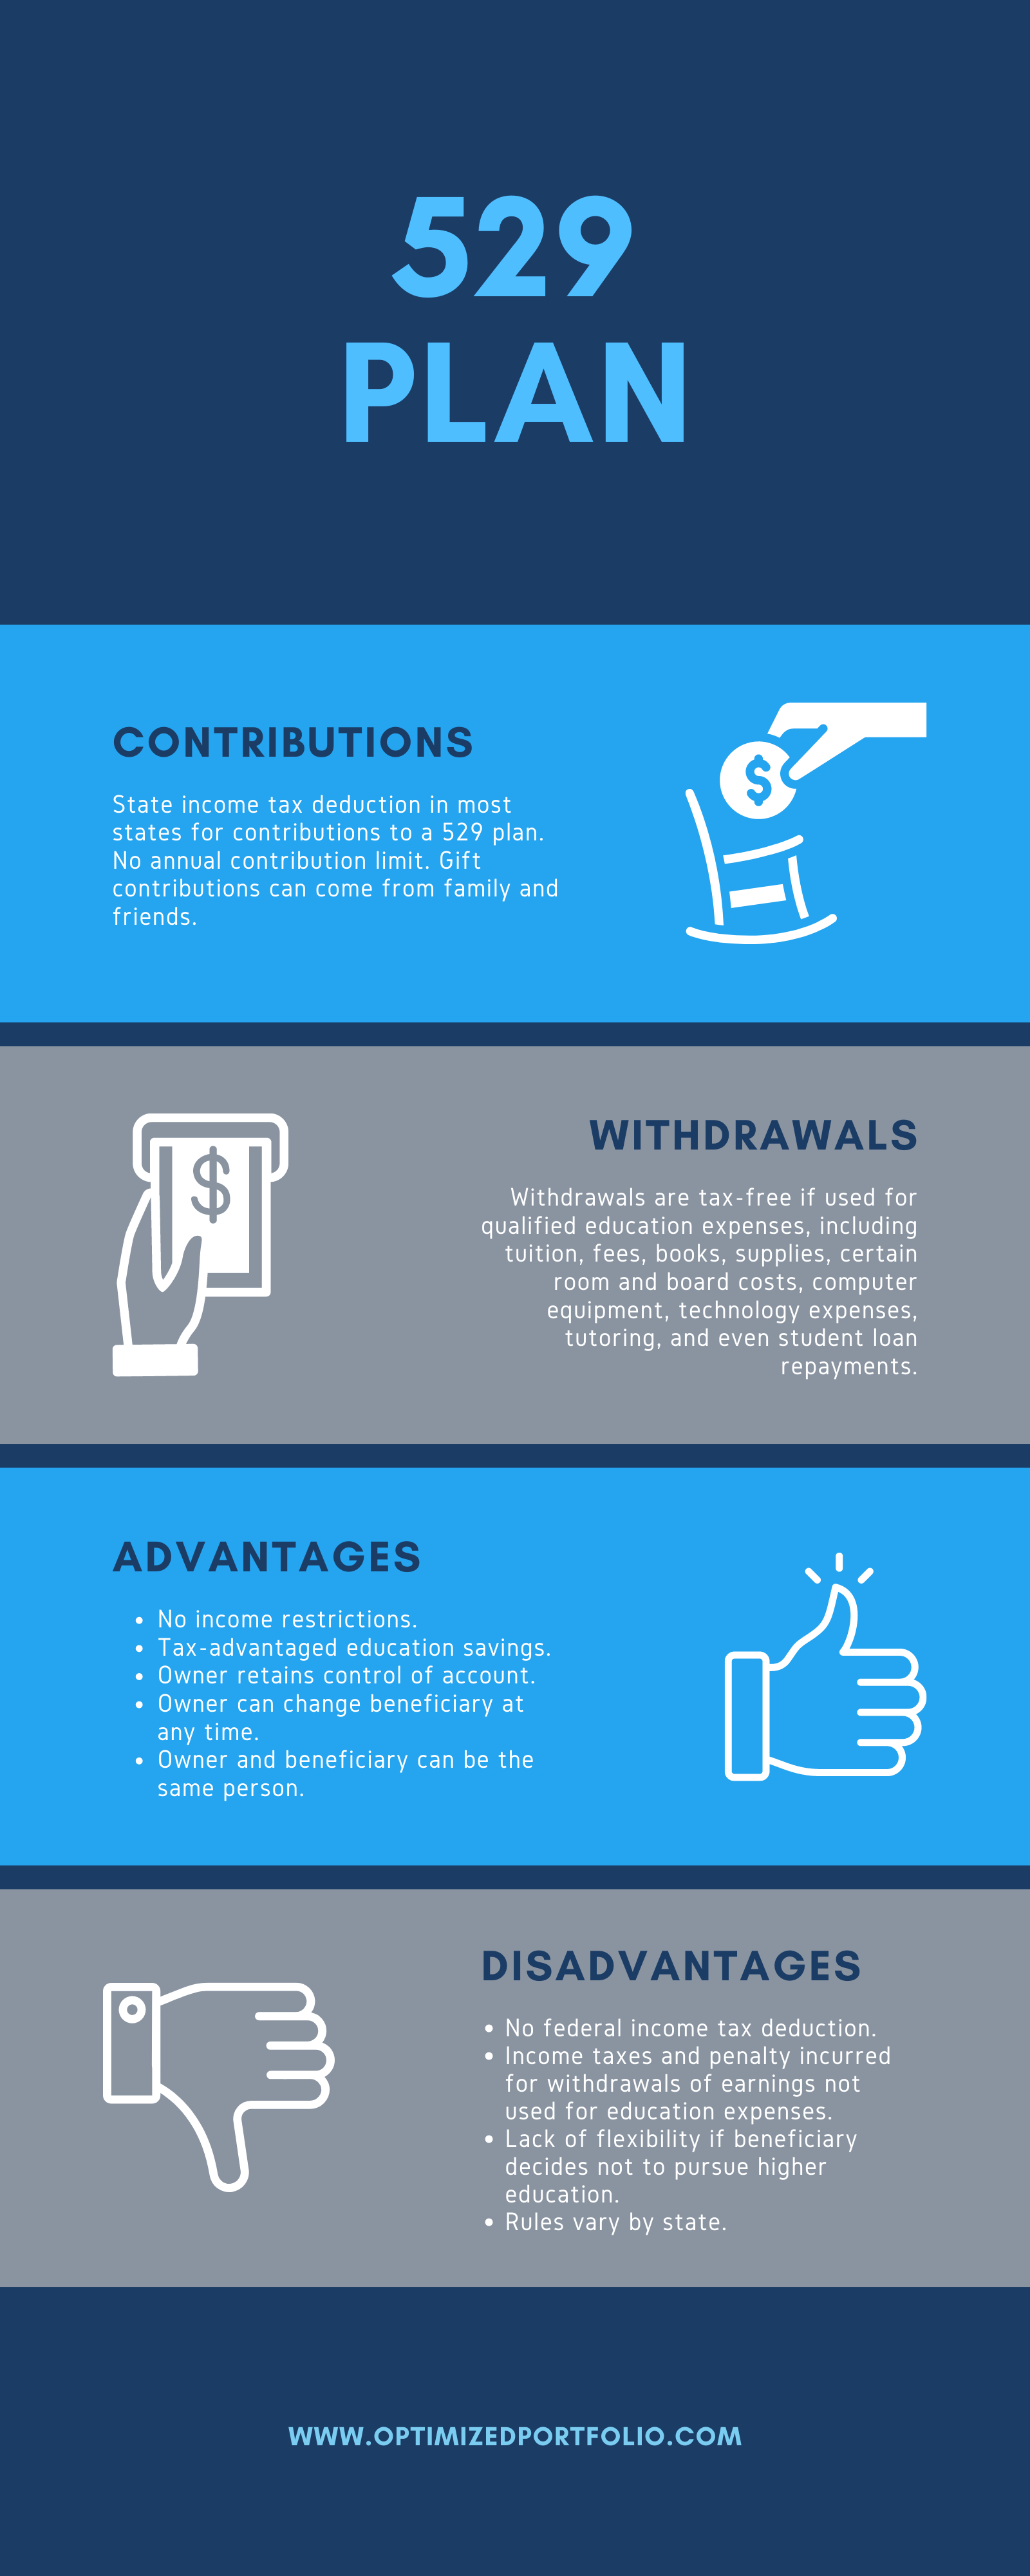
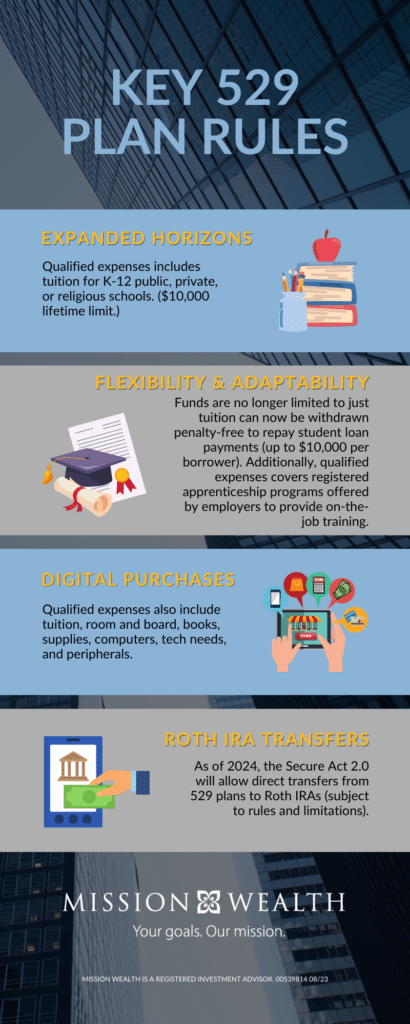
One of the primary benefits of 529 plans is their tax advantages. Contributions grow tax-deferred, and withdrawals are tax-free when used for qualified education expenses. However, it's crucial to understand what qualifies as a "qualified expense." This includes tuition, fees, books, supplies, and equipment required for enrollment or attendance at an eligible educational institution.
Withdrawals for non-qualified expenses are subject to income tax and a 10% penalty on the earnings. However, there are a few exceptions to this penalty, such as using the funds for a beneficiary with a disability or for registered apprenticeship programs.

Changing the Beneficiary: Rules and Considerations
One of the flexibilities of 529 plans is the ability to change the beneficiary. You can typically change the beneficiary to another qualifying family member without incurring taxes or penalties. However, you should be aware of a few rules:
- The new beneficiary must be under the age of 30 at the time of the change.
- The new beneficiary must be a member of the original beneficiary's family (as defined by the IRS).
- If the new beneficiary is not in the same generation as the original beneficiary, a gift tax may apply.
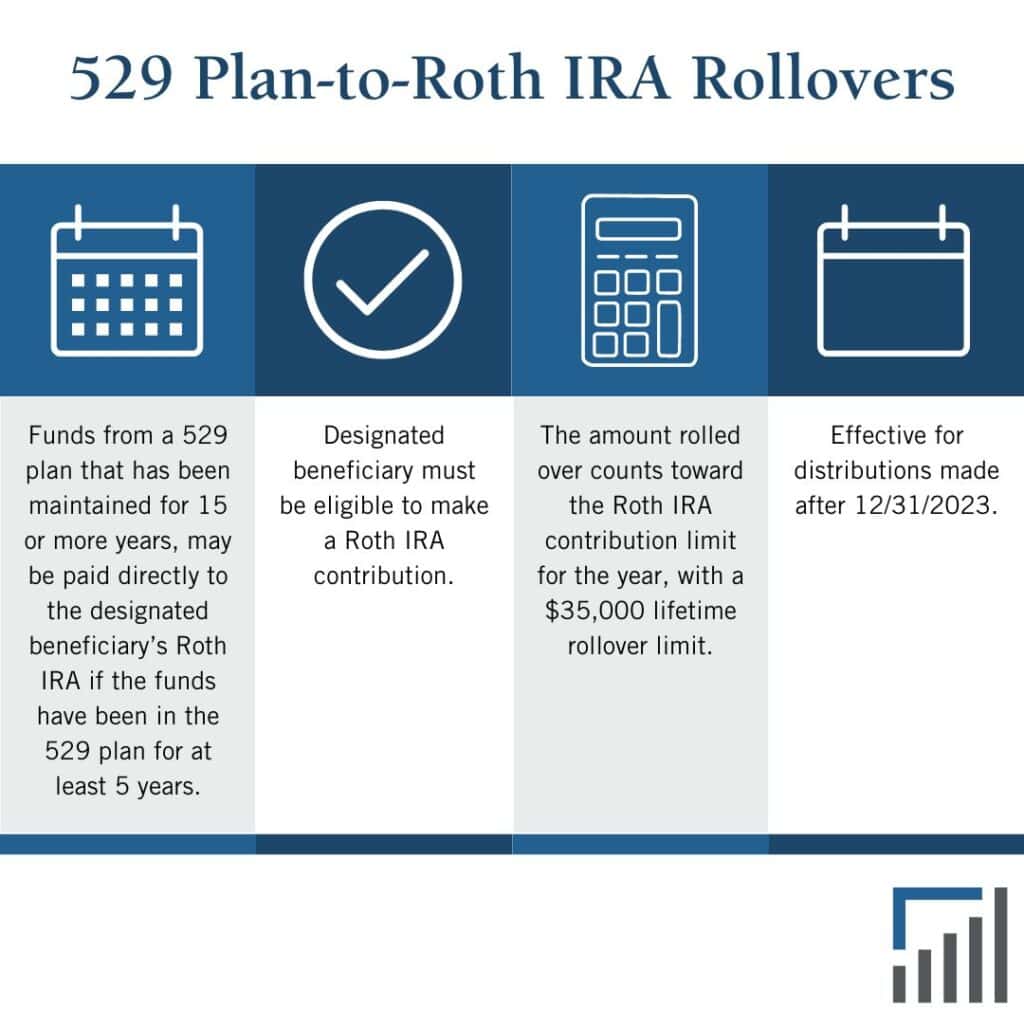
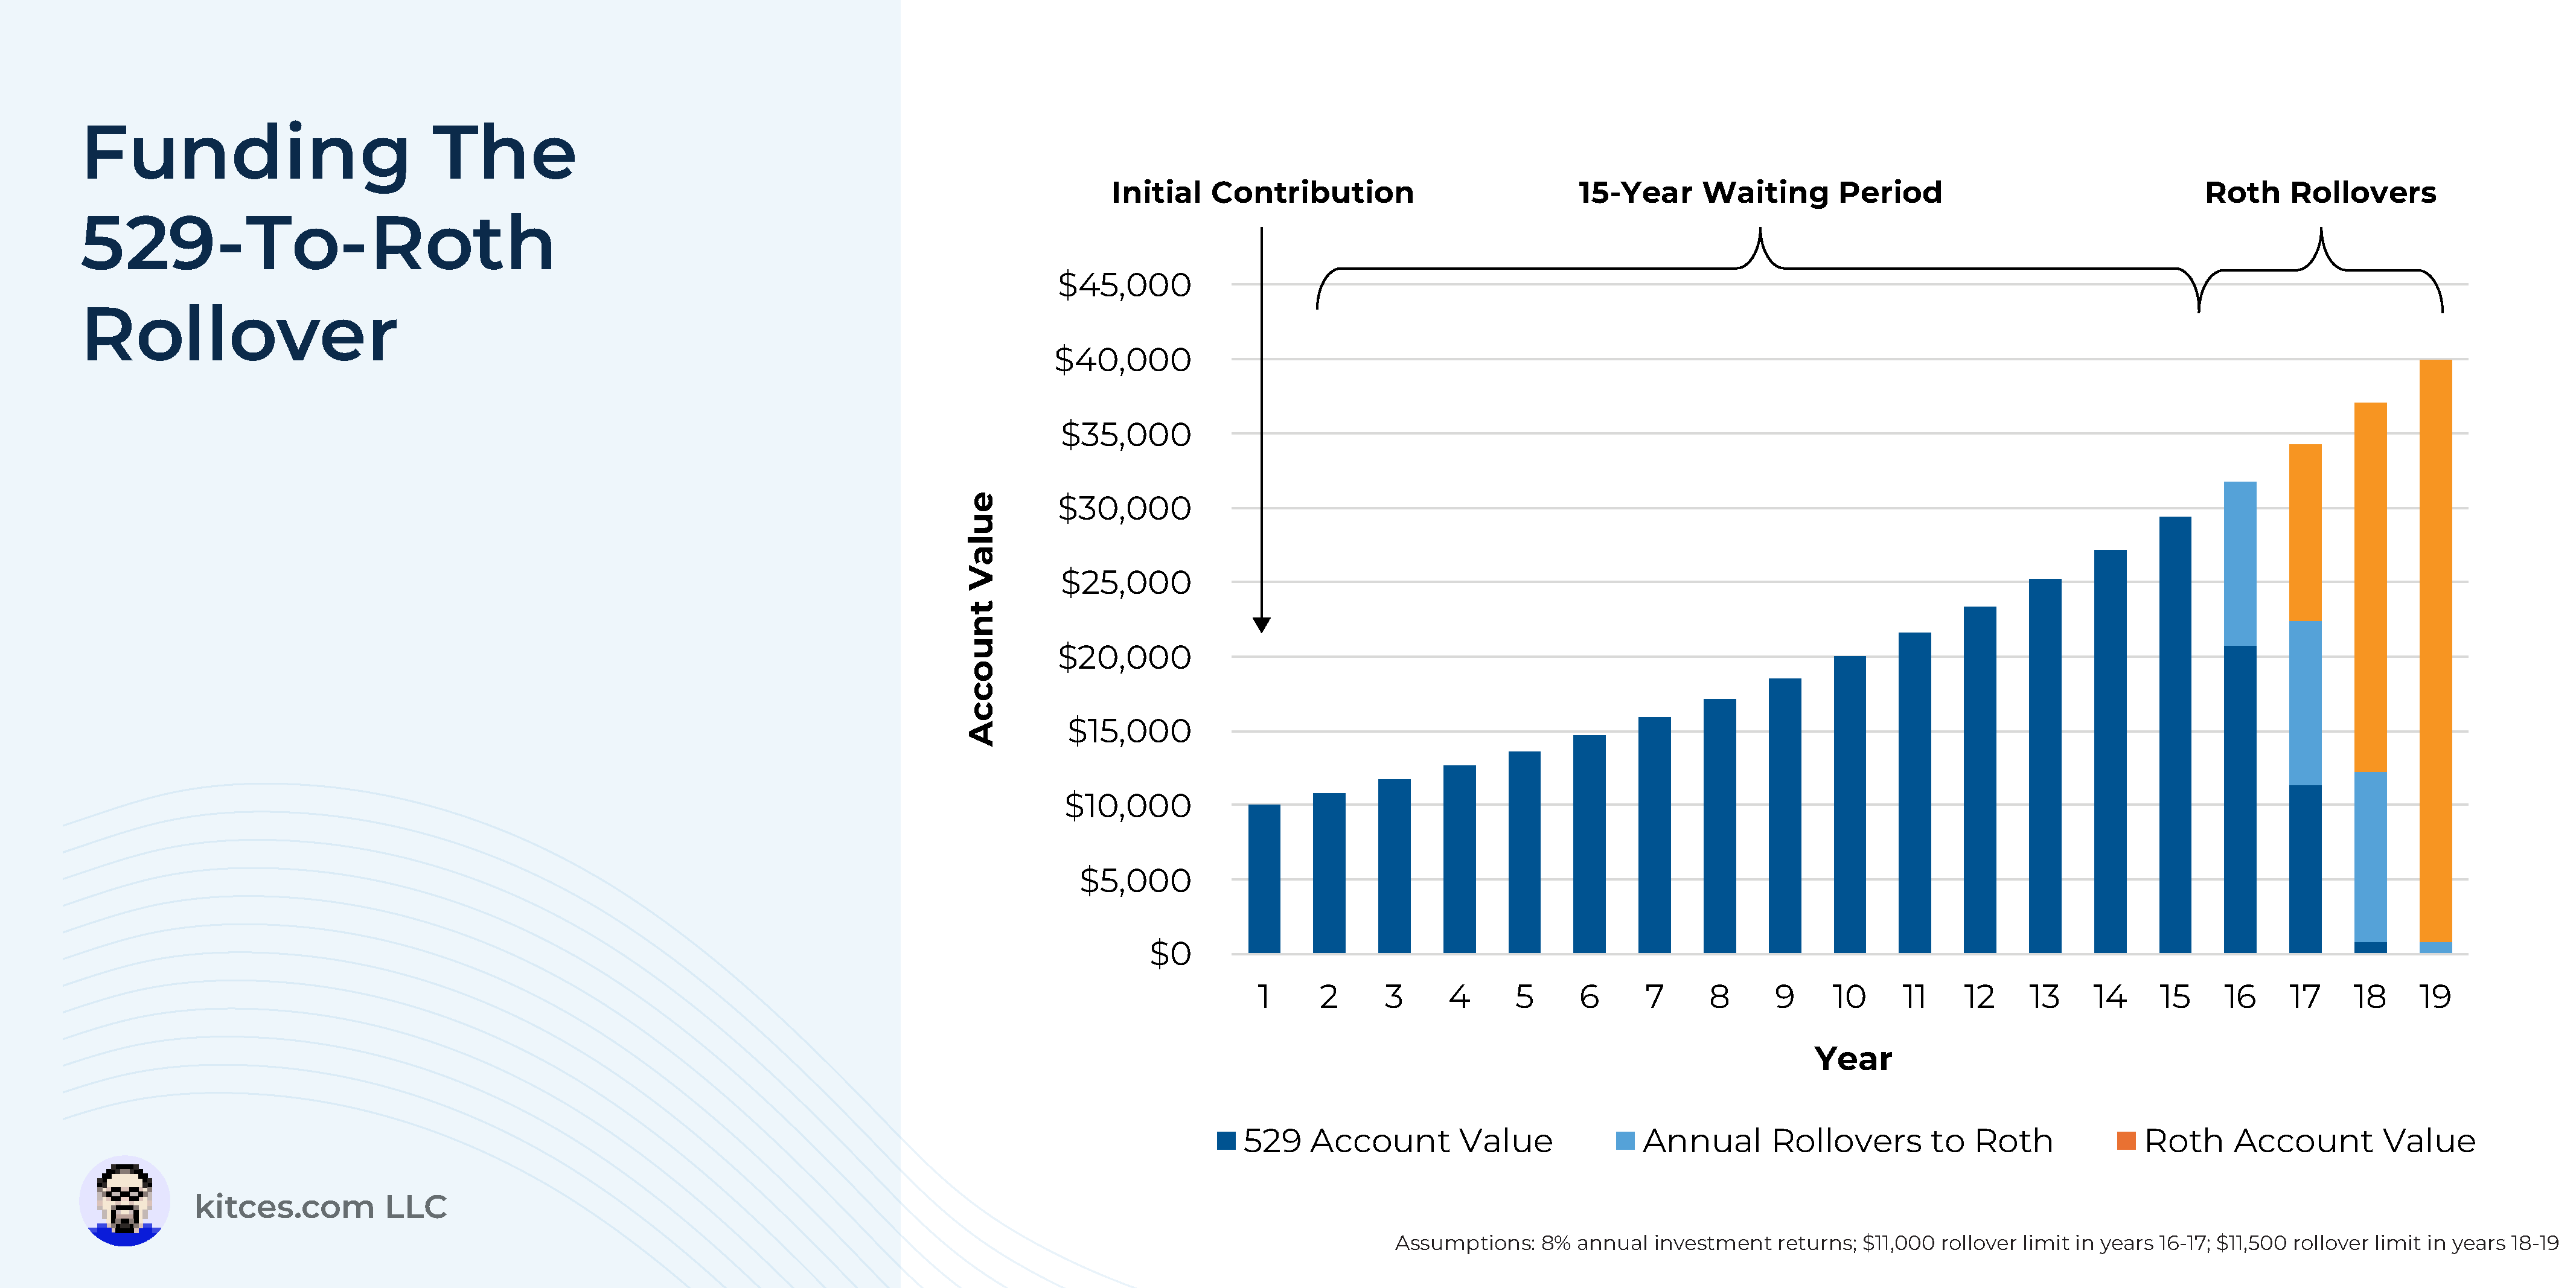
Rolling Over Funds: When and How
Another rule to be aware of is the ability to roll over funds from one 529 plan to another. This can be a useful strategy if you're not satisfied with the investment options or performance of your current plan. However, there are a few rules to keep in mind:
- You can only roll over funds once per year for the same beneficiary.
- The contribution limit still applies to rollovers. For example, if you rolled over $10,000 in one year, you could only contribute an additional $5,000 for that year.
- If the new plan is owned by a non-parent, a gift tax may apply.
Consulting a Financial Advisor
Given the complexity of these rules and the potential tax implications, it's always a good idea to consult with a financial advisor when using 529 funds. They can provide personalized advice based on your unique financial situation and help you make the most of your investment.
In conclusion, understanding the rules for using 529 funds is key to maximizing your investment and ensuring that you're taking full advantage of the tax benefits. By familiarizing yourself with the contribution limits, tax advantages, beneficiary changes, and rollover rules, you can make informed decisions about your education savings.