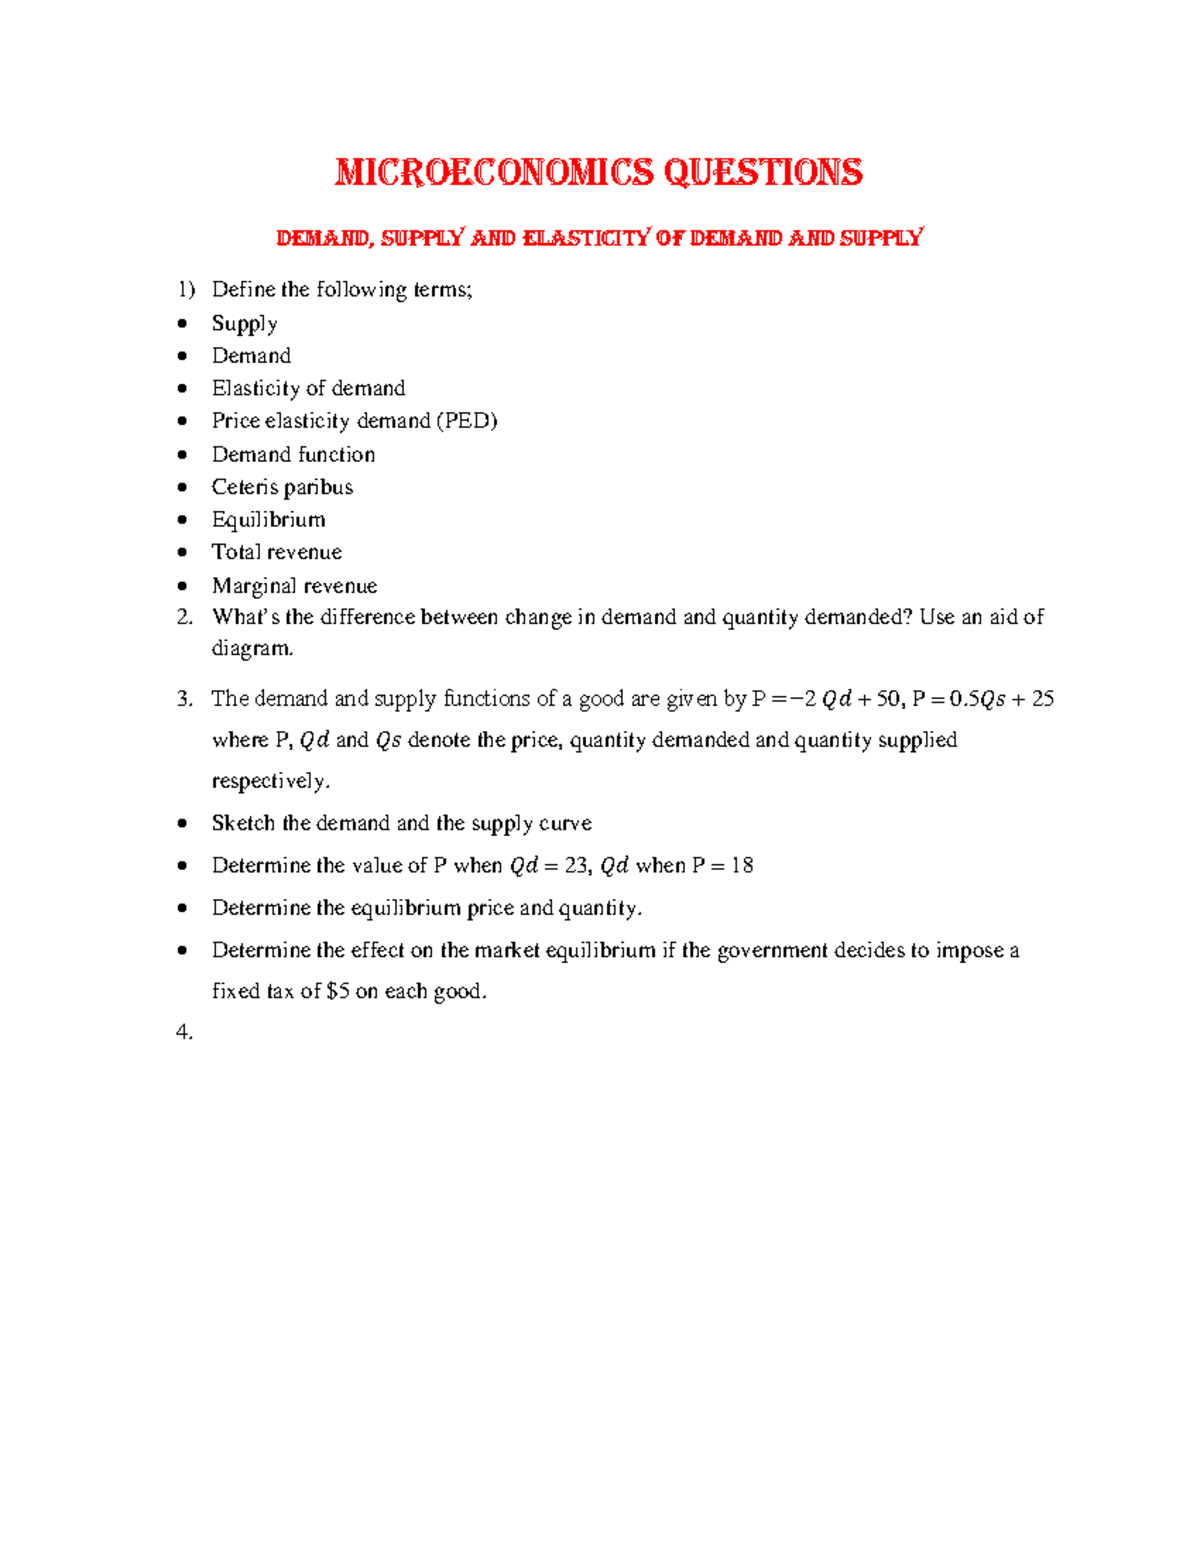
The interplay of supply and demand is a fundamental concept in microeconomics, governing the price and quantity of goods and services in a market. This article delves into the core questions surrounding supply and demand, their impact on market equilibrium, and the factors that shift these curves.
Understanding Supply and Demand
Supply and demand are the two primary forces that determine the price and allocation of resources in an economy. The law of supply states that, all else being equal, as the price of a good increases, the quantity supplied increases, and vice versa. Conversely, the law of demand posits that, all else being equal, as the price of a good increases, the quantity demanded decreases, and vice versa.
Key Questions in Supply and Demand
Several questions arise when studying supply and demand in microeconomics:

- What happens to the equilibrium price and quantity when the supply curve shifts?
- How do changes in demand affect the market equilibrium?
- What factors cause shifts in the supply and demand curves?
- How do taxes and subsidies impact the market equilibrium?
- What is the concept of consumer surplus and producer surplus, and how are they affected by changes in supply and demand?
Shifts in Supply and Demand Curves
Shifts in the supply and demand curves occur due to changes in factors other than price. For instance, an increase in the cost of production can shift the supply curve to the left (decreasing supply), while a discovery of new oil reserves can shift the supply curve to the right (increasing supply). Similarly, changes in consumer preferences or income can shift the demand curve.
Market Equilibrium and Surpluses
The market equilibrium is the point where the supply and demand curves intersect, representing the price and quantity where the market clears (i.e., the quantity supplied equals the quantity demanded). Changes in supply and demand can lead to surpluses (excess supply) or shortages (excess demand). Consumer surplus is the difference between what consumers are willing to pay and what they actually pay, while producer surplus is the difference between what producers receive and their cost of production.
Policies and Market Interventions
Governments often intervene in markets to influence the price and quantity of goods and services. Taxes, for example, can shift the supply curve to the left, increasing the price and decreasing the quantity supplied. Subsidies, on the other hand, shift the supply curve to the right, decreasing the price and increasing the quantity supplied. Understanding these shifts and their impacts is crucial for designing effective economic policies.

In conclusion, the study of supply and demand in microeconomics is essential for understanding how markets function and how they respond to changes in various factors. By exploring these questions, we can gain insights into the dynamics of markets and the impacts of economic policies.