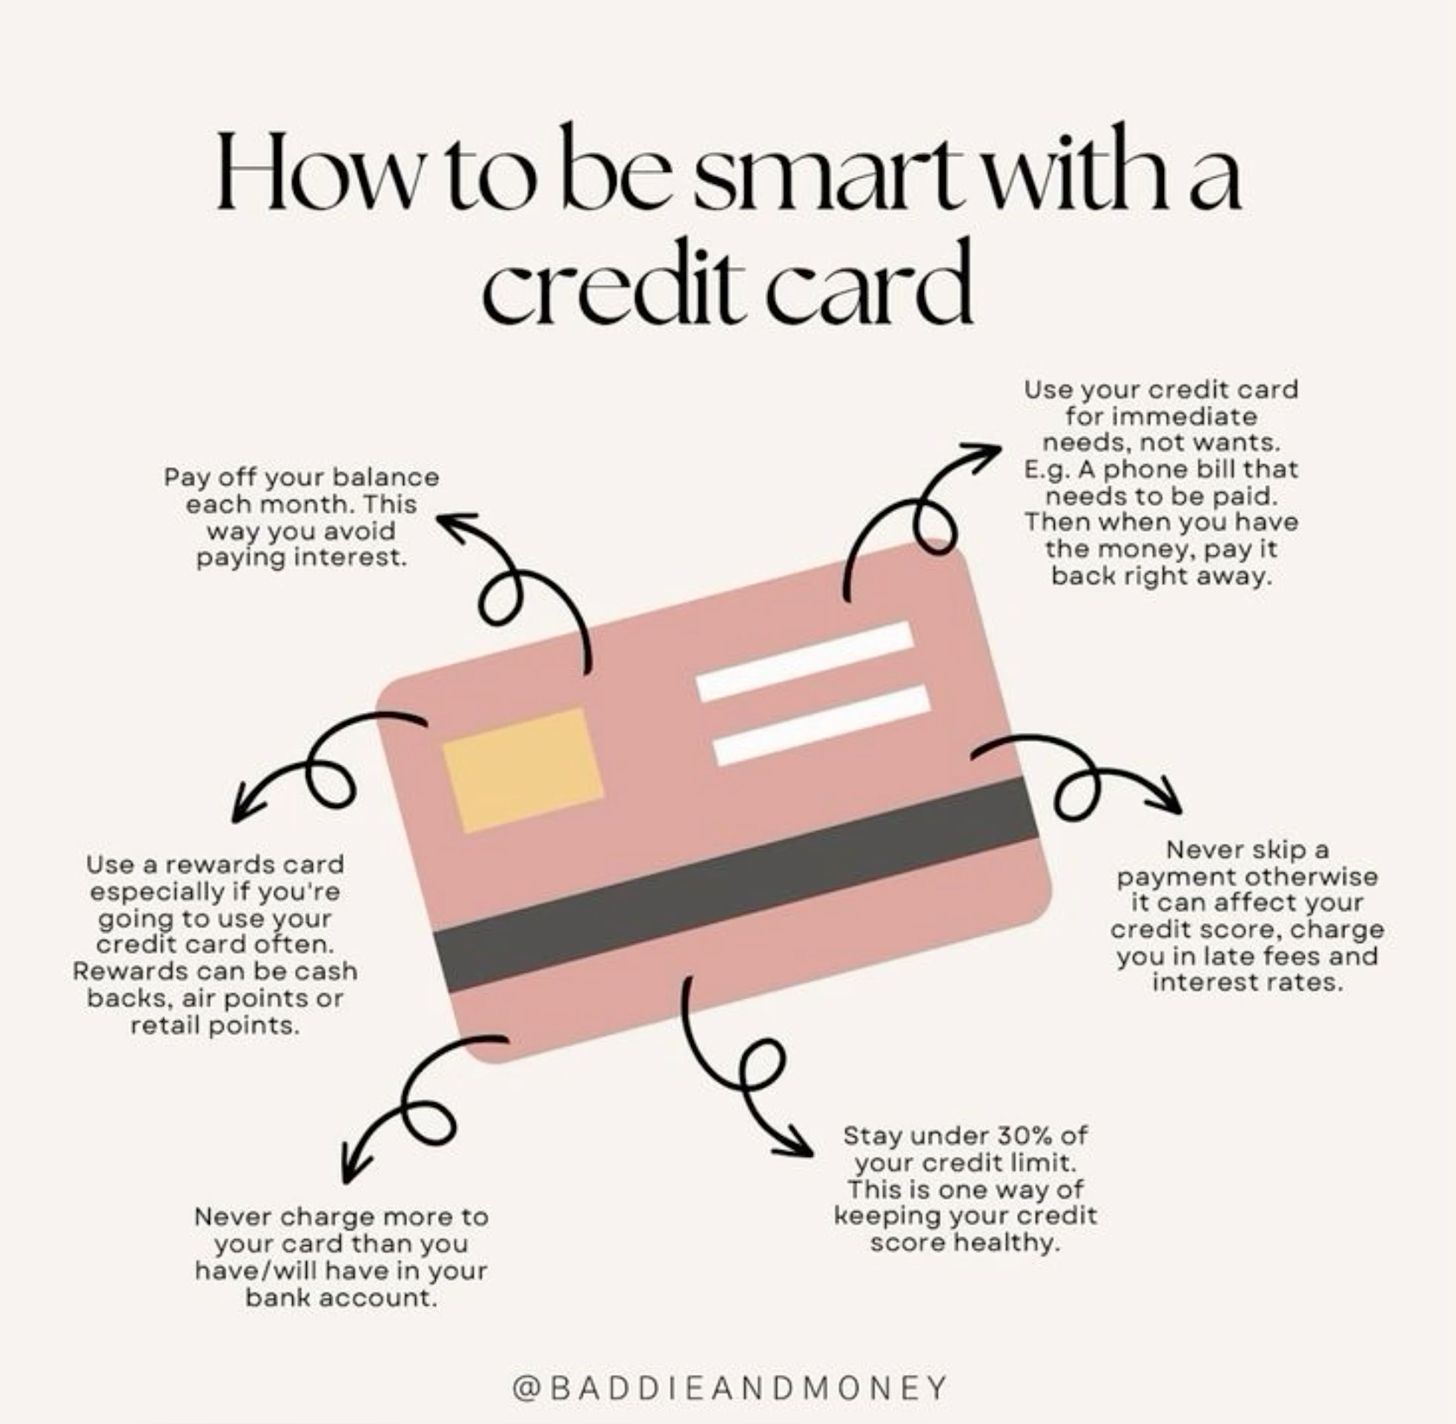
At its core, a general purpose credit card is an open-loop payment instrument issued by a bank or financial institution that provides a line of revolving credit. Unlike store cards or restricted-use cards, this type of plastic is designed for widespread acceptance, allowing cardholders to make purchases at a vast array of merchants, both in physical locations and online. The fundamental appeal lies in its flexibility, offering a convenient method to manage cash flow, cover unexpected expenses, or finance larger purchases over time while enjoying the inherent security and fraud protection provided by the network.
The Mechanics of Credit: How It Functions
Understanding the operational framework of a general purpose credit card requires looking beyond the simple act of swiping. When a transaction occurs, the card network—such as Visa, Mastercard, or Discover—facilitates the transfer of funds between the merchant’s bank and the issuing bank. The cardholder is essentially borrowing money from the issuer to pay the merchant. At the end of the billing cycle, the cardholder receives a statement outlining the transactions, the current balance, and the minimum amount due. This structure creates a revolving line of credit, meaning as the borrower repays the debt, the credit becomes available for use again.
Key Features and Benefits
The value of a general purpose credit card extends beyond mere convenience, encompassing a suite of features designed to enhance the consumer experience. These cards typically come with robust fraud protection, meaning cardholders are generally not liable for unauthorized transactions. Additionally, many issuers offer reward programs, such as cash back, points, or travel miles, which provide tangible value for everyday spending. The universal acceptance of these cards makes them indispensable tools for travel and emergency situations, offering a financial safety net that pure debit cards cannot match.

Rewards and Incentives
Modern general purpose cards are highly competitive products, often differentiated by their rewards structures. Cardholders can earn returns on their spending across diverse categories, including groceries, dining, gas, and travel. These rewards can significantly offset the cost of card usage over time. However, it is crucial to manage rewards earning strategically to ensure the value gained outweighs any potential interest charges if the balance is not paid in full monthly.
Financial Considerations and Responsibility
While the benefits are substantial, the responsible use of a general purpose credit card is paramount to maintaining financial health. The primary pitfall to avoid is carrying a balance from month to month, which triggers interest charges that can quickly erode the value of rewards. Cardholders should view their credit limit not as extra income, but as a tool to be managed wisely. Establishing a budget and adhering to it ensures that credit serves as a financial asset rather than a liability, protecting one’s credit score and long-term stability.
Impact on Credit Score
Because these cards are widely used and heavily reported to credit bureaus, they play a significant role in building a credit history. Payment history—the record of on-time or late payments—is the most influential factor in credit scoring models. Furthermore, the credit utilization ratio, which compares the balance to the credit limit, is a major metric. Responsible management, characterized by low utilization and consistent payments, signals reliability to lenders and can lead to better terms on future financial products, such as mortgages or auto loans.

Comparison to Alternative Payment Methods
To fully appreciate the role of a general purpose credit card, it is helpful to compare it to other common payment forms. Unlike debit cards, which draw directly from existing bank funds, credit cards offer a layer of separation that protects bank accounts from fraud. While debit cards often lack substantial rewards, general purpose cards are built around maximizing value. Furthermore, these cards provide superior purchase protection and extended warranties, benefits rarely found with debit or cash transactions, making them the superior choice for significant purchases.
Physical vs. Digital Wallets
The evolution of payment technology has integrated general purpose credit cards into digital ecosystems. Cardholders can now add their physical cards to mobile wallets like Apple Pay, Google Pay, and Samsung Pay. This digitization enhances security through tokenization, replacing sensitive card numbers with unique device account numbers. It also streamlines the checkout process, offering the flexibility of contactless payments in stores and one-click purchasing online, thereby preserving the relevance and utility of the traditional credit card in a cashless society.