"Navigating NQP Plan Distributions: Tax Treatment Explained"
When it comes to retirement planning, most people are familiar with qualified pension plans—those governed by ERISA and offering tax-deferred growth and favorable distribution rules. But what happens when your employer offers a non-qualified pension plan? Understanding the tax treatment of distributions from these plans is critical to avoiding unexpected liabilities and maximizing your after-tax income in retirement.

What Is a Non-Qualified Pension Plan?

A non-qualified pension plan is a type of deferred compensation arrangement that does not meet the requirements of Section 401(a) of the Internal Revenue Code. Unlike qualified plans, these arrangements are typically offered to key executives or highly compensated employees and are not subject to the same contribution limits, vesting schedules, or fiduciary protections. Because they fall outside ERISA’s umbrella, their tax treatment upon distribution differs significantly.
Key Differences from Qualified Plans

- No upfront tax deduction: Employers cannot deduct contributions until the employee includes the benefit in taxable income.
- No tax-deferred growth: Earnings may be taxed as they accrue, depending on plan structure.
- Limited portability: Assets are generally not transferable and remain subject to employer insolvency risk.
Tax Treatment of Distributions
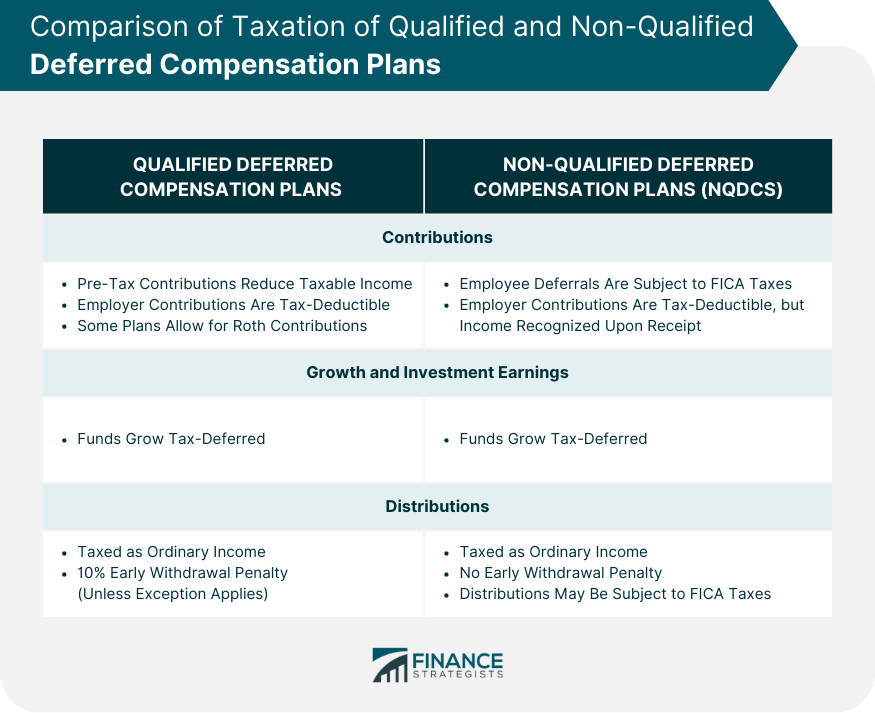
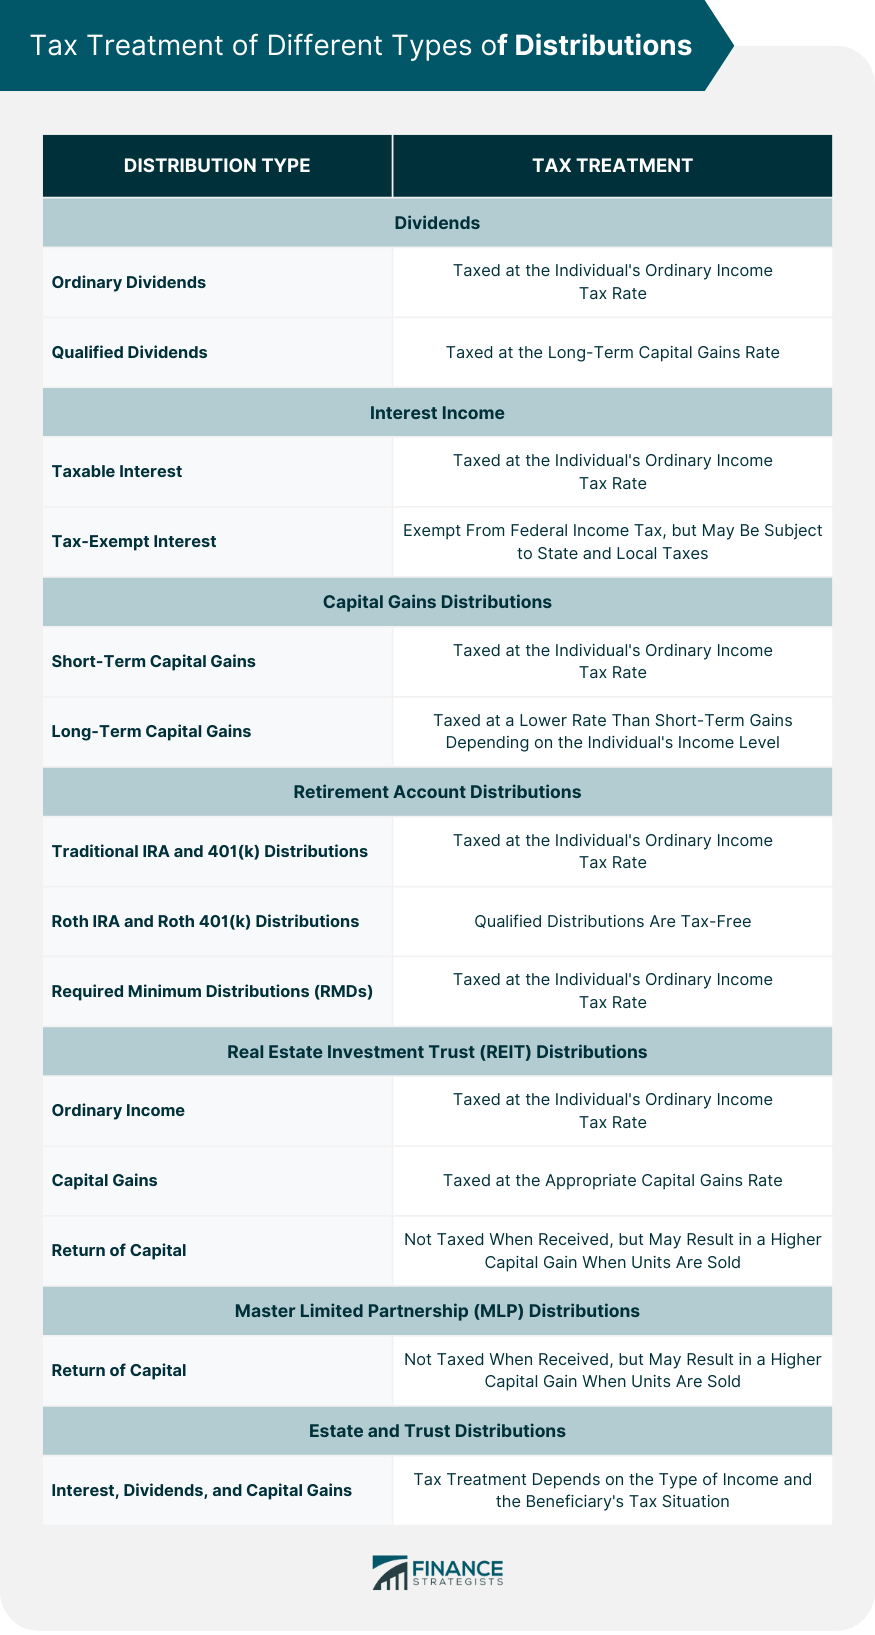
Distributions from non-qualified pension plans are generally included in the recipient’s gross income in the year they are received. The IRS treats these payments as ordinary income, meaning they are taxed at the individual’s marginal tax rate—there’s no capital gains treatment or special rates. If the plan was funded (i.e., assets were set aside in a trust or account), taxation may occur earlier under the “economic benefit” doctrine, even before actual receipt.
When Is Income Recognized?
Income recognition hinges on whether the plan is unfunded or funded. In an unfunded plan—where benefits are merely a promise by the employer—the employee recognizes income only upon actual or constructive receipt. In a funded plan, the IRS may require income inclusion when the benefit becomes substantially vested, regardless of distribution timing. This distinction is crucial for executives receiving large deferred bonuses or retirement incentives.

Reporting and Withholding Requirements
Employers must report non-qualified plan distributions on Form W-2 (for current employees) or Form 1099-NEC (for former employees or independent contractors). Federal income tax withholding applies at the supplemental wage rate—currently 22% for amounts up to $1 million, and 37% for amounts exceeding that threshold. State and local taxes may also apply depending on jurisdiction.
| Distribution Type | Taxable Event | Withholding Rate |
|---|---|---|
| Unfunded Plan | Upon receipt | 22%–37% |
| Funded Plan | At vesting or receipt | 22%–37% |

Penalties and Additional Considerations
Unlike qualified plans, non-qualified plans are not subject to the 10% early withdrawal penalty under Section 72(t). However, if the plan fails to comply with Section 409A of the Internal Revenue Code, all deferred amounts become immediately taxable—and an additional 20% penalty plus interest may apply. Proper plan design and timely reporting are essential to avoid these severe consequences.





Strategic Planning Tips
To minimize tax impact, consider coordinating distributions with other income sources, leveraging installment payouts, and ensuring strict adherence to 409A compliance. Consulting a tax advisor familiar with executive compensation structures is strongly recommended. While non-qualified plans offer flexibility, their tax complexity demands careful navigation.