Planning for retirement involves more than just setting aside a portion of your paycheck. Employer matching contributions play a massive role in growing your 401(k) balance over time. However, simply contributing isn't always enough to maximize those benefits. If your company offers a "true-up" provision, understanding how to calculate it can mean the difference between leaving free money on the table and fully leveraging your retirement plan.
What Is a 401(k) True-Up?
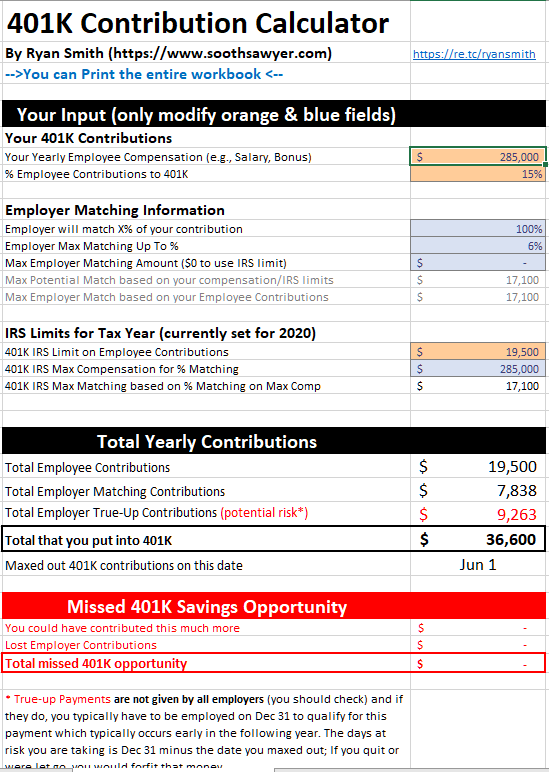
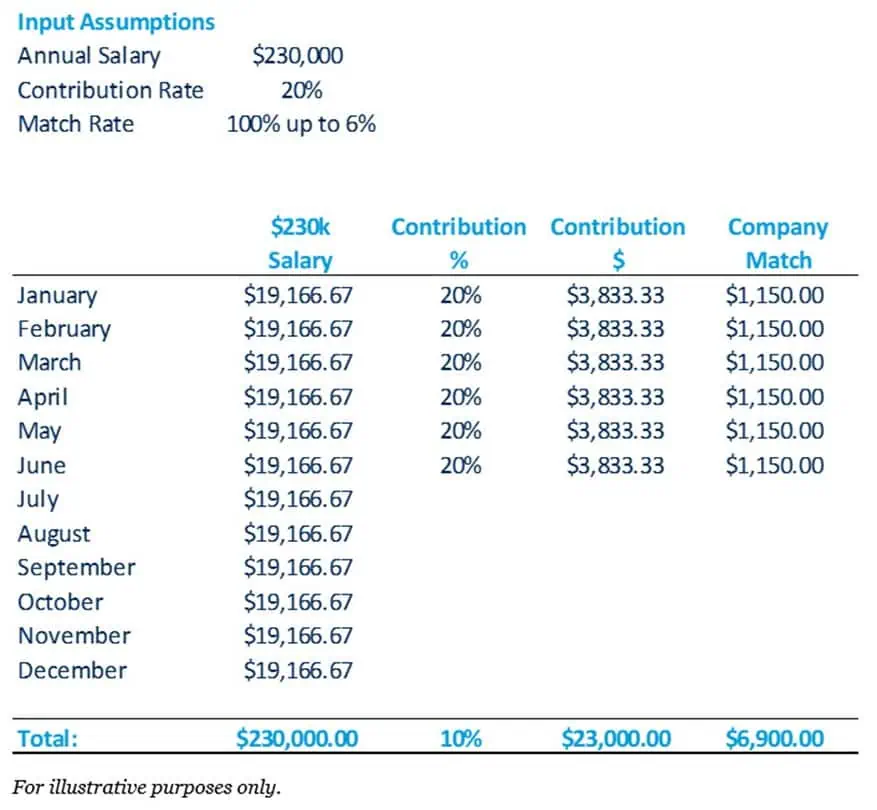
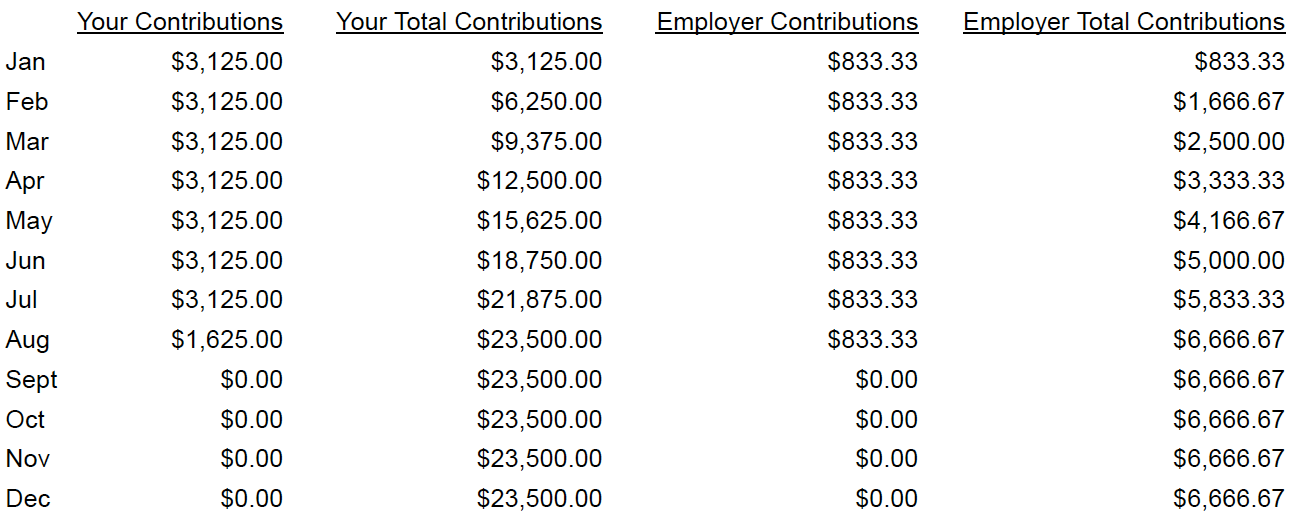
A 401(k) true-up is a corrective contribution made by an employer to ensure you receive the full matching amount you are entitled to for the entire plan year. This typically occurs when your contributions are front-loaded or unevenly distributed throughout the year. For example, if you max out your 401(k) contributions by June, you might miss out on matching funds for the remaining months because many employers match on a per-paycheck basis. The true-up provision reconciles this discrepancy at the end of the year.
Why a 401(k) True-Up Calculator Matters
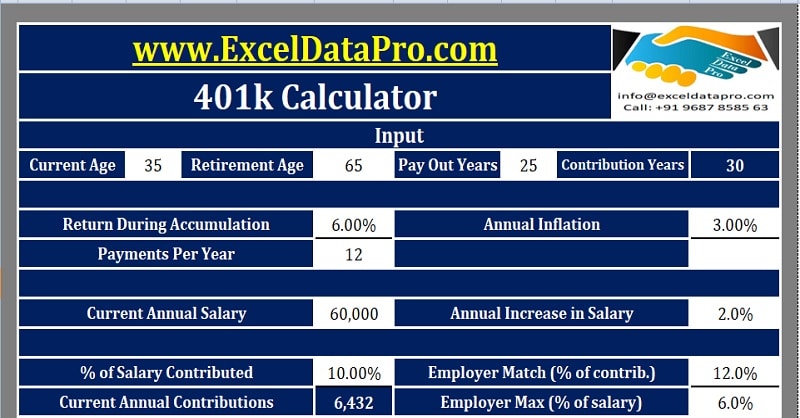
Manually calculating your potential true-up amount can be complex. A 401(k) true-up calculator simplifies this process by factoring in your total annual contributions, the employer match rate, and the specific timing of your deposits. It helps you visualize whether you’ve already secured your full match or if you need to adjust your contribution strategy. This tool is particularly valuable for high earners who reach the annual contribution limit early in the fiscal year.

Key Inputs for Accurate Calculation
To get the most out of a true-up calculator, you need to gather specific data points. These inputs ensure the tool provides a precise estimate of your potential employer contribution.
- Total Annual Employee Contributions: The sum of all your deferrals for the year.
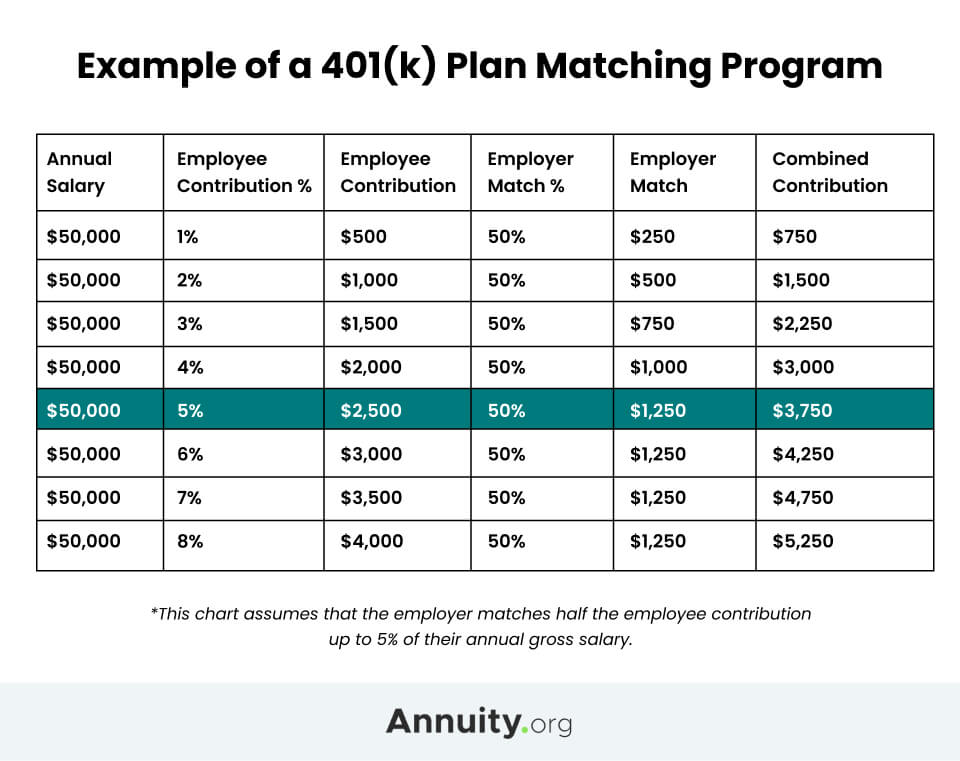
- Employer Match Rate: The percentage your company matches (e.g., 50% of the first 6% of salary).
- Contribution Timing: Whether you contributed evenly or front-loaded your contributions.
- Vesting Schedule: How much of the match you actually own based on tenure.
How the True-Up Process Works
Most 401(k) plans calculate matches on a per-paycheck basis. If you stop contributing after hitting the IRS limit, your employer stops matching. At year-end, the plan administrator reviews your total eligible compensation and total match owed. If the per-paycheck match was less than the total match owed based on annual compensation, the employer deposits the difference. This "true-up" ensures you receive the full benefit.
| Scenario | Without True-Up | With True-Up |
|---|---|---|
| Front-loaded Contributions | Missed match for later months | Full annual match received |
| Even Contributions | Match aligns with contributions | No adjustment needed |
Maximizing Your Retirement Savings
Understanding the mechanics of a true-up allows you to make informed decisions about your contribution schedule. If your employer does not offer a true-up, you might consider spreading your contributions evenly to capture every dollar of the match. Conversely, if a true-up is guaranteed, you can front-load your contributions to maximize tax-advantaged growth earlier in the year. Using a 401(k) true-up calculator empowers you to model these scenarios and optimize your long-term financial strategy.