What is Included in an Annuity Contract: A Comprehensive Guide
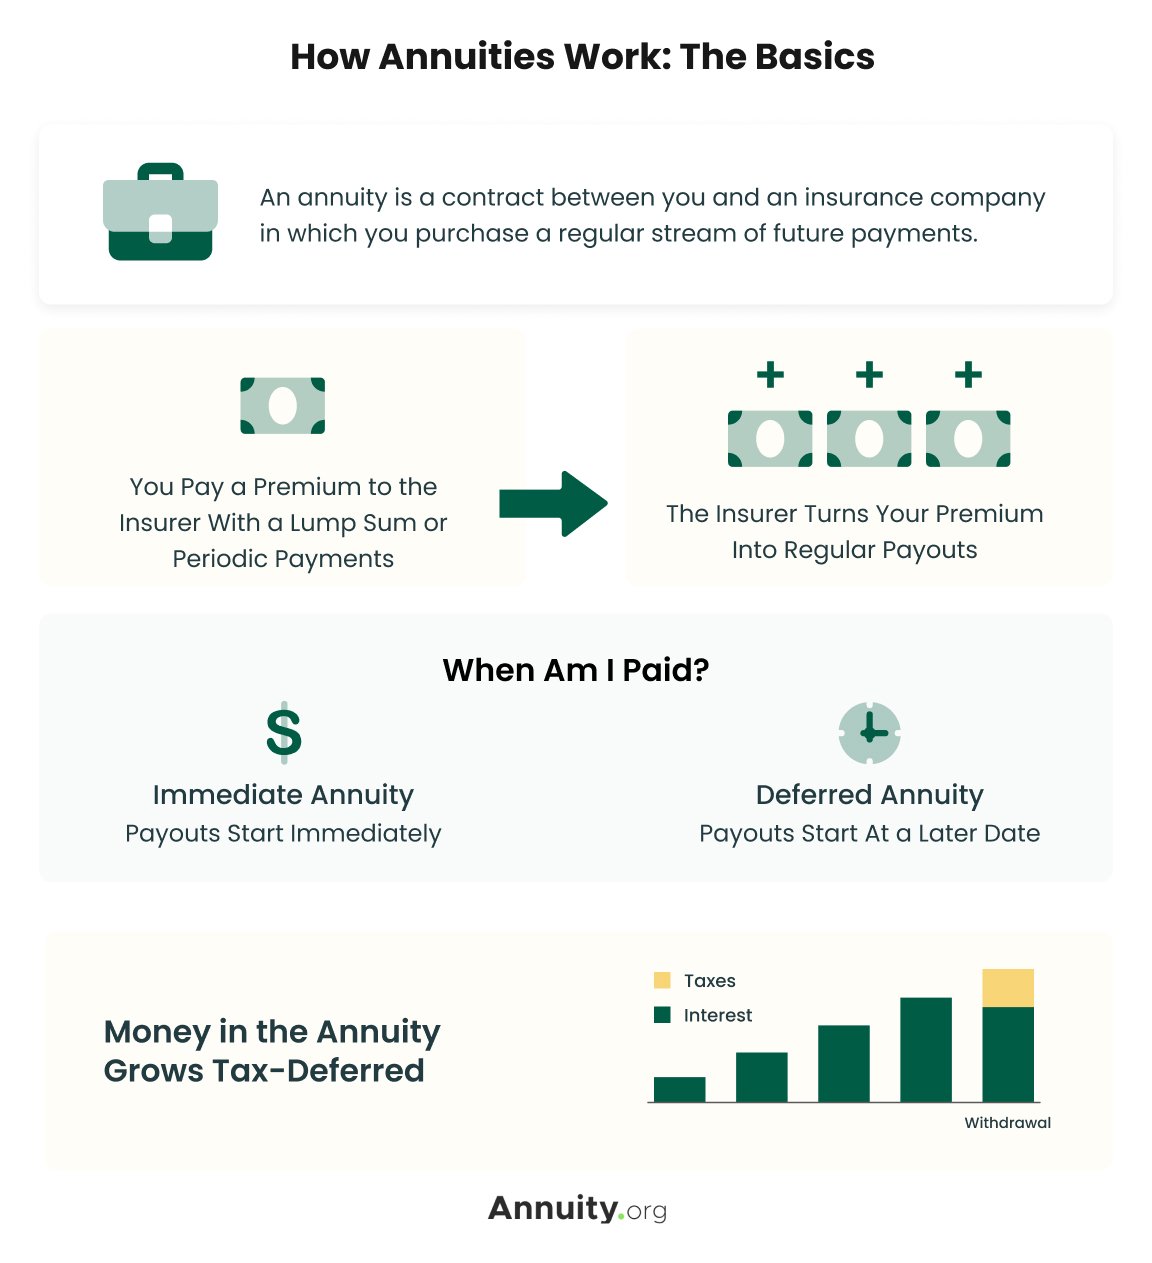
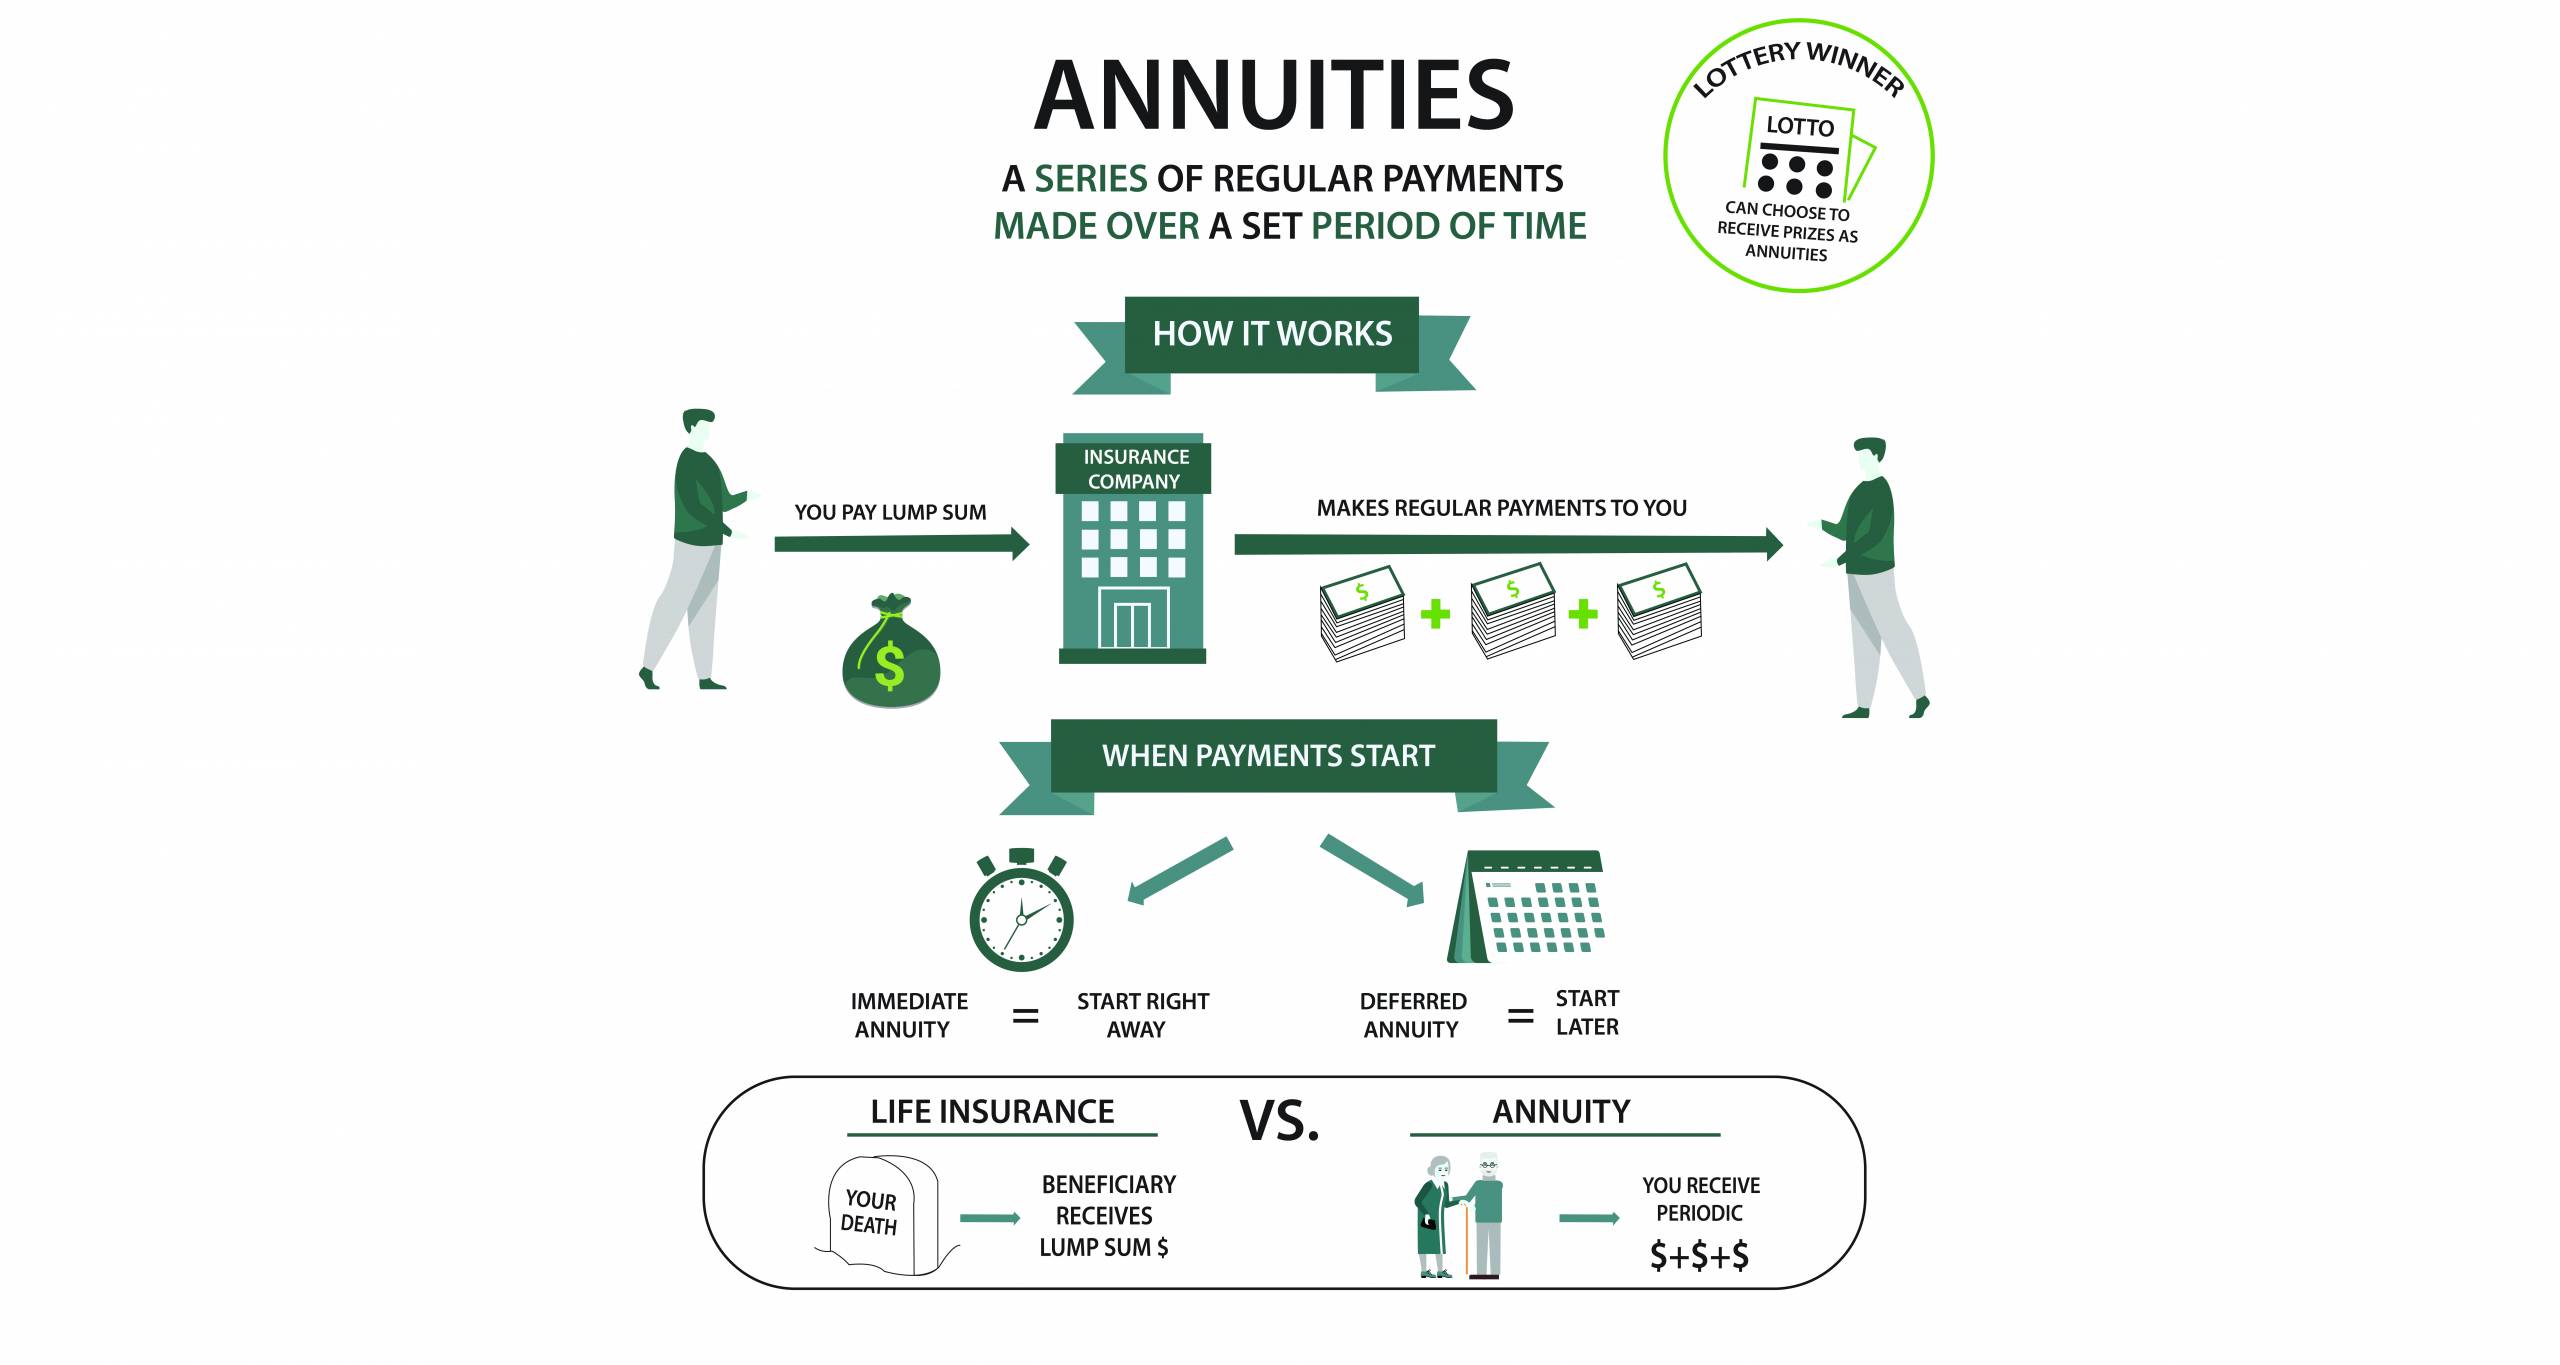
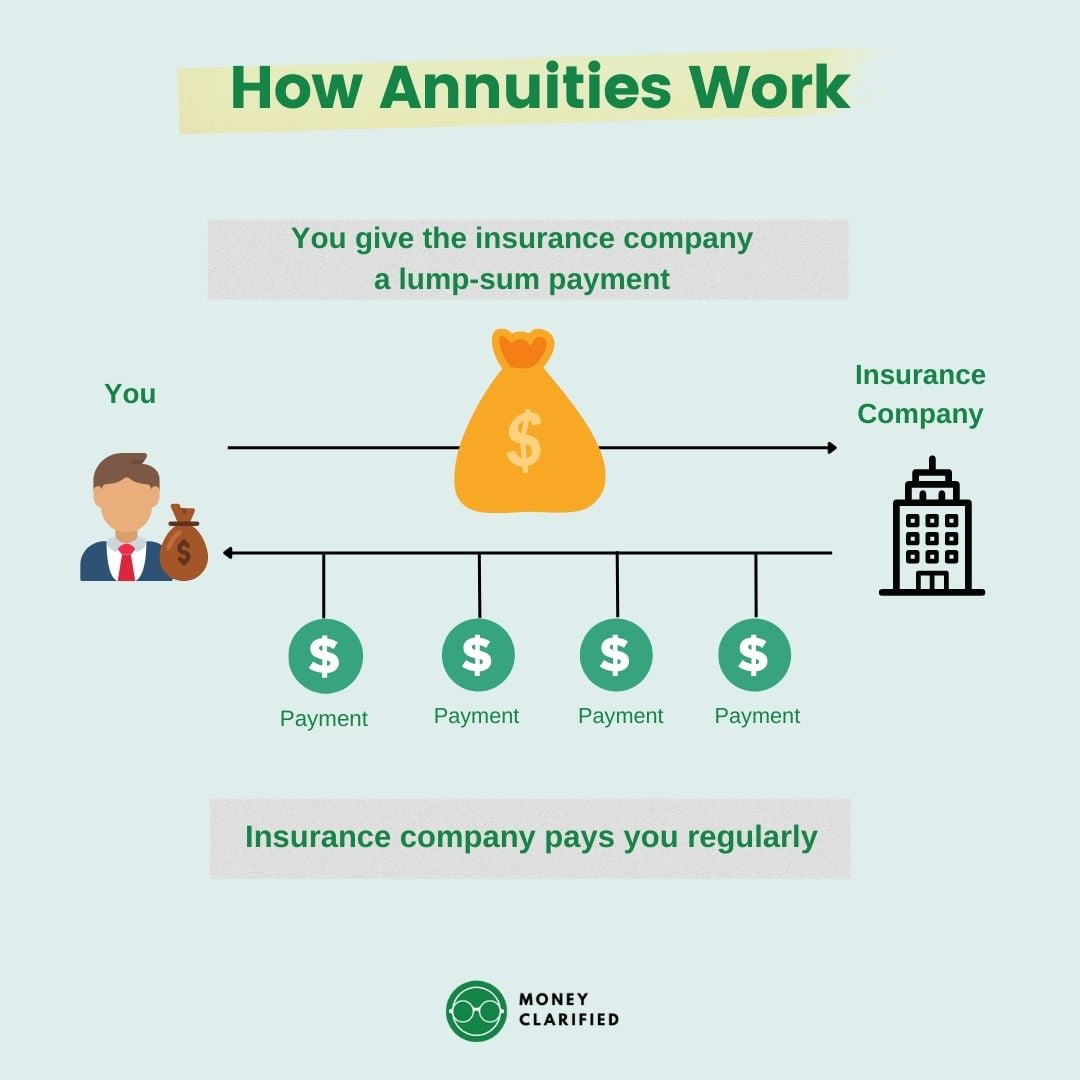
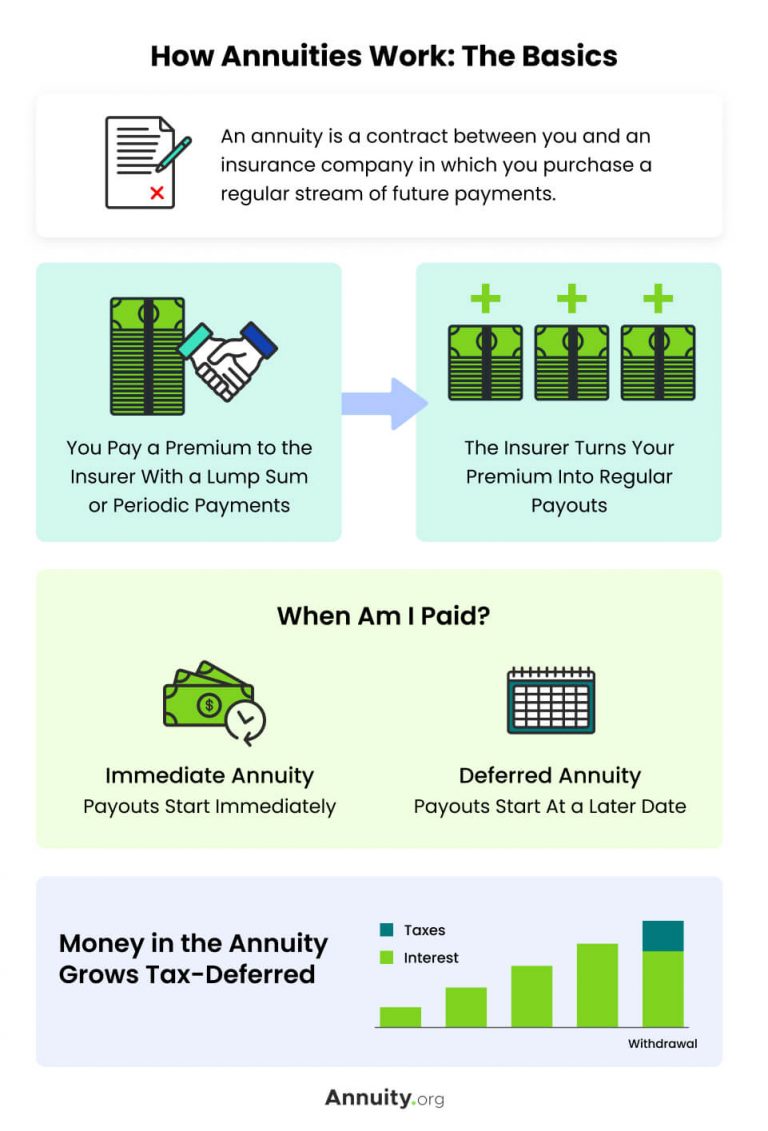
An annuity contract is a complex financial instrument that provides a steady income stream to individuals in exchange for a lump sum payment or a series of payments. When purchasing an annuity, it's essential to understand what's included in the contract to make an informed decision. This guide will walk you through the key components of an annuity contract.
Types of Annuity Contracts
Annuity contracts come in various forms, including fixed, variable, and indexed. Each type of contract has its own set of features and benefits. Here's a brief overview of the main types:
- Fixed Annuities: These contracts offer a guaranteed interest rate for a specified period, typically 5-10 years. The interest rate is fixed, and the returns are predictable.
- Variable Annuities: These contracts invest in a portfolio of assets, such as stocks and bonds, which can increase or decrease in value based on market performance. The returns are not guaranteed, and the investor bears the risk of market fluctuations.
- Indexed Annuities: These contracts tie their returns to a specific market index, such as the S&P 500. The returns are based on the performance of the underlying index, and the investor benefits from the growth of the index.
Payout Options
Annuity contracts offer various payout options, which determine how the annuity income is paid out to the policyholder. The most common payout options include:

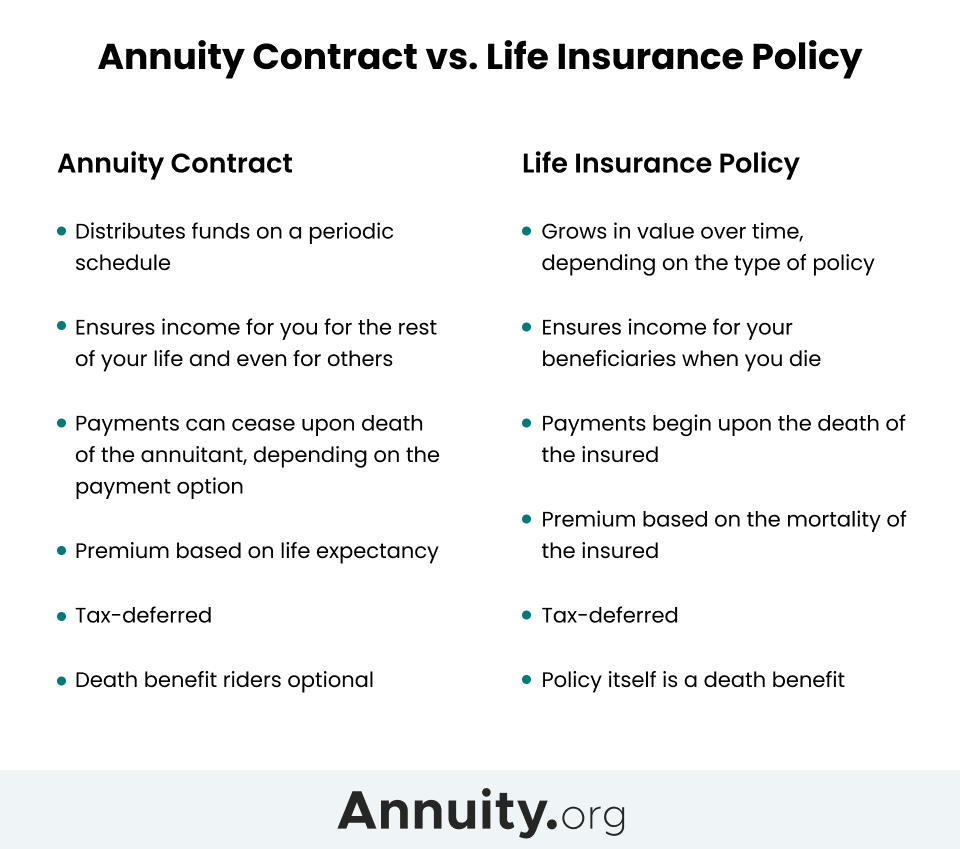
- Lifetime Income: This option provides a guaranteed income stream for the policyholder's lifetime.
- Term Certain: This option provides a guaranteed income stream for a specified period, such as 10-20 years.
- Joint Life: This option provides a guaranteed income stream for the policyholder and their spouse, as long as either of them is alive.
Fees and Charges
Annuity contracts come with various fees and charges, which can impact the policyholder's returns. These fees include:
- Administrative Fees: These fees cover the costs of maintaining the annuity contract.
- Management Fees: These fees cover the costs of managing the underlying investments.
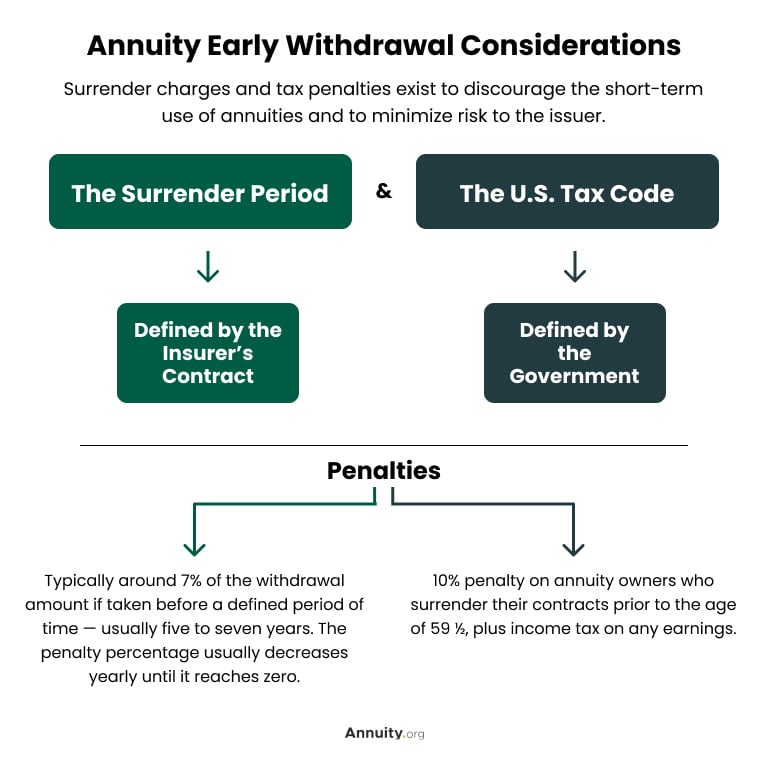
- Surrender Charges: These fees are imposed if the policyholder surrenders the annuity contract within a certain period.
Guarantees and Protections
Annuity contracts often come with various guarantees and protections, which provide a level of security for the policyholder. These guarantees include:
- Guaranteed Minimum Income Benefits: These guarantees provide a minimum income stream, even if the underlying investments perform poorly.
- Guaranteed Minimum Death Benefits: These guarantees provide a death benefit to the policyholder's beneficiaries, even if the underlying investments perform poorly.
Investment Options
Variable and indexed annuity contracts often offer a range of investment options, which allow policyholders to customize their investments. These investment options include:

- Stocks: These investments offer the potential for long-term growth, but come with a higher level of risk.
- Bonds: These investments offer a steady income stream, but may not keep pace with inflation.
- Real Estate: These investments offer a potential for long-term growth, but come with a higher level of risk.
Annuitization
Annuitization is the process of converting the lump sum payment or series of payments into a steady income stream. This process can be complex, and the policyholder should consult with a financial advisor to determine the best annuitization strategy.
Taxes and Withdrawals
Annuity contracts are subject to income taxes, and policyholders should understand the tax implications of their contract. Withdrawals from the contract may be subject to penalties, and policyholders should consult with a tax professional to determine the best withdrawal strategy.