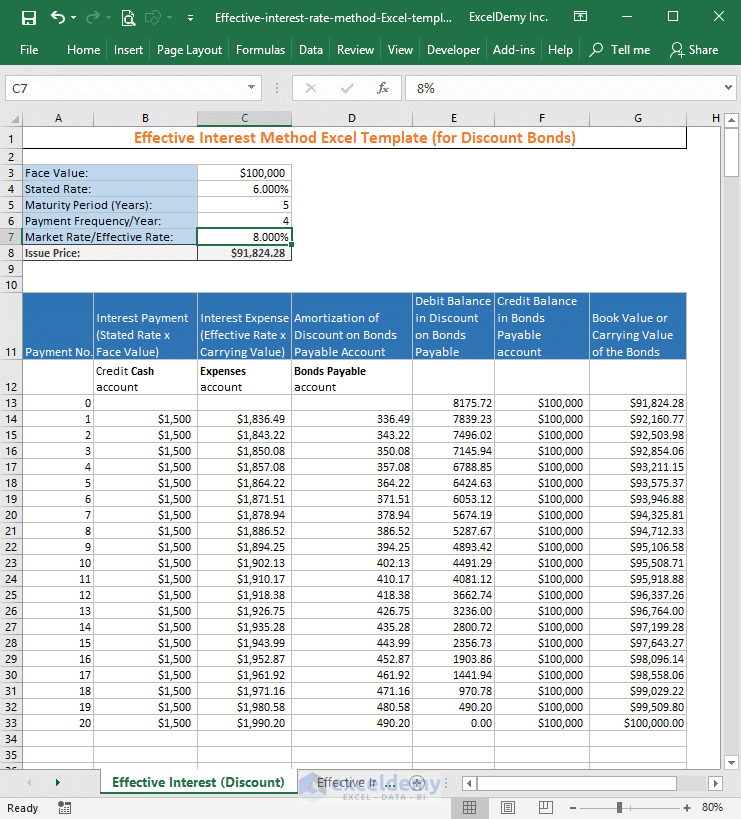
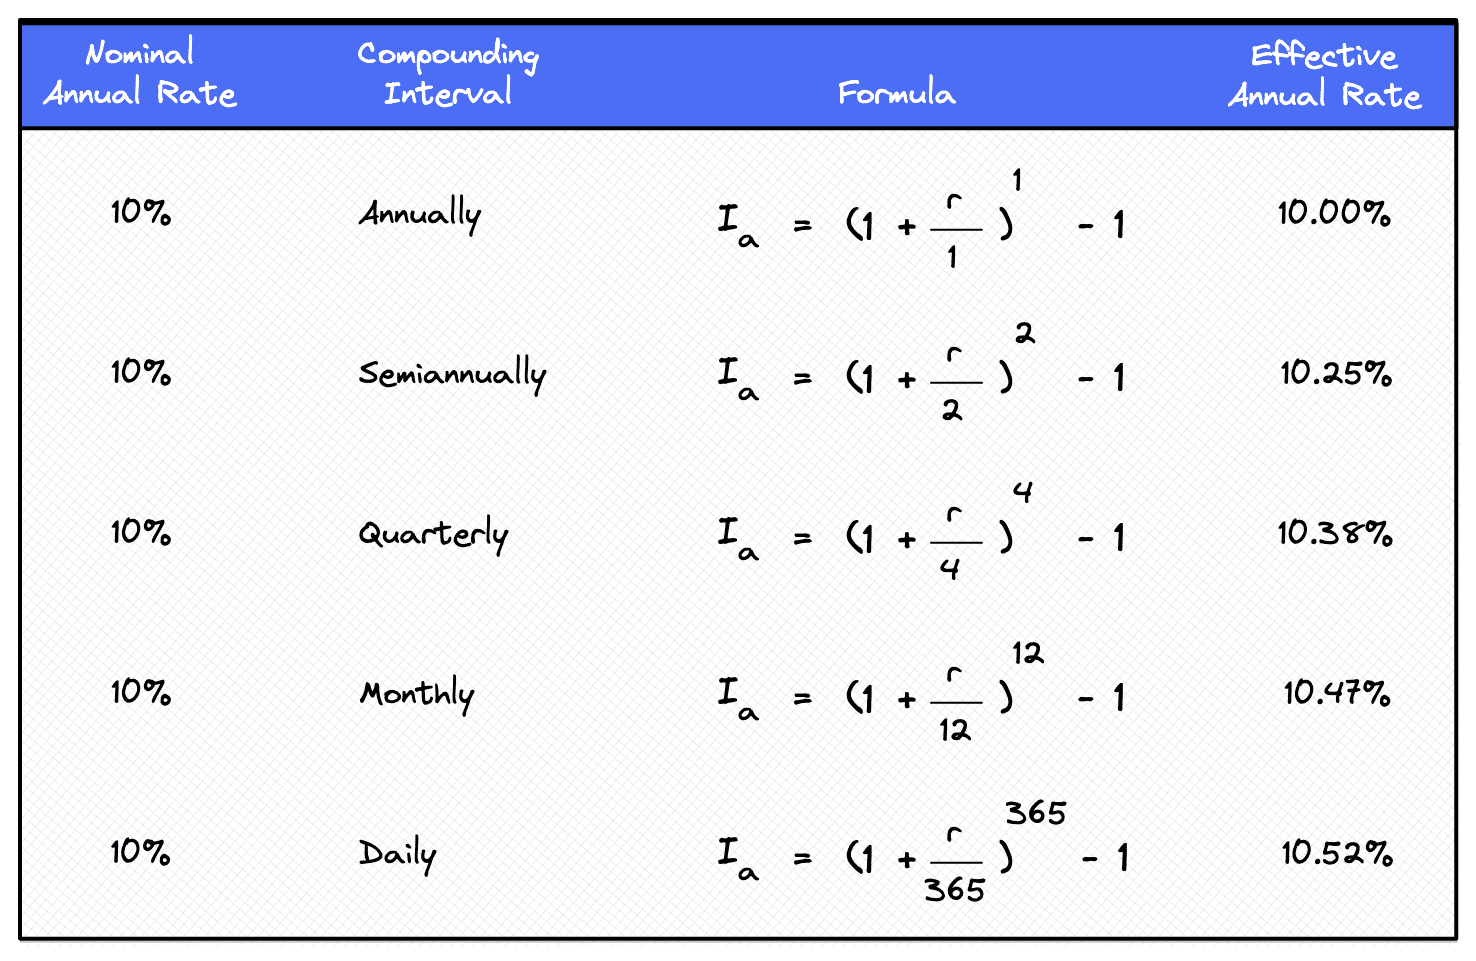
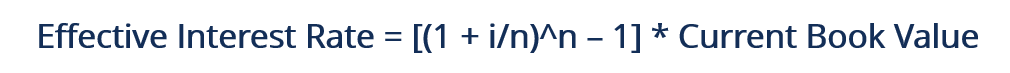Understanding the Effective Interest Rate Method
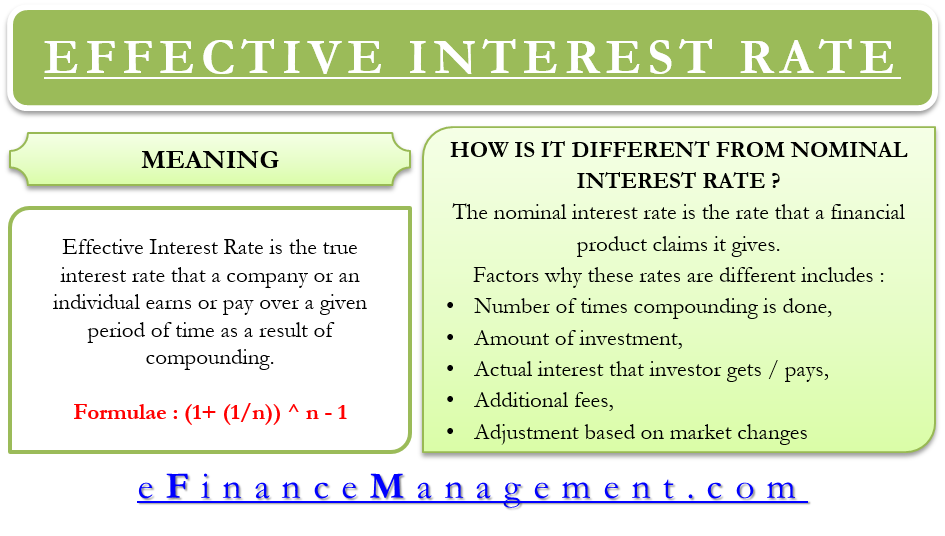
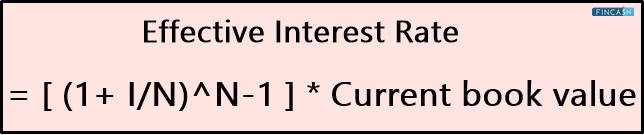
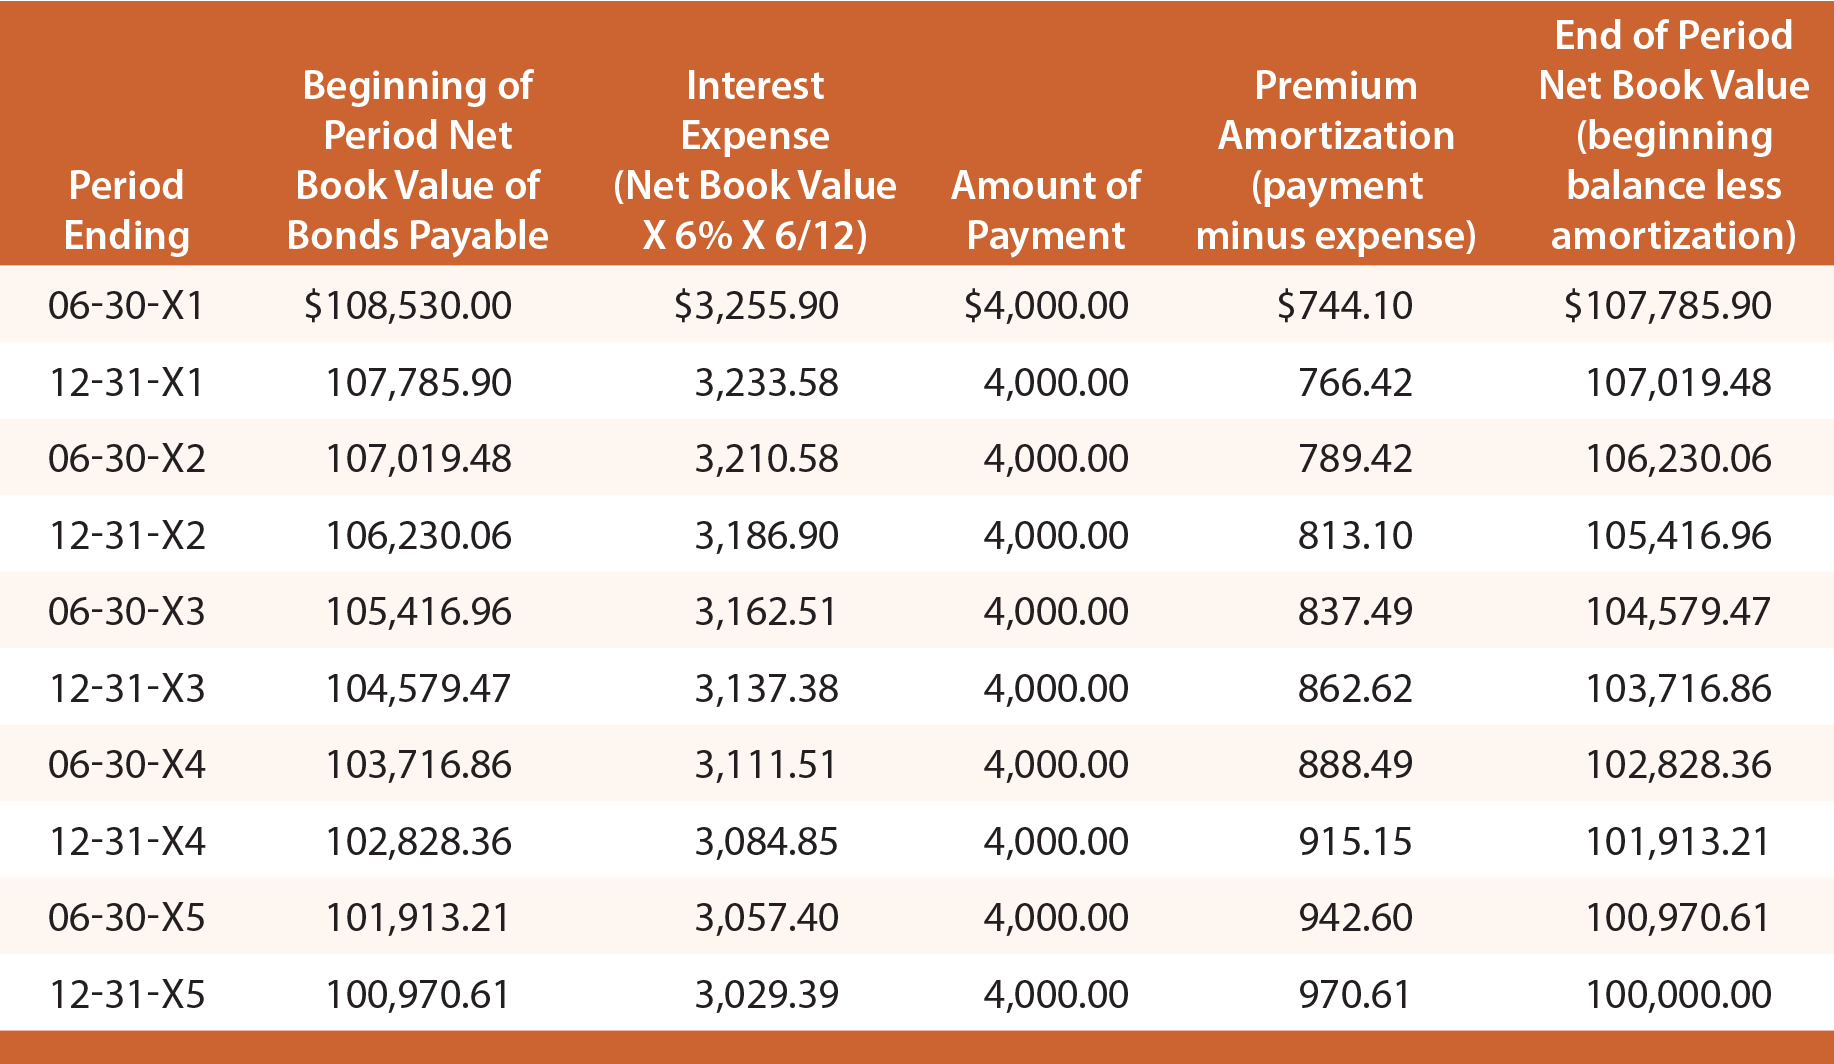
The Effective Interest Rate Method (EIRM) is a powerful tool used in finance to calculate the average interest rate on a loan or investment that has a varying interest rate over its lifetime. It's particularly useful when dealing with loans that have different interest rates over time, such as floating-rate notes or mortgage loans with varying interest rates. This method helps to provide a more accurate representation of the actual cost of borrowing or investing.
Why Use the Effective Interest Rate Method?
Unlike the simple interest rate method, which calculates interest based on the initial principal and a flat interest rate, the EIRM takes into account the time value of money and the changing interest rates. This makes it a more accurate and effective way to calculate the true cost of borrowing or the return on an investment.
How the Effective Interest Rate Method Works
The EIRM works by calculating the present value of each cash flow (interest payments and principal repayments) and then finding the internal rate of return (IRR) of these cash flows. The IRR is the effective interest rate that equates the present value of the cash inflows to the present value of the cash outflows.

Calculating the Effective Interest Rate
To calculate the effective interest rate, you would typically follow these steps:
- List out all the cash inflows (interest payments) and cash outflows (principal repayments) over the life of the loan or investment.
- Calculate the present value of each cash flow using the initial principal and the discount rate (which is initially set to the first interest rate).
- Adjust the discount rate and repeat step 2 until the present value of the cash inflows equals the present value of the cash outflows.
- The discount rate at which the present values of the cash inflows and outflows are equal is the effective interest rate.
Example of the Effective Interest Rate Method
Let's consider a simple example to illustrate the EIRM. Suppose you take out a loan of $100,000 with an initial interest rate of 5% for the first year, 6% for the second year, and 7% for the third year. You repay $30,000 at the end of the first year, $40,000 at the end of the second year, and $30,000 at the end of the third year.
| Year | Interest Rate | Principal Repayment | Interest Payment |
|---|---|---|---|
| 1 | 5% | $30,000 | $5,000 |
| 2 | 6% | $40,000 | $6,000 |
| 3 | 7% | $30,000 | $7,000 |
Using the EIRM, you would calculate the present value of each cash flow and find the IRR. Let's say you find that the effective interest rate is 6.2%. This means that the average annual cost of borrowing over the three years is 6.2%.
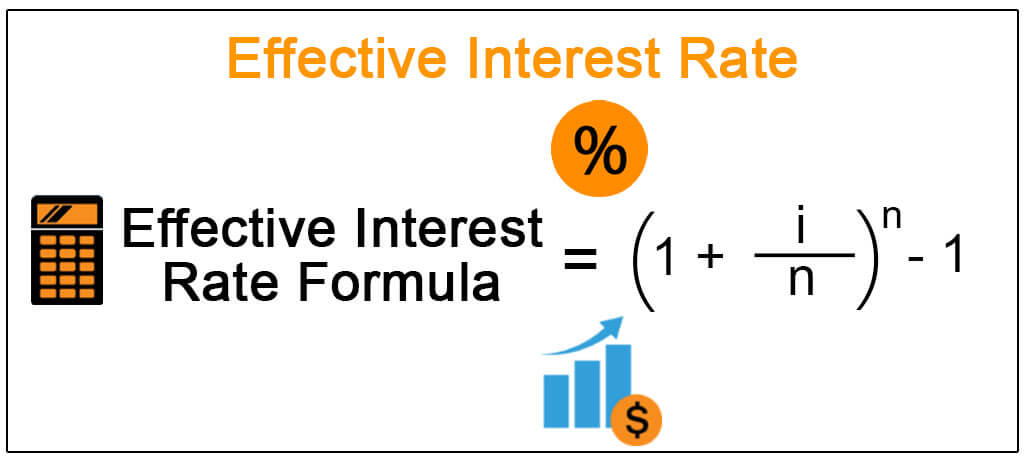
Limitations of the Effective Interest Rate Method
While the EIRM provides a more accurate representation of the true cost of borrowing or investing, it's not without its limitations. It can be complex and time-consuming to calculate, especially for loans or investments with many cash flows or changing interest rates. It also assumes that the cash flows can be reinvested at the same rate as the effective interest rate, which may not always be the case.
Conclusion
The Effective Interest Rate Method is a valuable tool for understanding the true cost of borrowing or the return on an investment. By taking into account the time value of money and changing interest rates, it provides a more accurate and effective way to calculate the average interest rate over the life of a loan or investment. However, it's important to understand its limitations and use it appropriately.