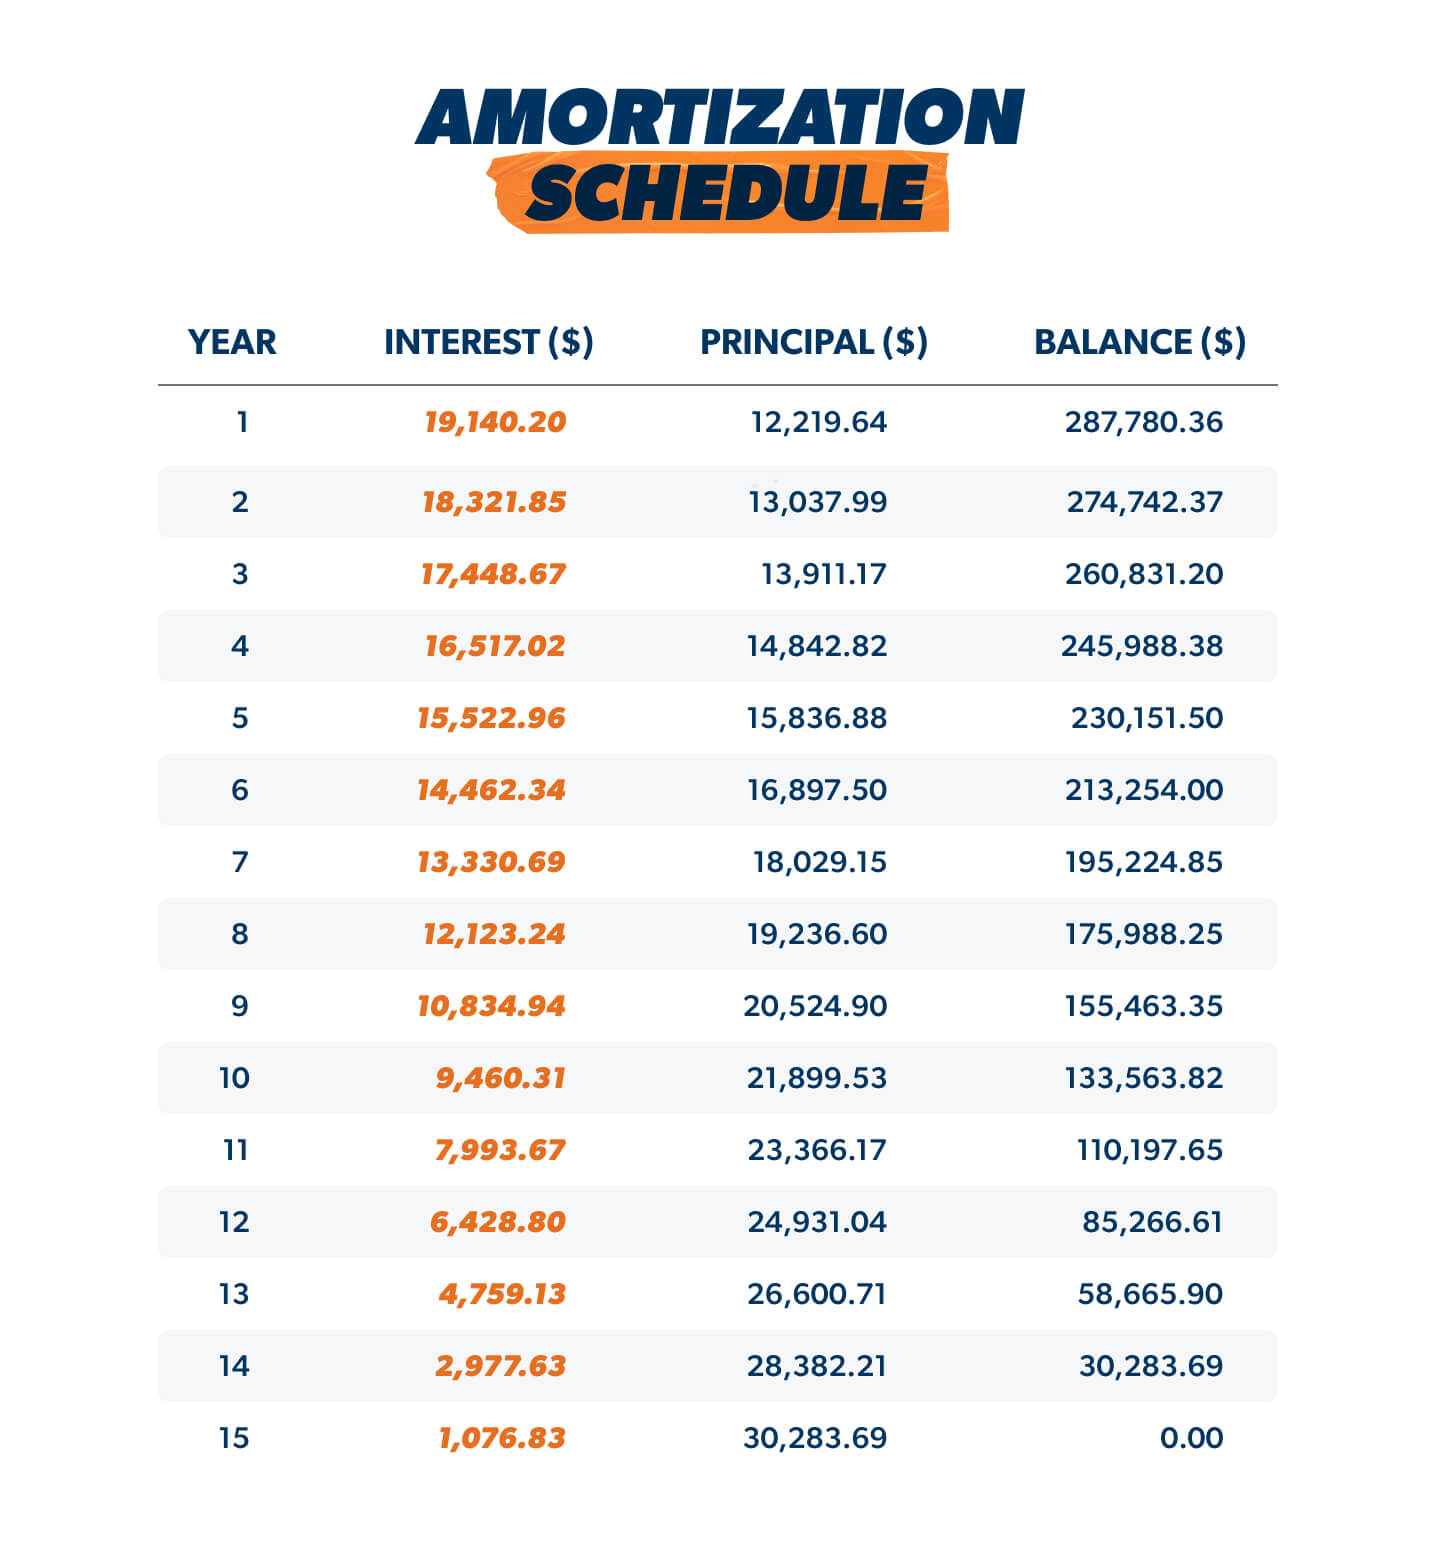
Understanding Mortgage Interest: A Comprehensive Guide
Mortgage interest can be a complex and intimidating concept for many homebuyers, but it's essential to understand how it works to make informed decisions about your home financing. In this article, we'll break down the basics of mortgage interest, explain how it's calculated, and provide tips on how to minimize its impact on your budget.
What is Mortgage Interest?
Mortgage interest is the cost of borrowing money from a lender to purchase a home. It's typically expressed as a percentage of the loan amount and is usually paid over a set period of time, such as 15 or 30 years. The interest rate is determined by the lender and can vary depending on factors like your credit score, loan term, and the type of property being purchased.
The Anatomy of a Mortgage Interest Calculation
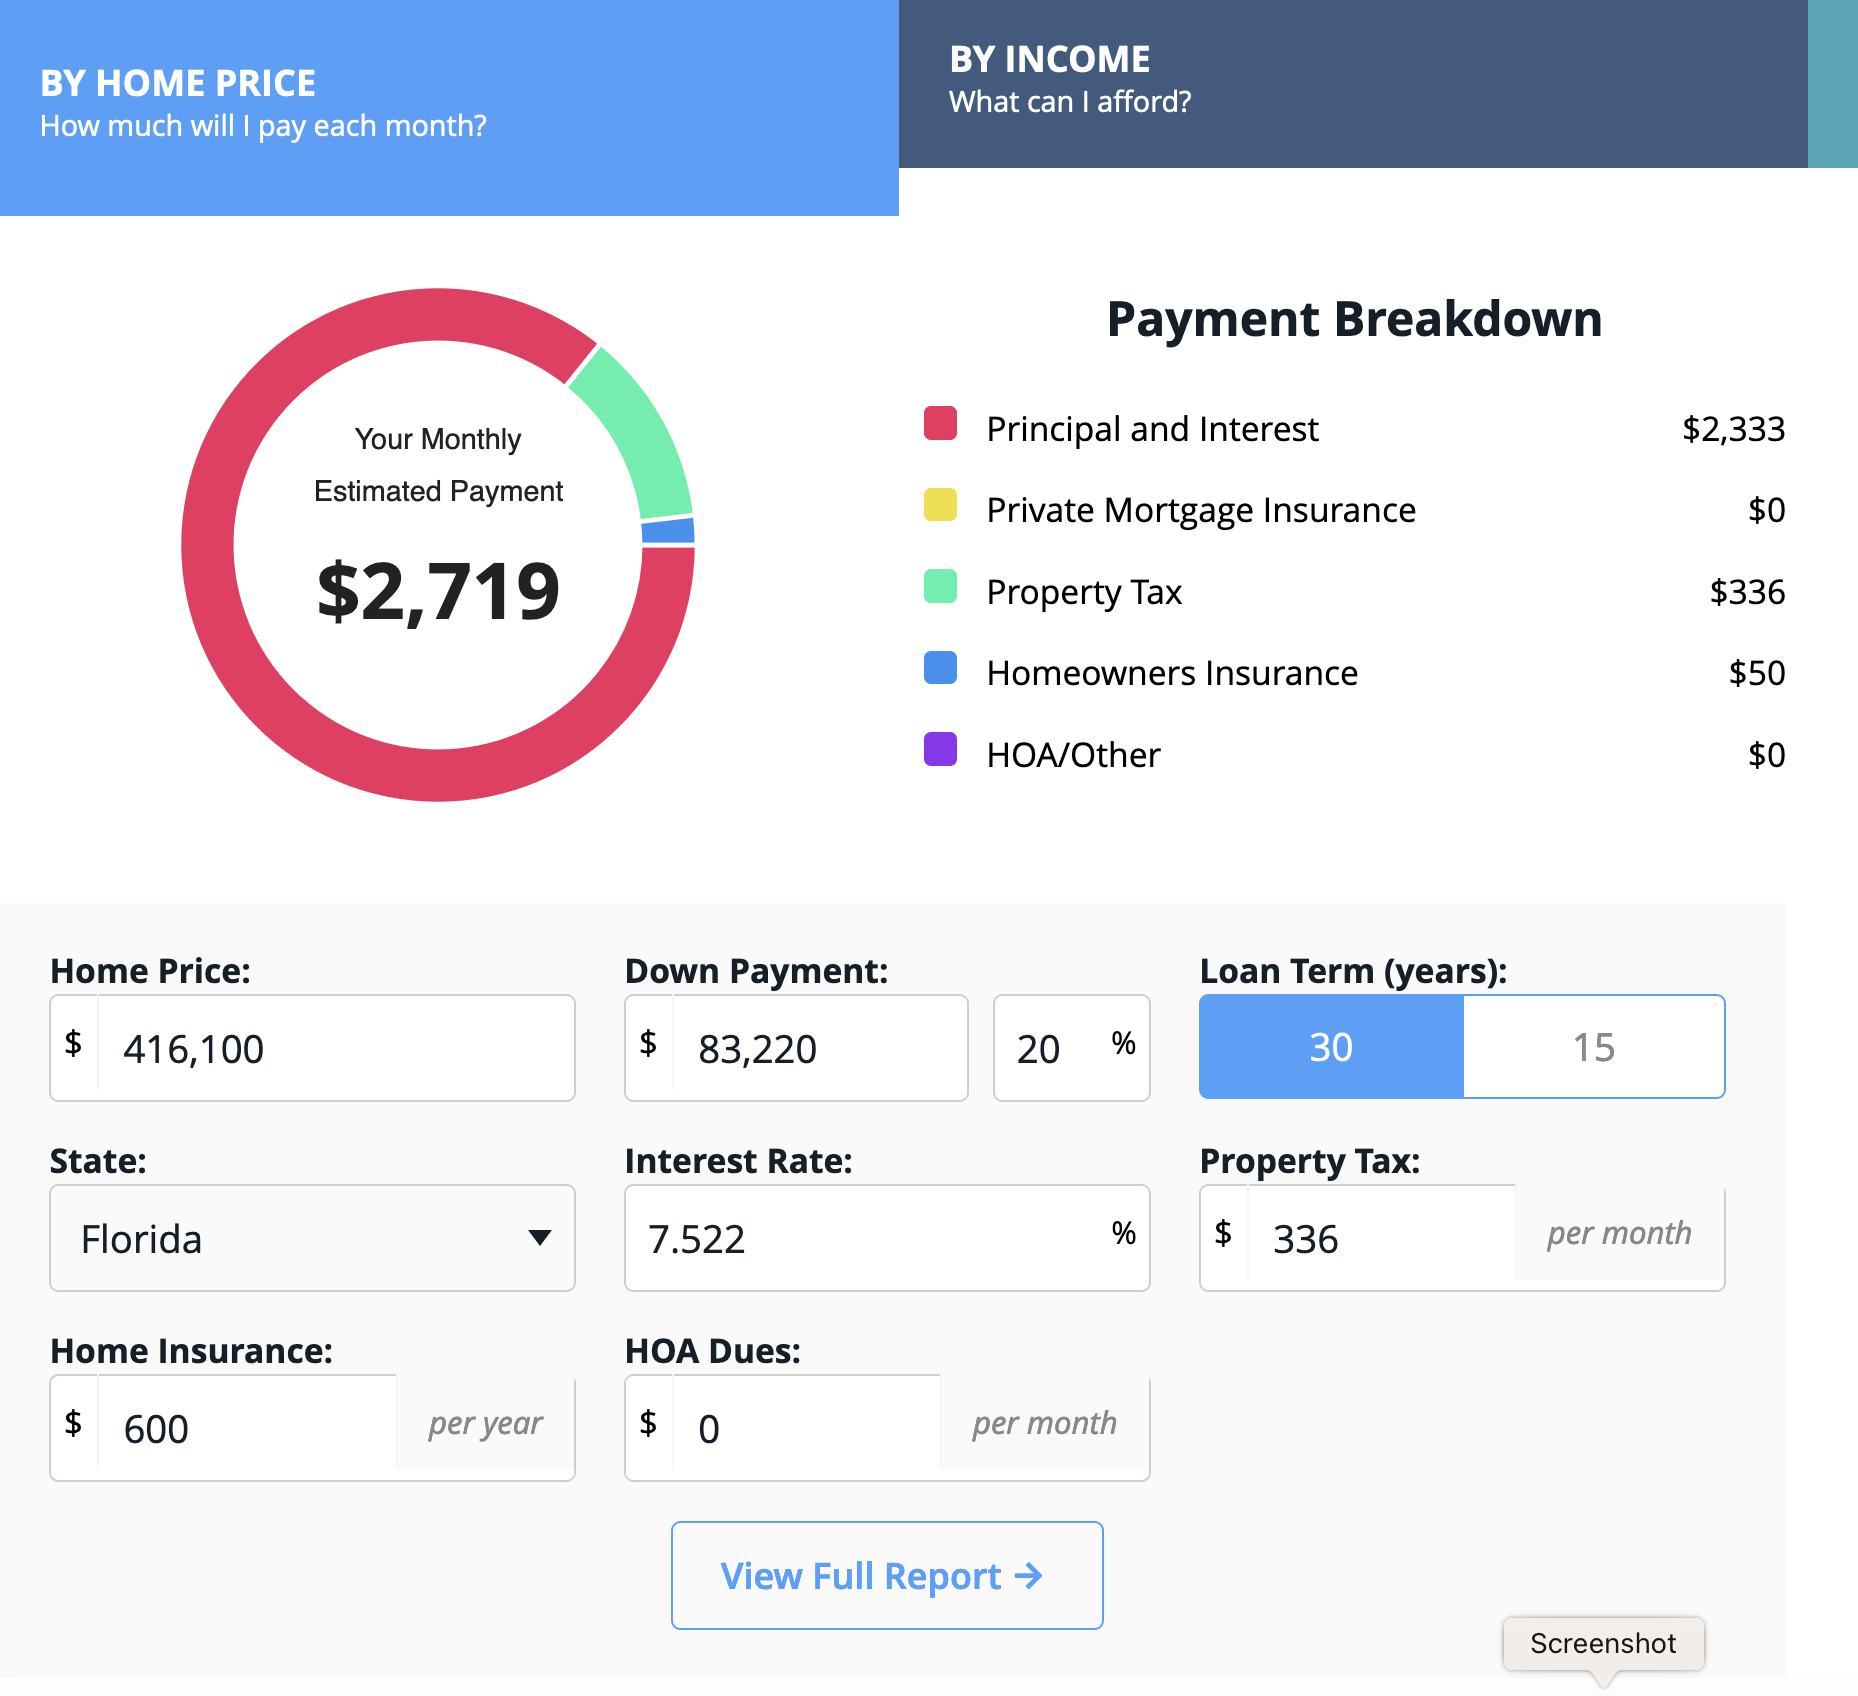
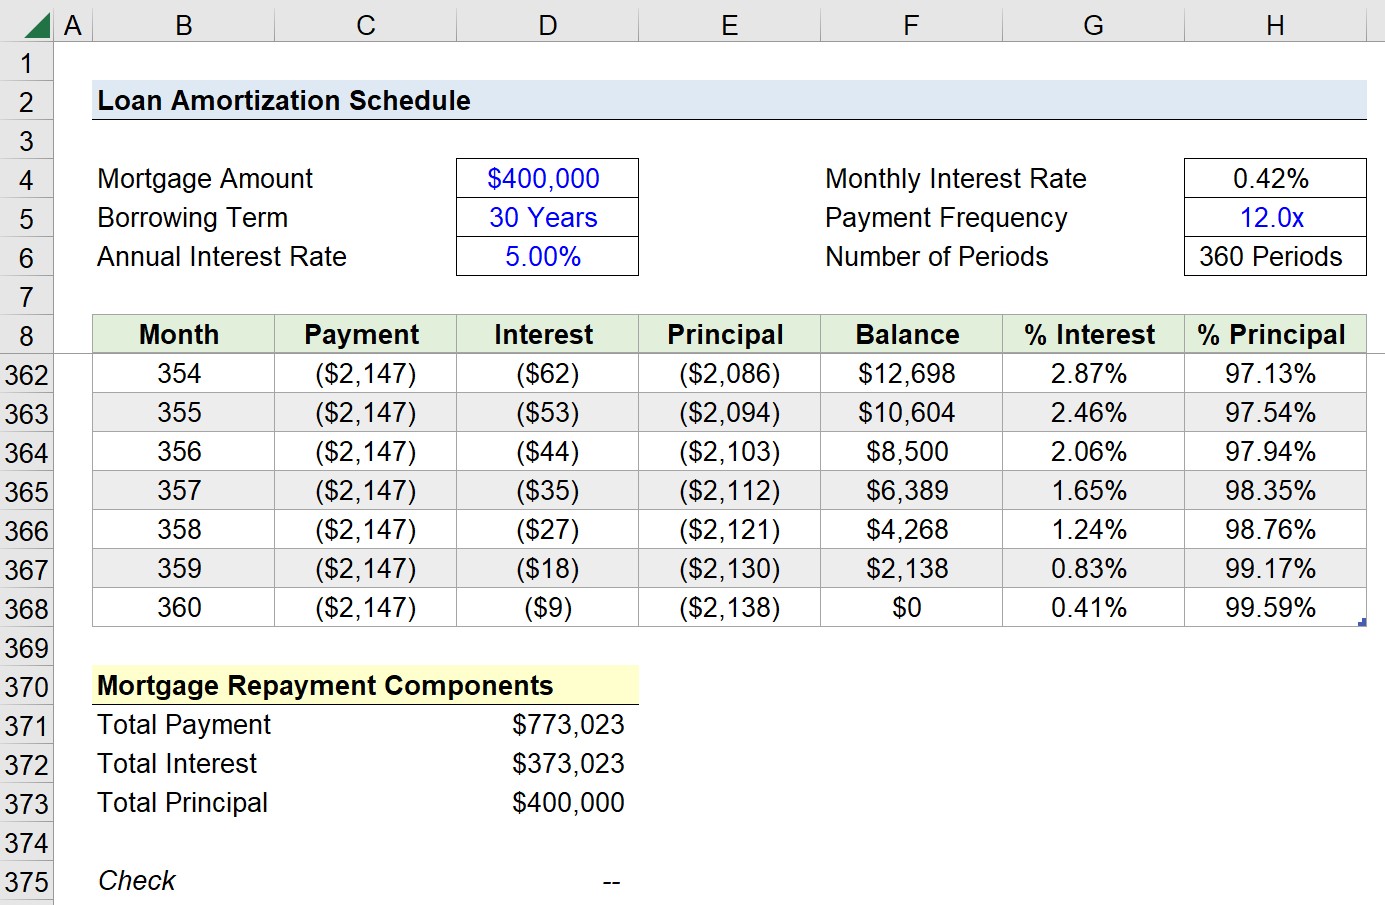
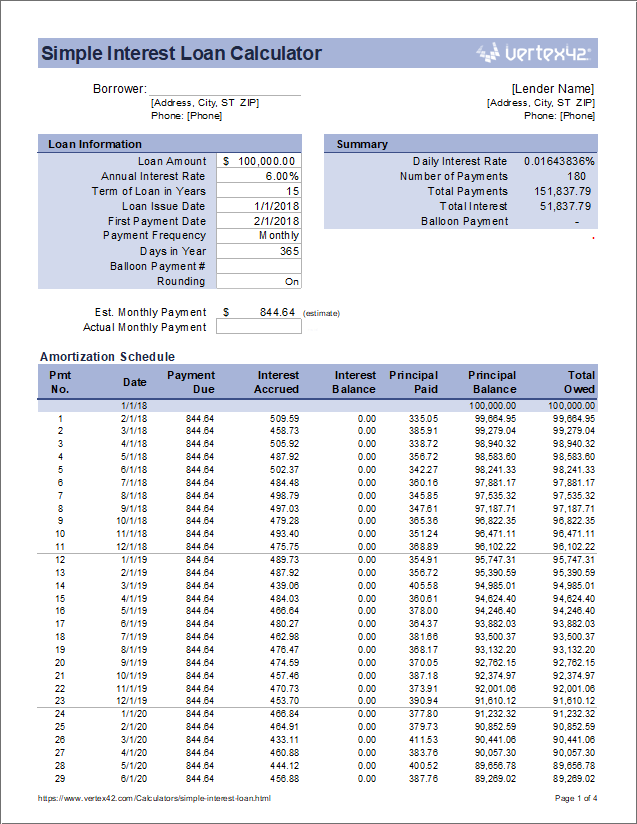
So, how is mortgage interest calculated? It's a straightforward process that involves multiplying the loan amount by the interest rate. Here's a breakdown of the key factors involved:
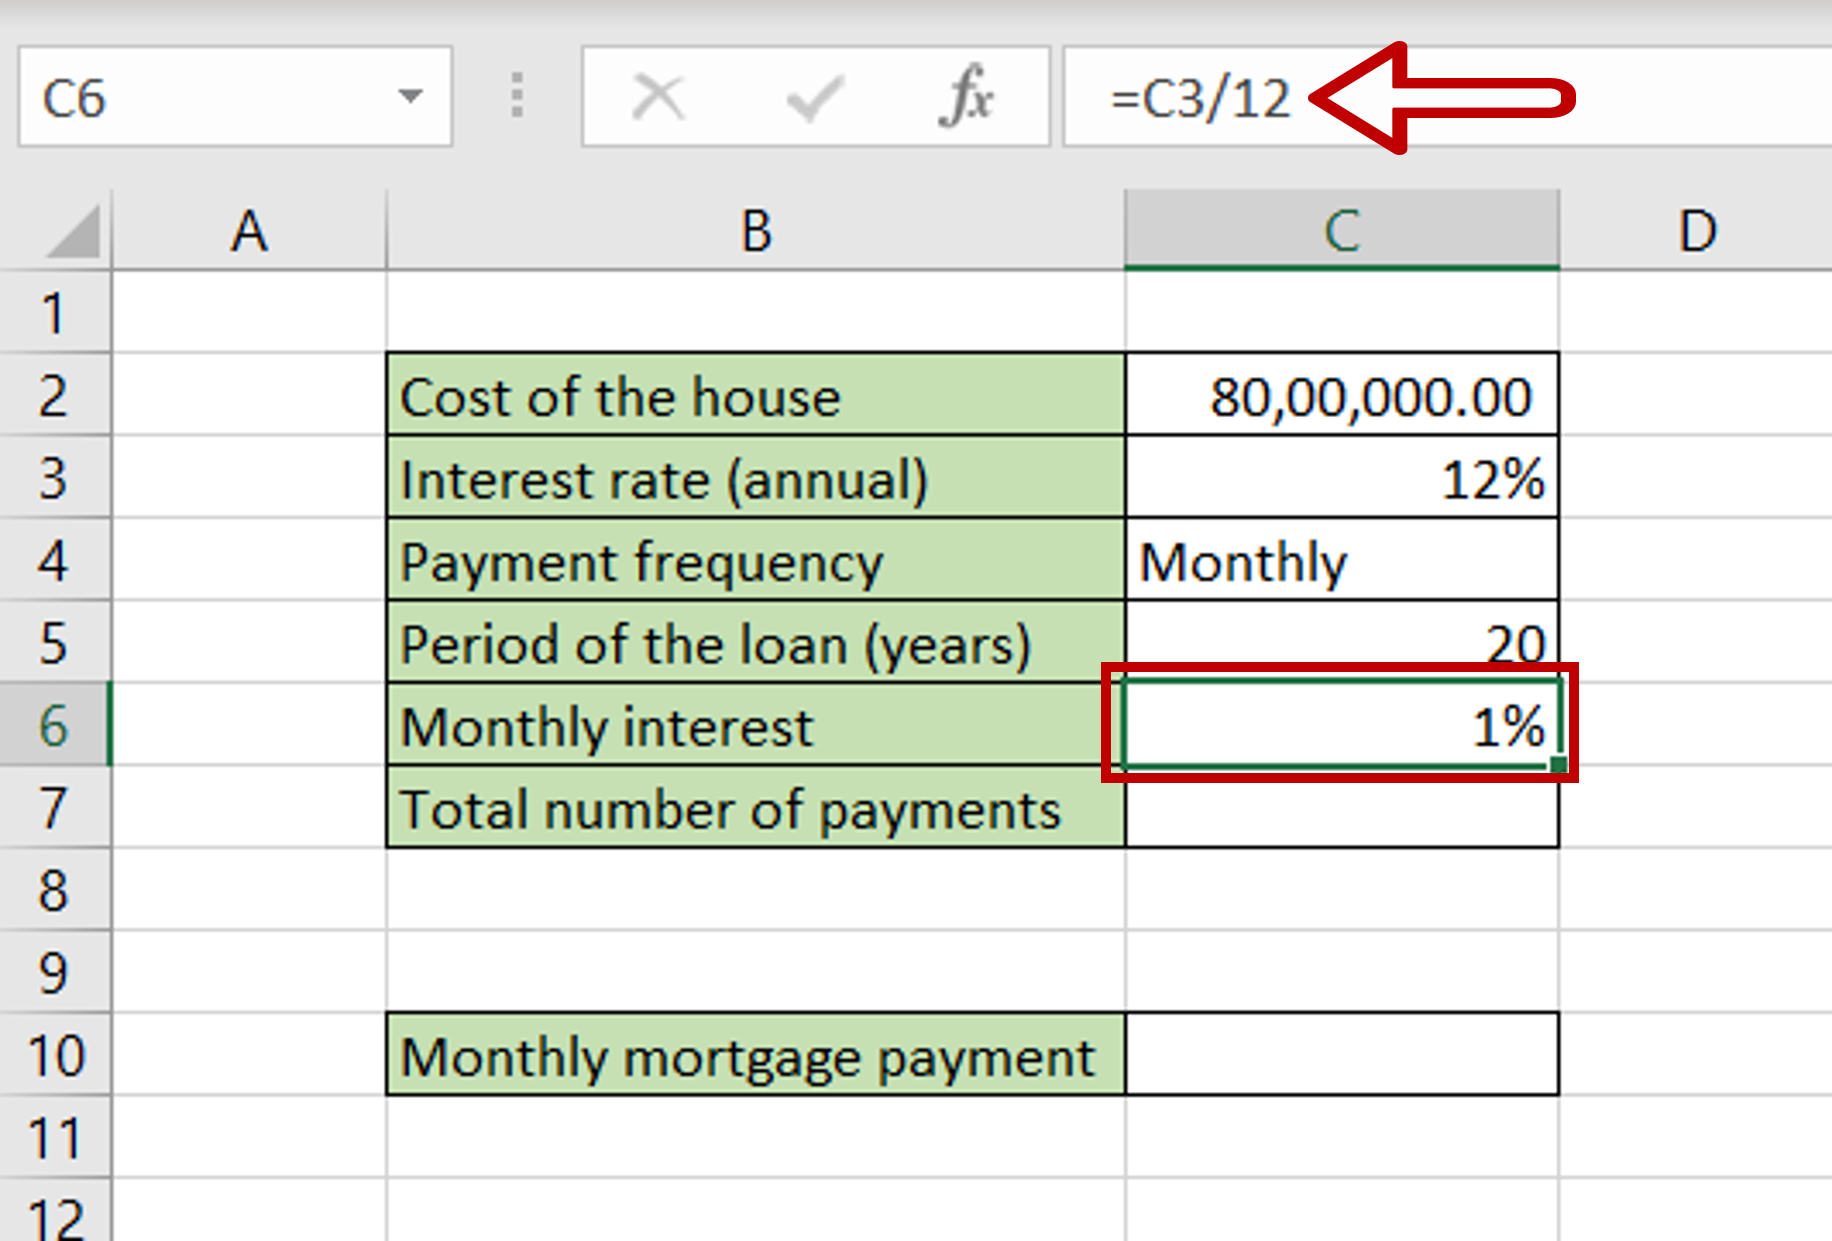
- Loan Amount: This is the total amount borrowed from the lender to purchase the home.
- Interest Rate: This is the percentage of the loan amount that's charged as interest. It's usually expressed as an annual percentage rate (APR).
- Loan Term: This is the length of time the loan is repaid, usually measured in years.
The Simple Interest Formula
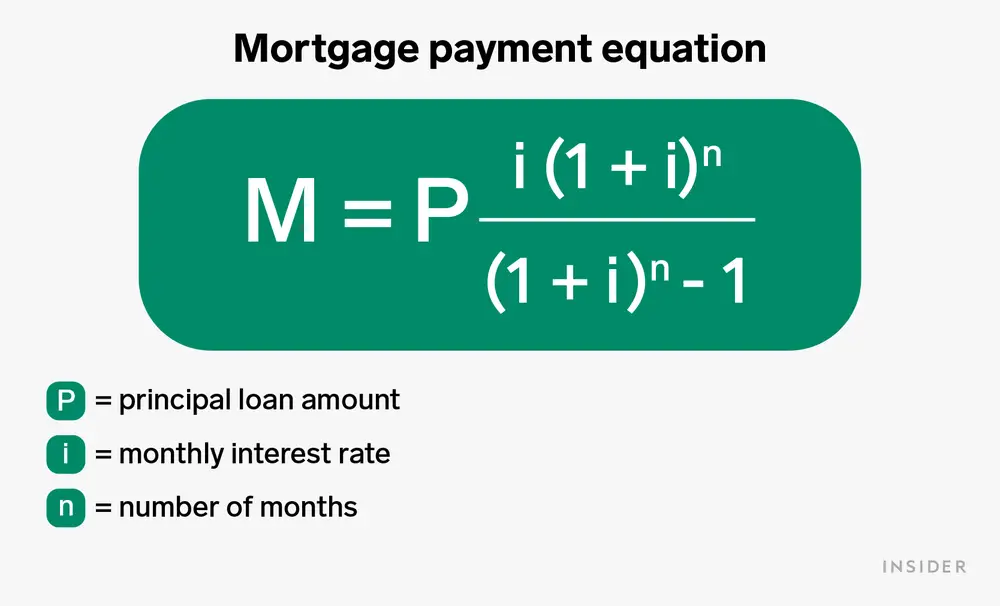
The simple interest formula is as follows:
| Loan Amount | Interest Rate (APR) | Loan Term (in years) | Mortgage Interest |
|---|---|---|---|
| $200,000 | 4% | 30 years | $140,492.51 |
Factors That Affect Mortgage Interest Rates
So, what affects mortgage interest rates? Several factors come into play, including:
- Credit Score: A higher credit score can result in lower interest rates, while a lower credit score may lead to higher rates.
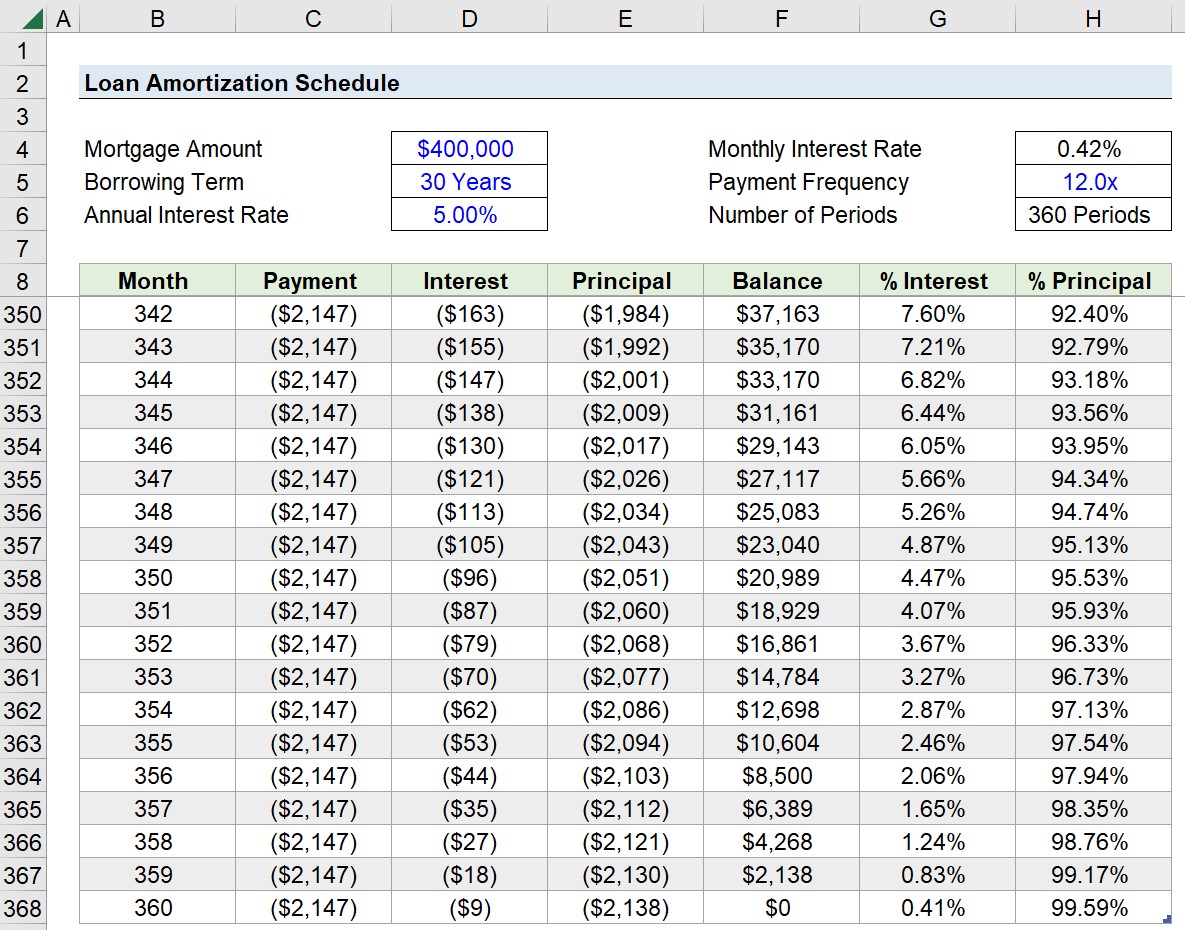
- Loan Term: Longer loan terms typically result in lower monthly payments, but also mean more interest paid over the life of the loan.
- Property Type: Different types of properties, such as primary residences or investment properties, may have different interest rates.
- Market Conditions: Interest rates can fluctuate based on economic conditions, such as inflation or recession.
Minimizing Mortgage Interest: Tips and Strategies
Want to keep your mortgage interest in check? Here are some tips to consider:

- Making extra payments: Paying more than the minimum payment each month can help reduce the principal balance and interest owed.
- Choosing a shorter loan term: Opting for a 15-year mortgage instead of a 30-year mortgage can save you thousands in interest over the life of the loan.
- Refinancing: Refinancing your mortgage to a lower interest rate can help you save money on interest.
- Improving your credit score: A higher credit score can result in lower interest rates and save you money on interest.