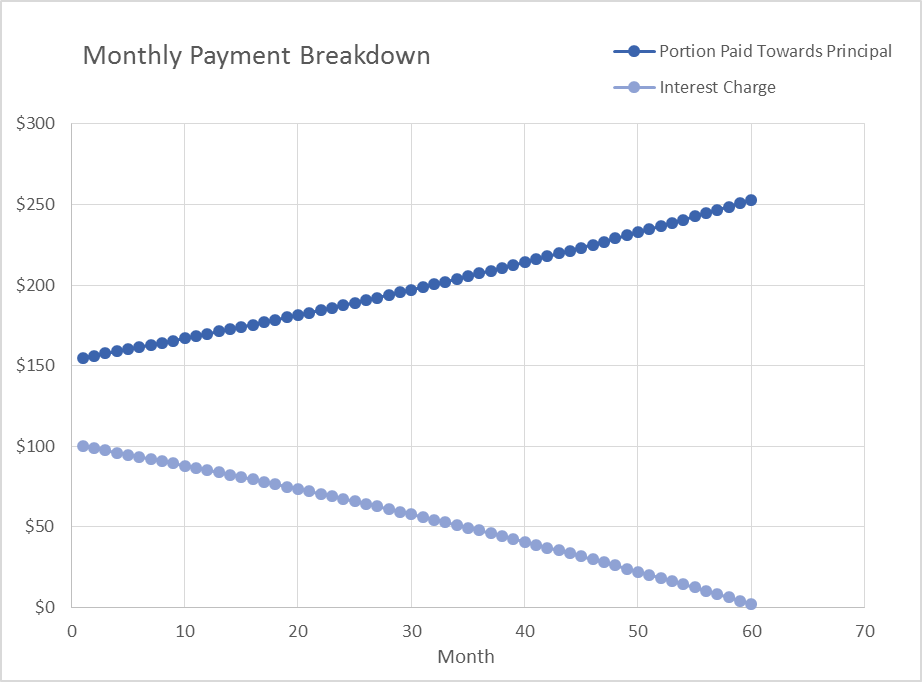
When you're in the market for a new car, understanding how car payments work is crucial. It's not just about the monthly amount you'll pay, but also the total cost, interest rates, and other factors that can impact your financial health. Let's dive into the world of car payments, breaking down the process into simple, understandable parts.
Understanding the Basics of Car Payments
Car payments are typically made through a financing agreement with a lender, which could be a bank, credit union, or the car dealership itself. The agreement outlines the total amount you'll pay, the interest rate, the loan term (usually 36 to 72 months), and the monthly payment amount. Here's a simple breakdown:
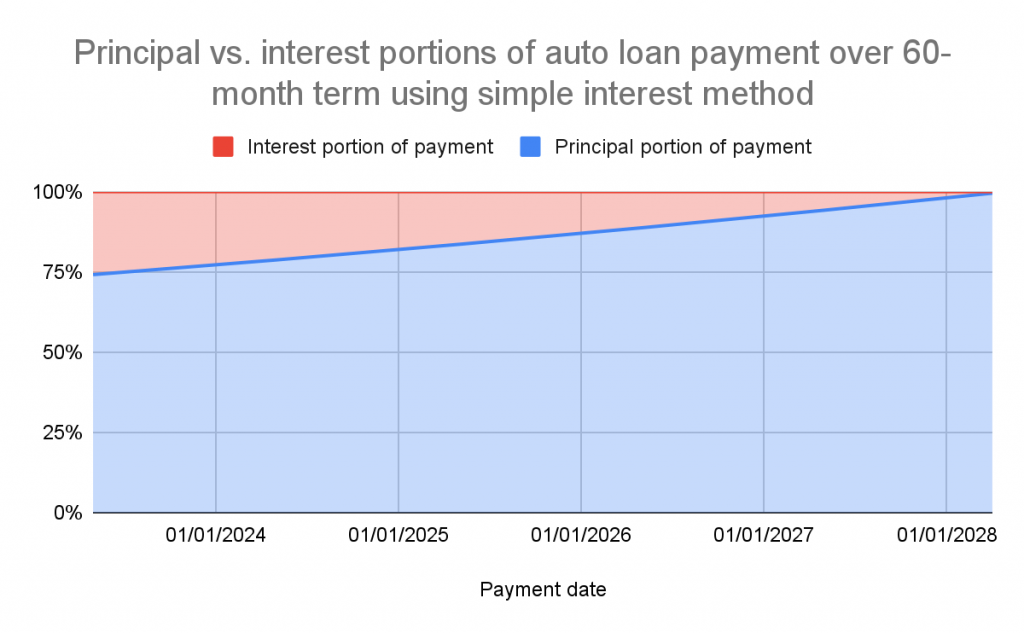
- Principal: The total cost of the car, minus any down payment.
- Interest: The fee charged by the lender for borrowing the money.
- Term: The length of time you have to pay off the loan.
- Monthly Payment: The amount you'll pay each month, calculated based on the principal, interest, and term.
How Your Monthly Payment is Calculated
Car payments are typically calculated using a formula that includes the principal loan amount, the annual interest rate, and the loan term. Here's a simplified version of the formula:
M = P [ i(1 + i)^n ] / [ (1 + i)^n – 1 ]
Where:
Mis your monthly payment.Pis the principal loan amount.iis your monthly interest rate (annual interest rate divided by 12).nis the number of months in the loan term.
Example
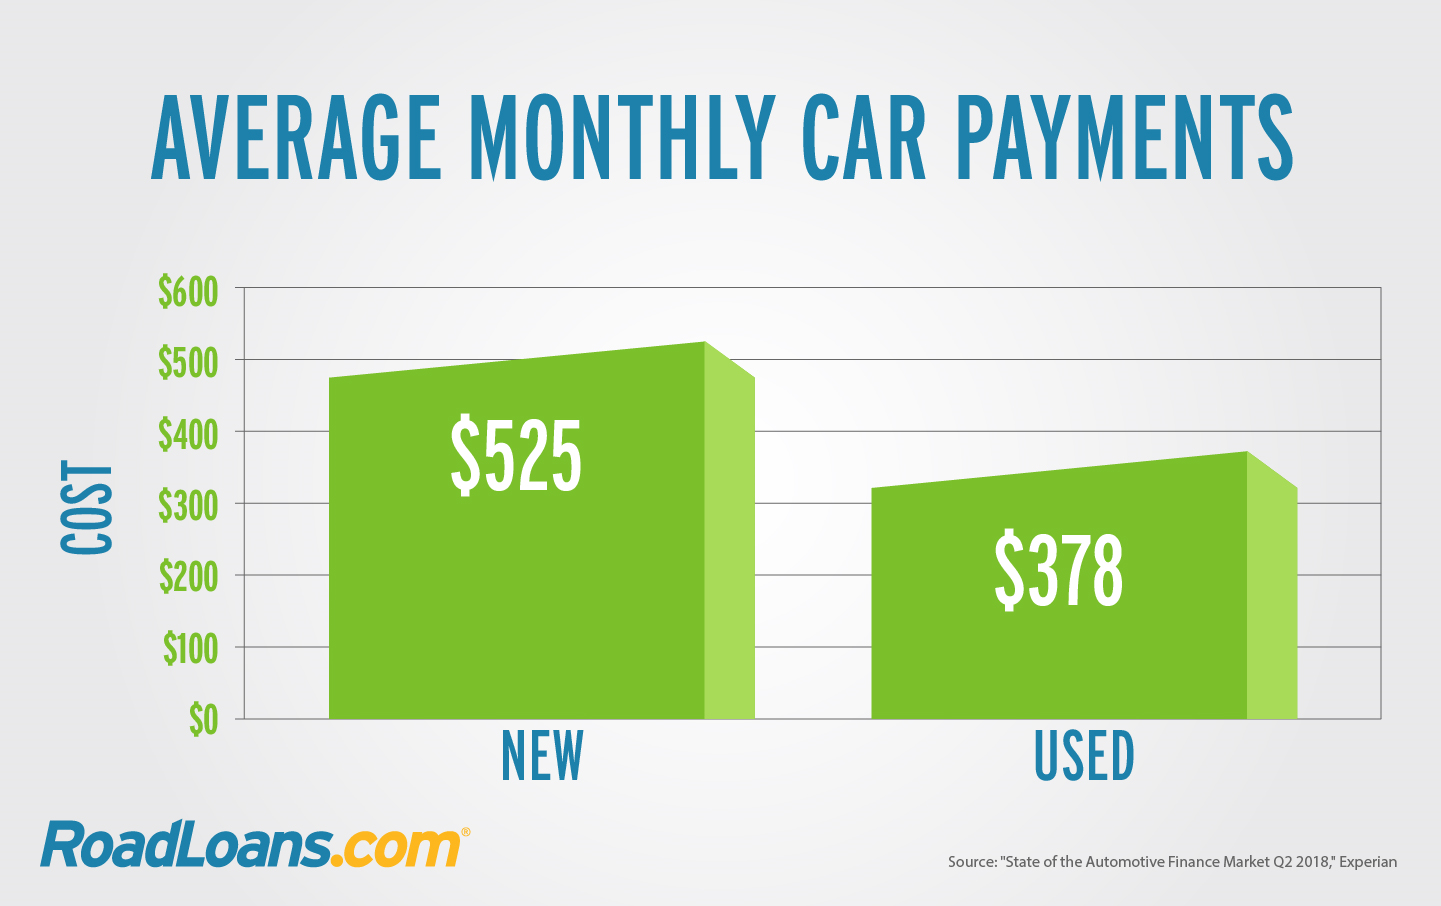
Let's say you're financing a $20,000 car with a 60-month term and an annual interest rate of 6%. Your monthly payment would be approximately $377.

| Principal (P) | Interest Rate (i) | Term (n) | Monthly Payment (M) |
|---|---|---|---|
| $20,000 | 0.005 (6% annual rate divided by 12) | 60 | $377 |
Factors Affecting Your Car Payment
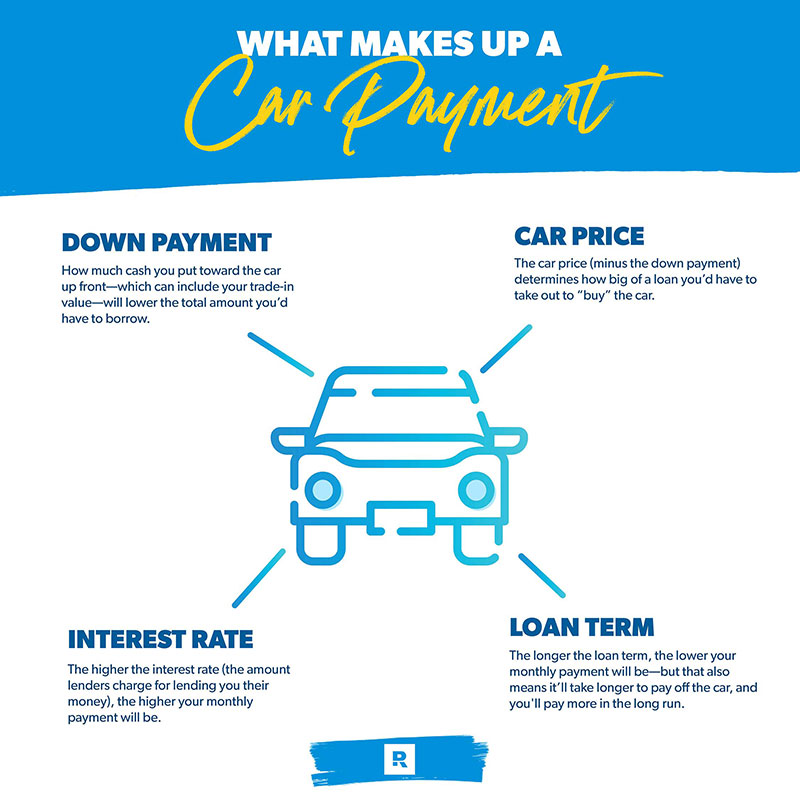
Several factors can influence your car payment:
- Car Price: The higher the car price, the higher your monthly payment.
- Down Payment: A larger down payment reduces the principal amount, lowering your monthly payment.
- Interest Rate: Lower interest rates mean lower monthly payments.
- Loan Term: Longer loan terms mean lower monthly payments, but you'll pay more in interest over time.
Tips for Managing Car Payments
Here are some tips to help you manage your car payments:
- Make sure your monthly payment is no more than 15% of your monthly gross income.
- Consider a shorter loan term to pay off your car faster and save on interest.
- Make extra payments when you can to reduce the principal and save on interest.
- Regularly review your budget to ensure you can comfortably afford your car payment.
Understanding how car payments work is the first step in making a smart decision about your next vehicle. By knowing the factors that influence your monthly payment and managing your finances wisely, you can drive off the lot with confidence.