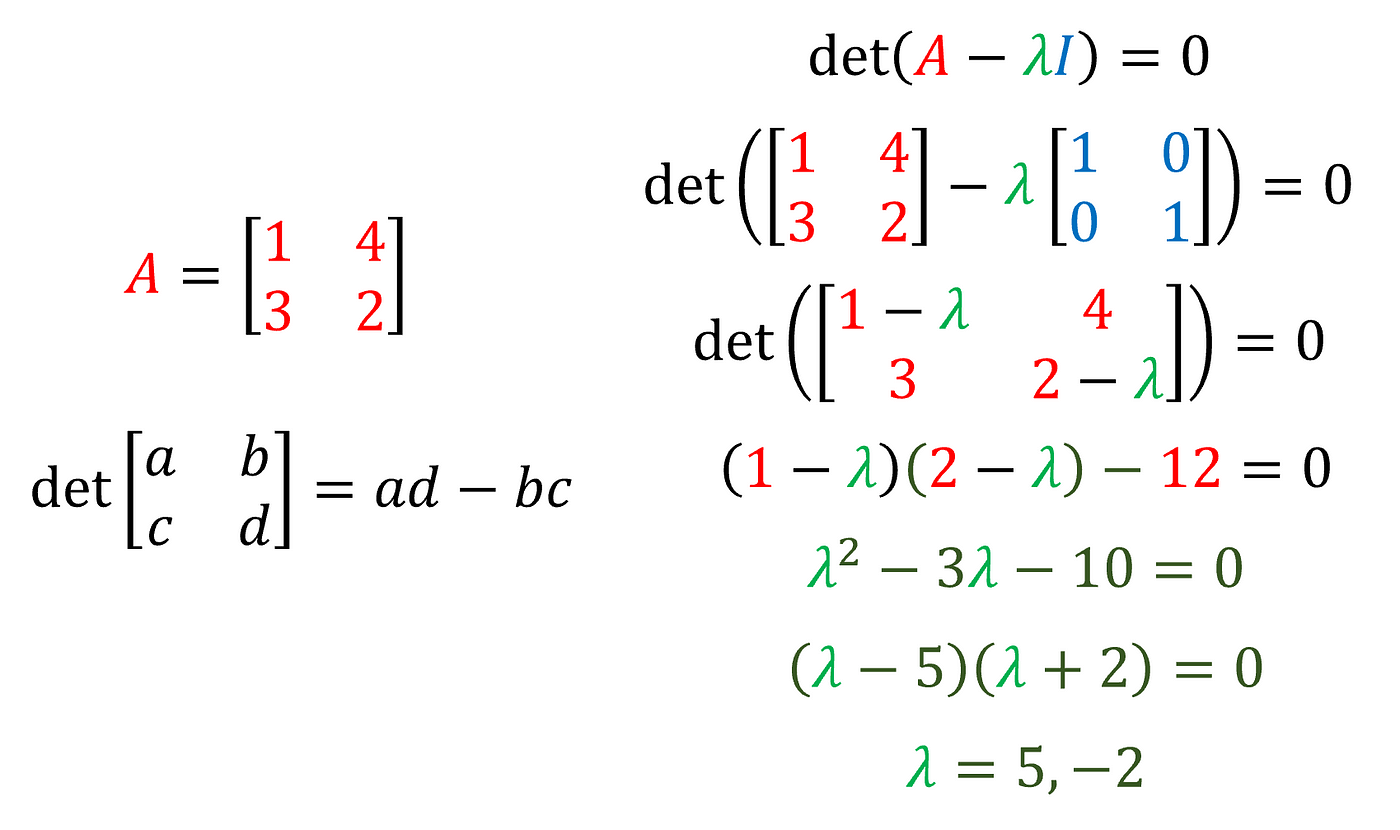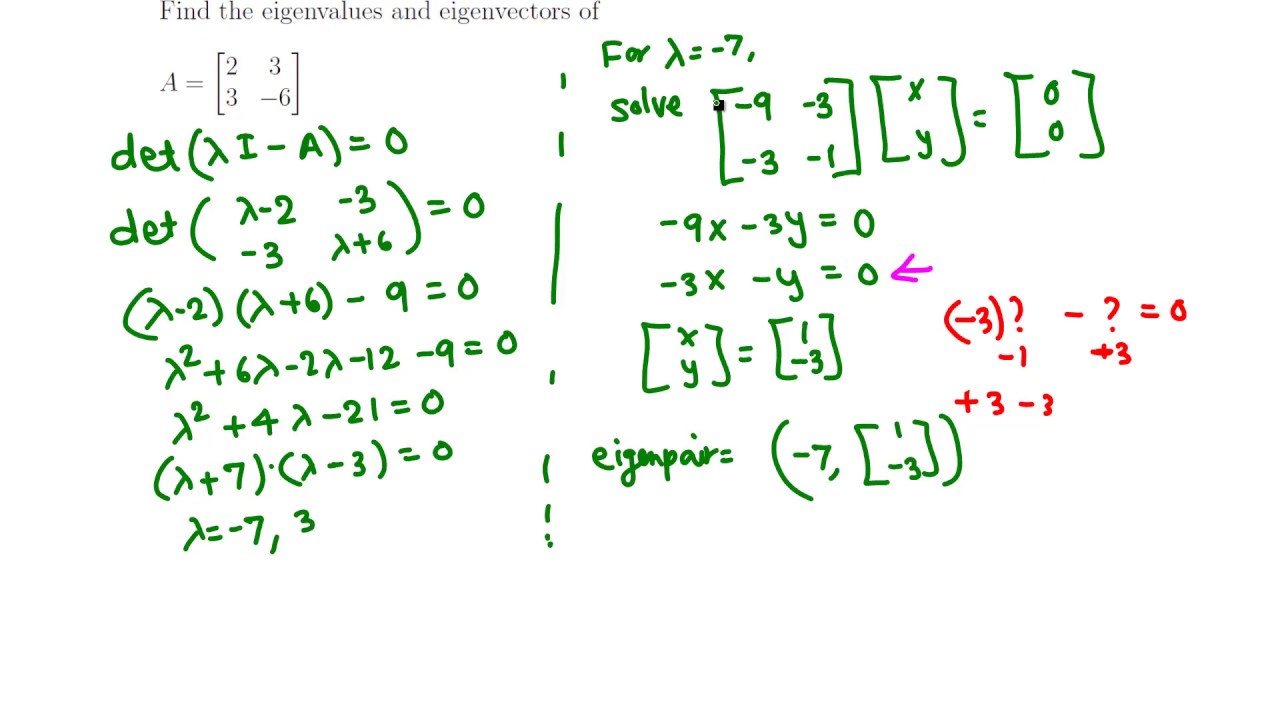Understanding Eigenvectors: A Comprehensive Guide
Eigenvectors are a fundamental concept in linear algebra, playing a crucial role in various fields such as machine learning, data analysis, and computer graphics. They represent the directions in which a linear transformation (or a matrix) stretches or compresses space. In this article, we'll delve into the world of eigenvectors, exploring their definition, how to calculate them, and their significance.
What are Eigenvectors?
Eigenvectors are special vectors that, when multiplied by a matrix, result in a new vector that is a scalar multiple of the original vector. In other words, if v is an eigenvector of a matrix A, and λ is a scalar, then:
A * v = λ * v

The scalar λ is called the eigenvalue associated with the eigenvector v. The term "eigen" comes from the German word "eigen" meaning "own," reflecting the fact that eigenvectors are the "special" or "own" vectors of the matrix.
Finding Eigenvectors: Step-by-Step
1. Find the Eigenvalues
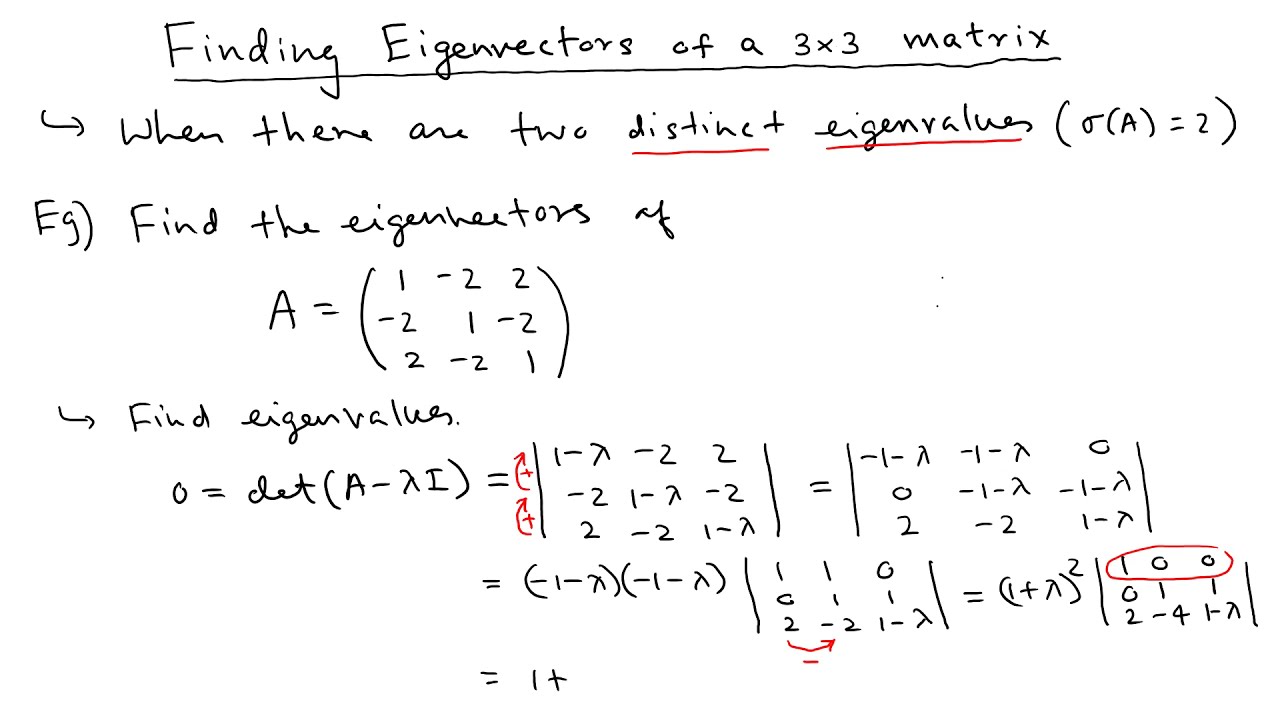
To find the eigenvectors, you first need to find the eigenvalues. The eigenvalues can be found by solving the characteristic equation of the matrix A:
det(A - λI) = 0
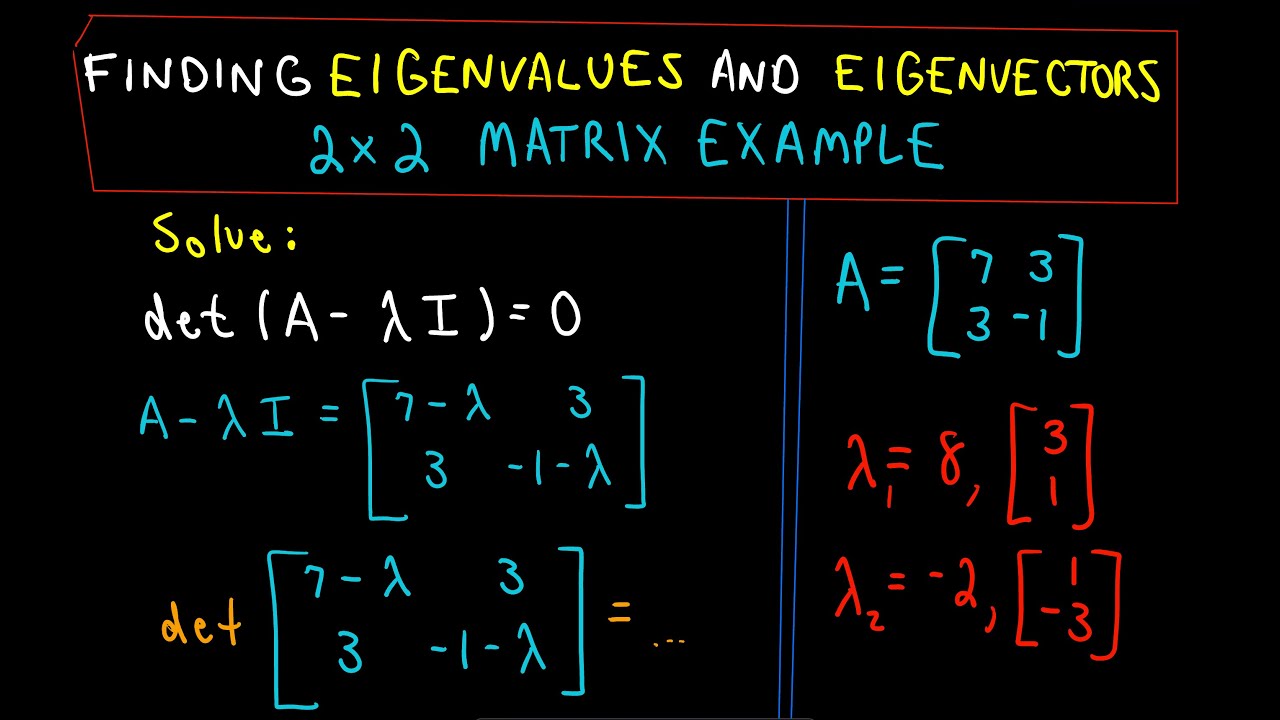
where I is the identity matrix, and det denotes the determinant. The roots of this equation are the eigenvalues of the matrix.
2. Find the Eigenvectors for Each Eigenvalue
Once you have the eigenvalues, you can find the corresponding eigenvectors. For each eigenvalue λ, solve the system of linear equations:
(A - λI) * v = 0
This system has a nontrivial solution (i.e., a solution that is not the zero vector) if and only if λ is an eigenvalue of A. The solutions to this system are the eigenvectors corresponding to the eigenvalue λ.
3. Normalize the Eigenvectors
Eigenvectors are not unique; they are determined only up to a scalar multiple. It's common to normalize the eigenvectors so that their Euclidean norm (length) is 1. This can be done by dividing the eigenvector by its magnitude.
Significance of Eigenvectors
Eigenvectors and eigenvalues have numerous applications in linear algebra and other fields. Some of their key roles include:
- Diagonalization of Matrices: If a matrix can be diagonalized, it means it can be written as a product of a matrix of its eigenvectors and a diagonal matrix of its eigenvalues. This can simplify calculations involving the matrix.
- Principal Component Analysis (PCA): In data analysis, PCA uses the eigenvectors of the covariance matrix to find the directions of maximum variance in the data. This is often used for dimensionality reduction.
- Eigenfaces in Computer Vision: In facial recognition, the eigenvectors of the covariance matrix of a set of face images are used to represent the images in a new basis, where the basis vectors are the eigenfaces.
Eigenvectors and eigenvalues are powerful tools in linear algebra, with a wide range of applications. Understanding how to find and interpret them is a crucial part of mastering linear algebra.