Understanding Credit Slips: A Comprehensive Guide
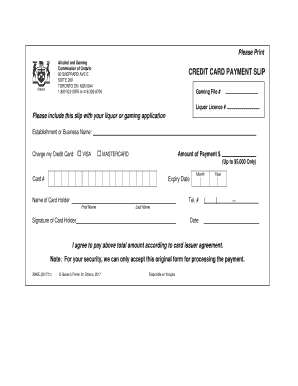
A credit slip, also known as a credit memo, is a financial document used to record and track adjustments to a customer's account. It's essentially a way to credit back an amount to a customer, often due to a return, exchange, or other adjustments. Here, we'll delve into the world of credit slips, exploring their purpose, how they work, and their significance in accounting and business operations.
Why Use Credit Slips?
Credit slips serve several crucial purposes in a business environment:
- Customer Satisfaction: They allow businesses to rectify errors or issues, maintaining customer satisfaction and loyalty.
- Accounting Accuracy: They help maintain accurate financial records by ensuring that transactions are correctly reflected in the accounts.
- Inventory Management: They aid in tracking inventory by accounting for returned or exchanged items.
How Credit Slips Work
Credit slips typically include the following information:
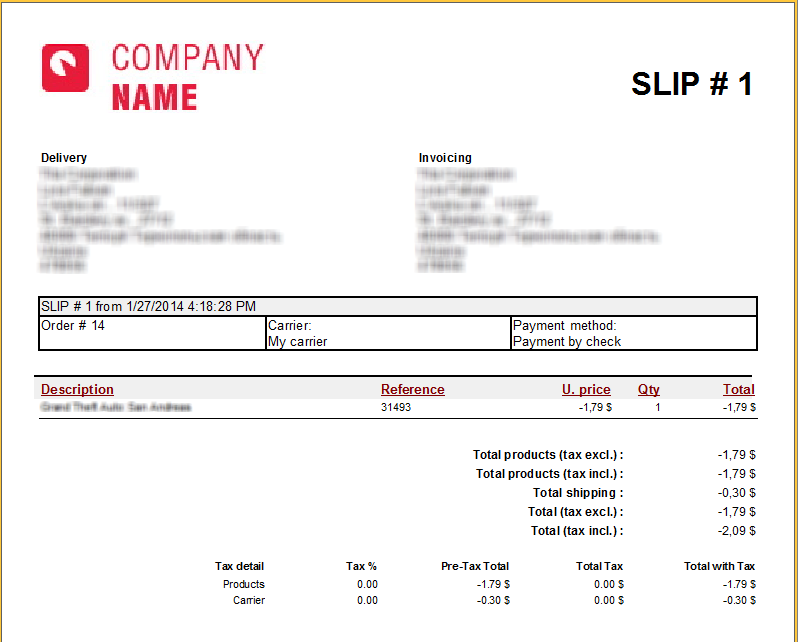
- Invoice or transaction number
- Date of the original transaction
- Customer's name and account number
- Description of the item or service
- Original price and quantity
- Credit amount and reason (e.g., return, exchange, adjustment)
The credit slip is then applied to the customer's account, reducing the amount they owe. In accounting, this is typically recorded as a journal entry, with the credit slip's details reflecting the adjustment.
Types of Credit Slips
Credit slips can be used for various purposes, including:
- Returns: When a customer returns a product, a credit slip is issued to refund the purchase price.
- Exchanges: If a customer exchanges one product for another, a credit slip is used to adjust the transaction.
- Adjustments: Credit slips can also be used to correct errors in pricing, quantity, or other aspects of a transaction.
Credit Slips vs. Debit Memos
While credit slips are used to credit back an amount to a customer, debit memos serve the opposite purpose. They are used to charge a customer for additional amounts, such as late fees, restocking fees, or other charges. Understanding the difference between the two is crucial for maintaining accurate financial records.

The Role of Credit Slips in Accounting
In accounting, credit slips are typically recorded using the following journal entry:
| Account | Dr | Cr |
|---|---|---|
| Sales Returns and Allowances | X | |
| Accounts Receivable | X |
This entry reduces the amount owed by the customer (Accounts Receivable) and increases the sales returns and allowances (an expense account). This helps maintain the accuracy of the financial statements.