Strategic Mortgage Payoff: Is Paying Extra Principal Worth It?
When it comes to managing your mortgage, you might wonder if paying extra principal is a sound financial decision. The short answer is: it depends. While it can help you save on interest and pay off your home faster, it's not always the best use of your money. Let's delve into the pros, cons, and factors to consider when deciding whether to pay extra principal on your mortgage.
Understanding Mortgage Amortization
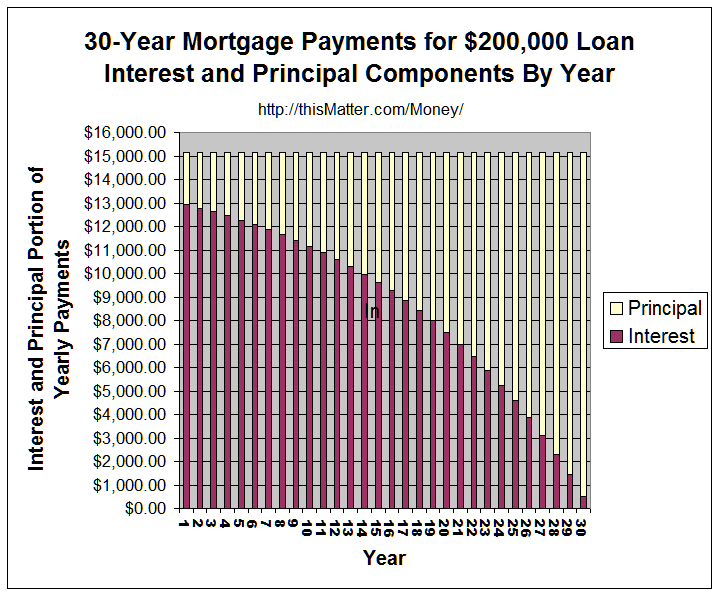
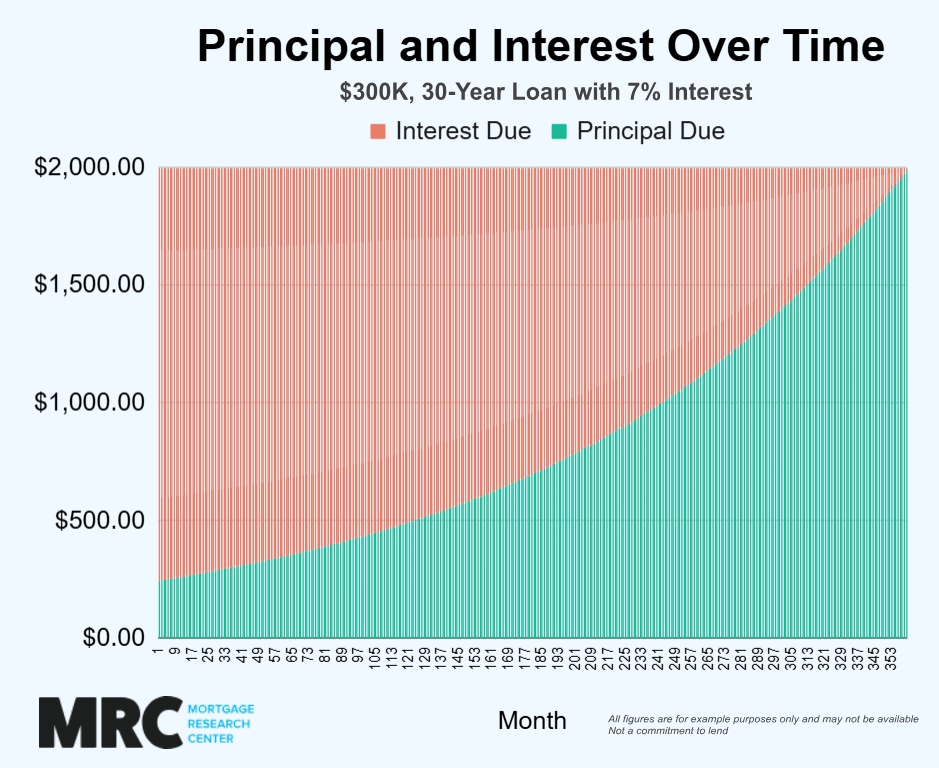
Before we dive into the details, it's crucial to understand how mortgages work. Most mortgages are amortized over 30 years, meaning your monthly payment is divided into interest and principal. Each payment reduces your principal balance, but the amount that goes towards interest is highest in the early years of your loan.
Example of Mortgage Amortization
| Month | Interest | Principal | Total Payment | Remaining Balance |
|---|---|---|---|---|
| 1 | $1,000 | $200 | $1,200 | $348,800 |
| 12 | $834 | $366 | $1,200 | $347,434 |
| 24 | $667 | $533 | $1,200 | $345,901 |
As you can see, in the first year, only $2,400 went towards your principal, while $12,000 went towards interest. However, by the second year, the amount going towards principal increased to $4,400, with $9,600 going towards interest.
Benefits of Paying Extra Principal
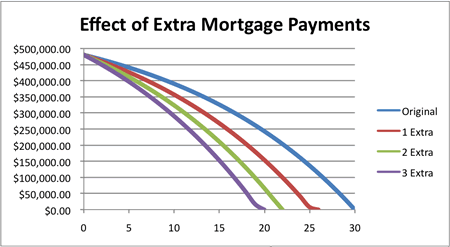
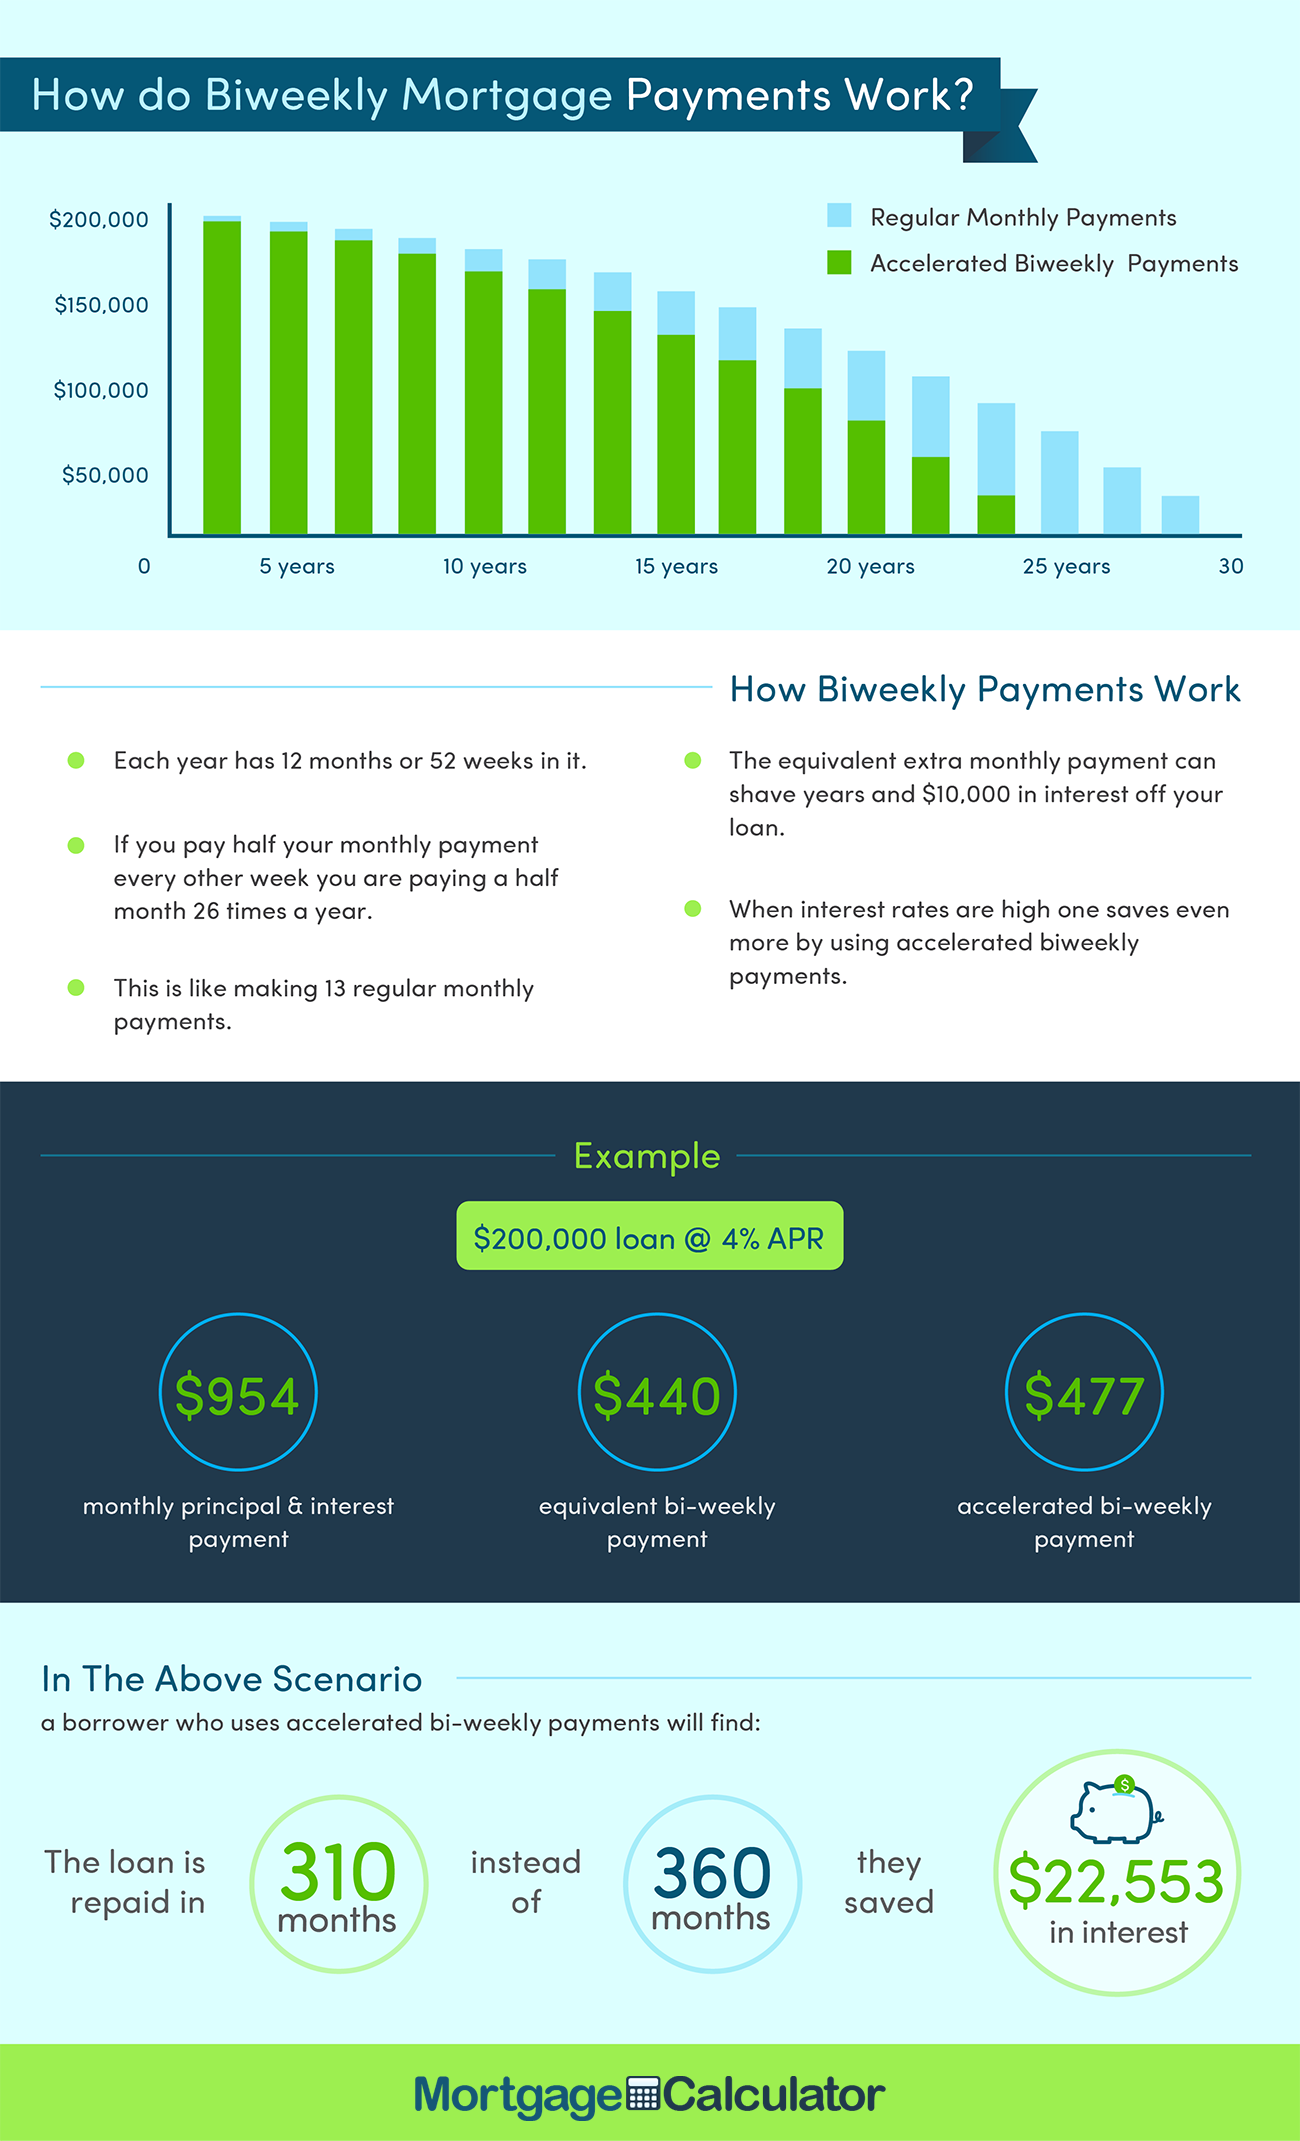
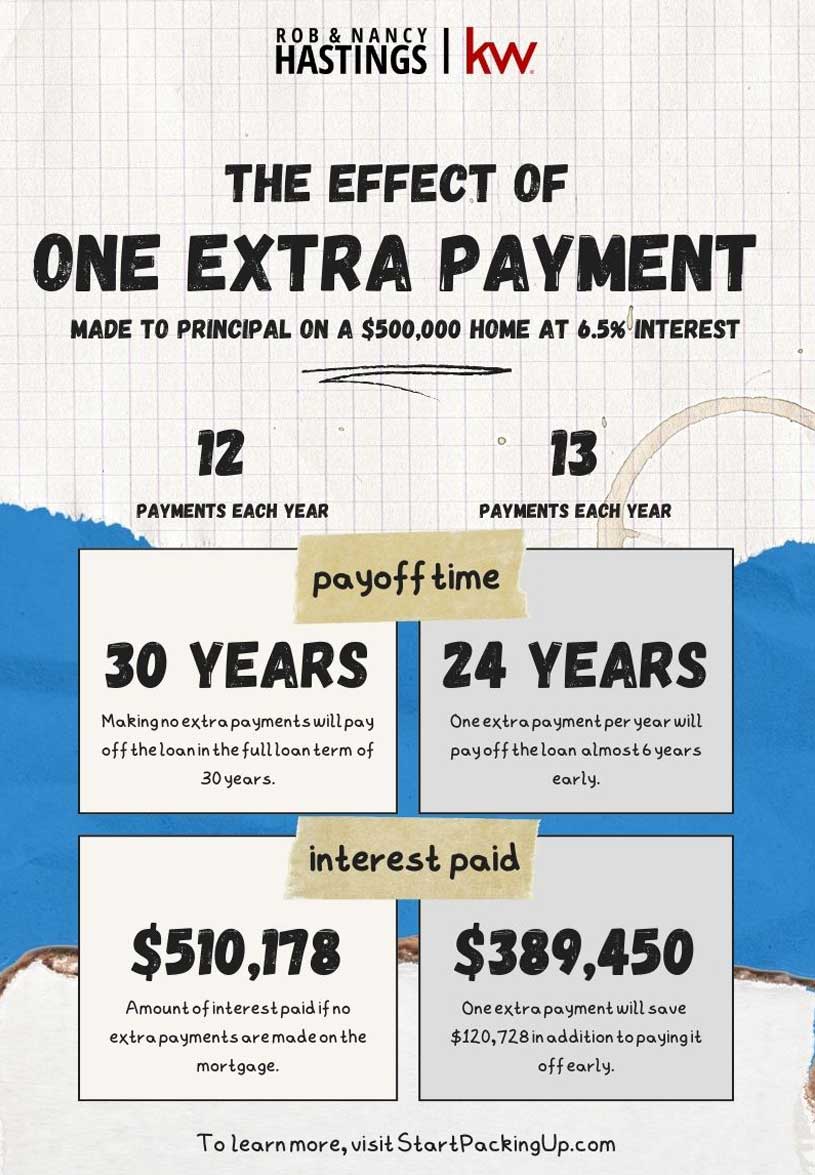
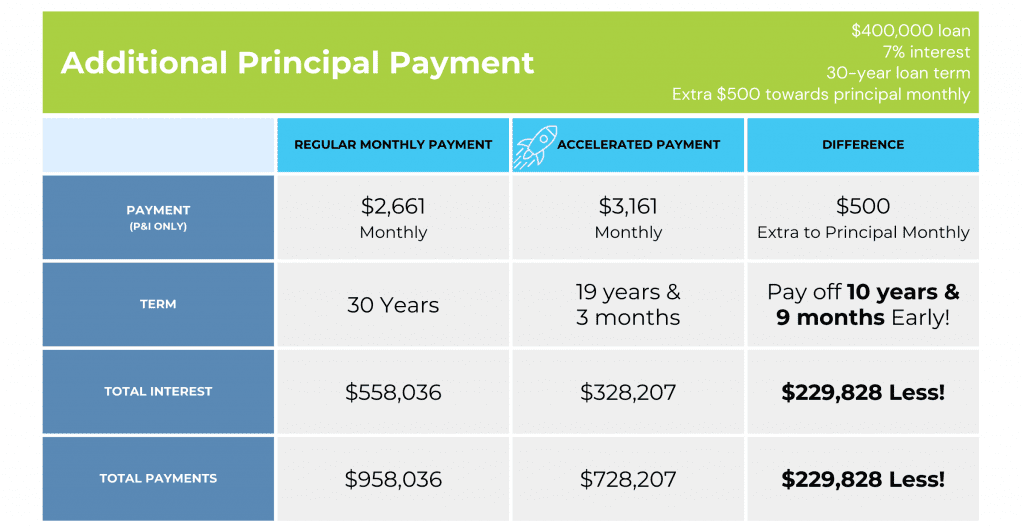
- Save on Interest: By paying extra principal, you reduce the amount of interest you'll pay over the life of your loan. This can result in significant savings, especially for those with high-interest rates.
- Pay Off Your Home Faster: Making extra payments can help you pay off your mortgage faster, potentially allowing you to own your home free and clear sooner.
- Increased Financial Flexibility: A paid-off mortgage can provide peace of mind and increased financial flexibility, allowing you to redirect those funds towards other financial goals, such as retirement or your children's education.
Drawbacks of Paying Extra Principal
- Opportunity Cost: Money used to pay down your mortgage could be invested elsewhere, potentially earning a higher return. This is especially true if you have a low-interest rate mortgage.
- Liquidity: Paying down your mortgage reduces your liquid assets. It's important to maintain an emergency fund and consider your other financial obligations before making extra mortgage payments.
- Prepayment Penalties: Some mortgages have prepayment penalties. Be sure to check your loan agreement to see if you'll incur any fees for paying off your loan early.
When Does It Make Sense to Pay Extra Principal?
Paying extra principal can be a smart financial move in several scenarios:
- You have a high-interest rate mortgage.
- You have extra cash on hand and no high-interest debt, like credit cards.
- You're planning to stay in your home for an extended period.
- You want to build equity in your home faster.
Alternatives to Paying Extra Principal
If you're unsure about paying extra principal, consider these alternatives:
- Invest the Money: If you have a low-interest rate mortgage, you might earn a higher return by investing the money instead.
- Build an Emergency Fund: Before paying extra on your mortgage, ensure you have an emergency fund covering 3-6 months' worth of living expenses.
- Pay Off High-Interest Debt: If you have high-interest debt, like credit cards, paying that off first can save you more money in the long run.
Ultimately, whether or not to pay extra principal on your mortgage depends on your unique financial situation. It's a good idea to consult with a financial advisor or use a mortgage payoff calculator to see how extra payments could impact your financial goals.
Remember, the key to making informed financial decisions is to understand your options and consider your personal circumstances. By doing so, you can make the best choice for your financial future.