Understanding Wrap-Around Mortgage Loans: A Comprehensive Guide
In the dynamic world of real estate finance, one type of loan stands out for its unique structure and flexibility: the wrap-around mortgage loan. If you're a homeowner, investor, or simply curious about innovative financing options, this guide will demystify wrap-around mortgages, their benefits, drawbacks, and how they work.
What is a Wrap-Around Mortgage Loan?
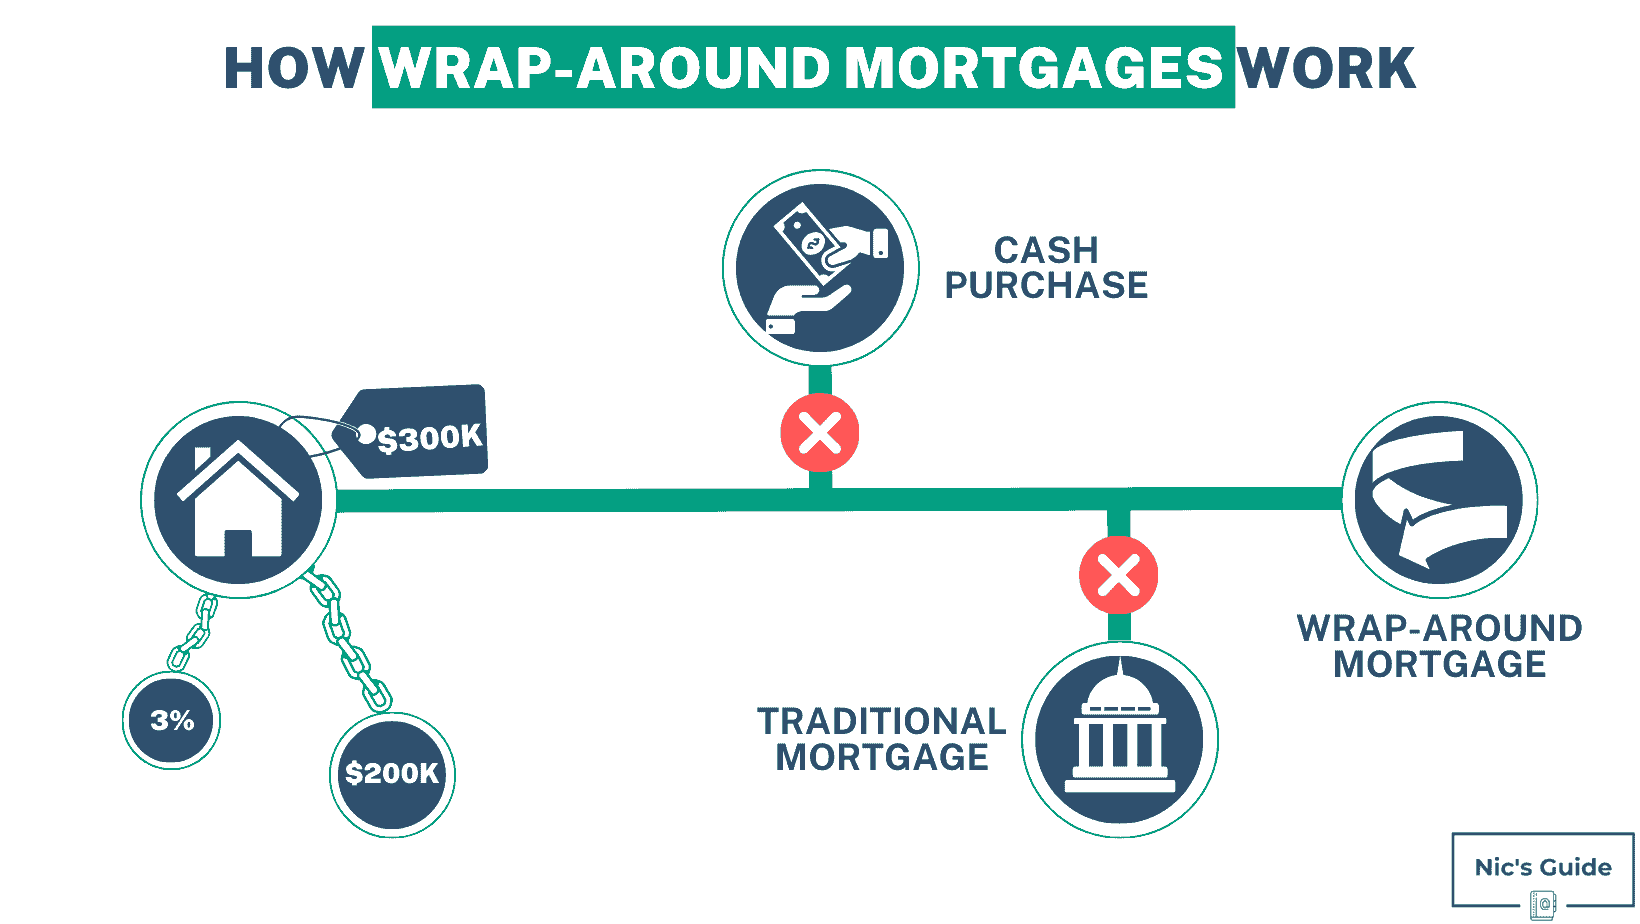
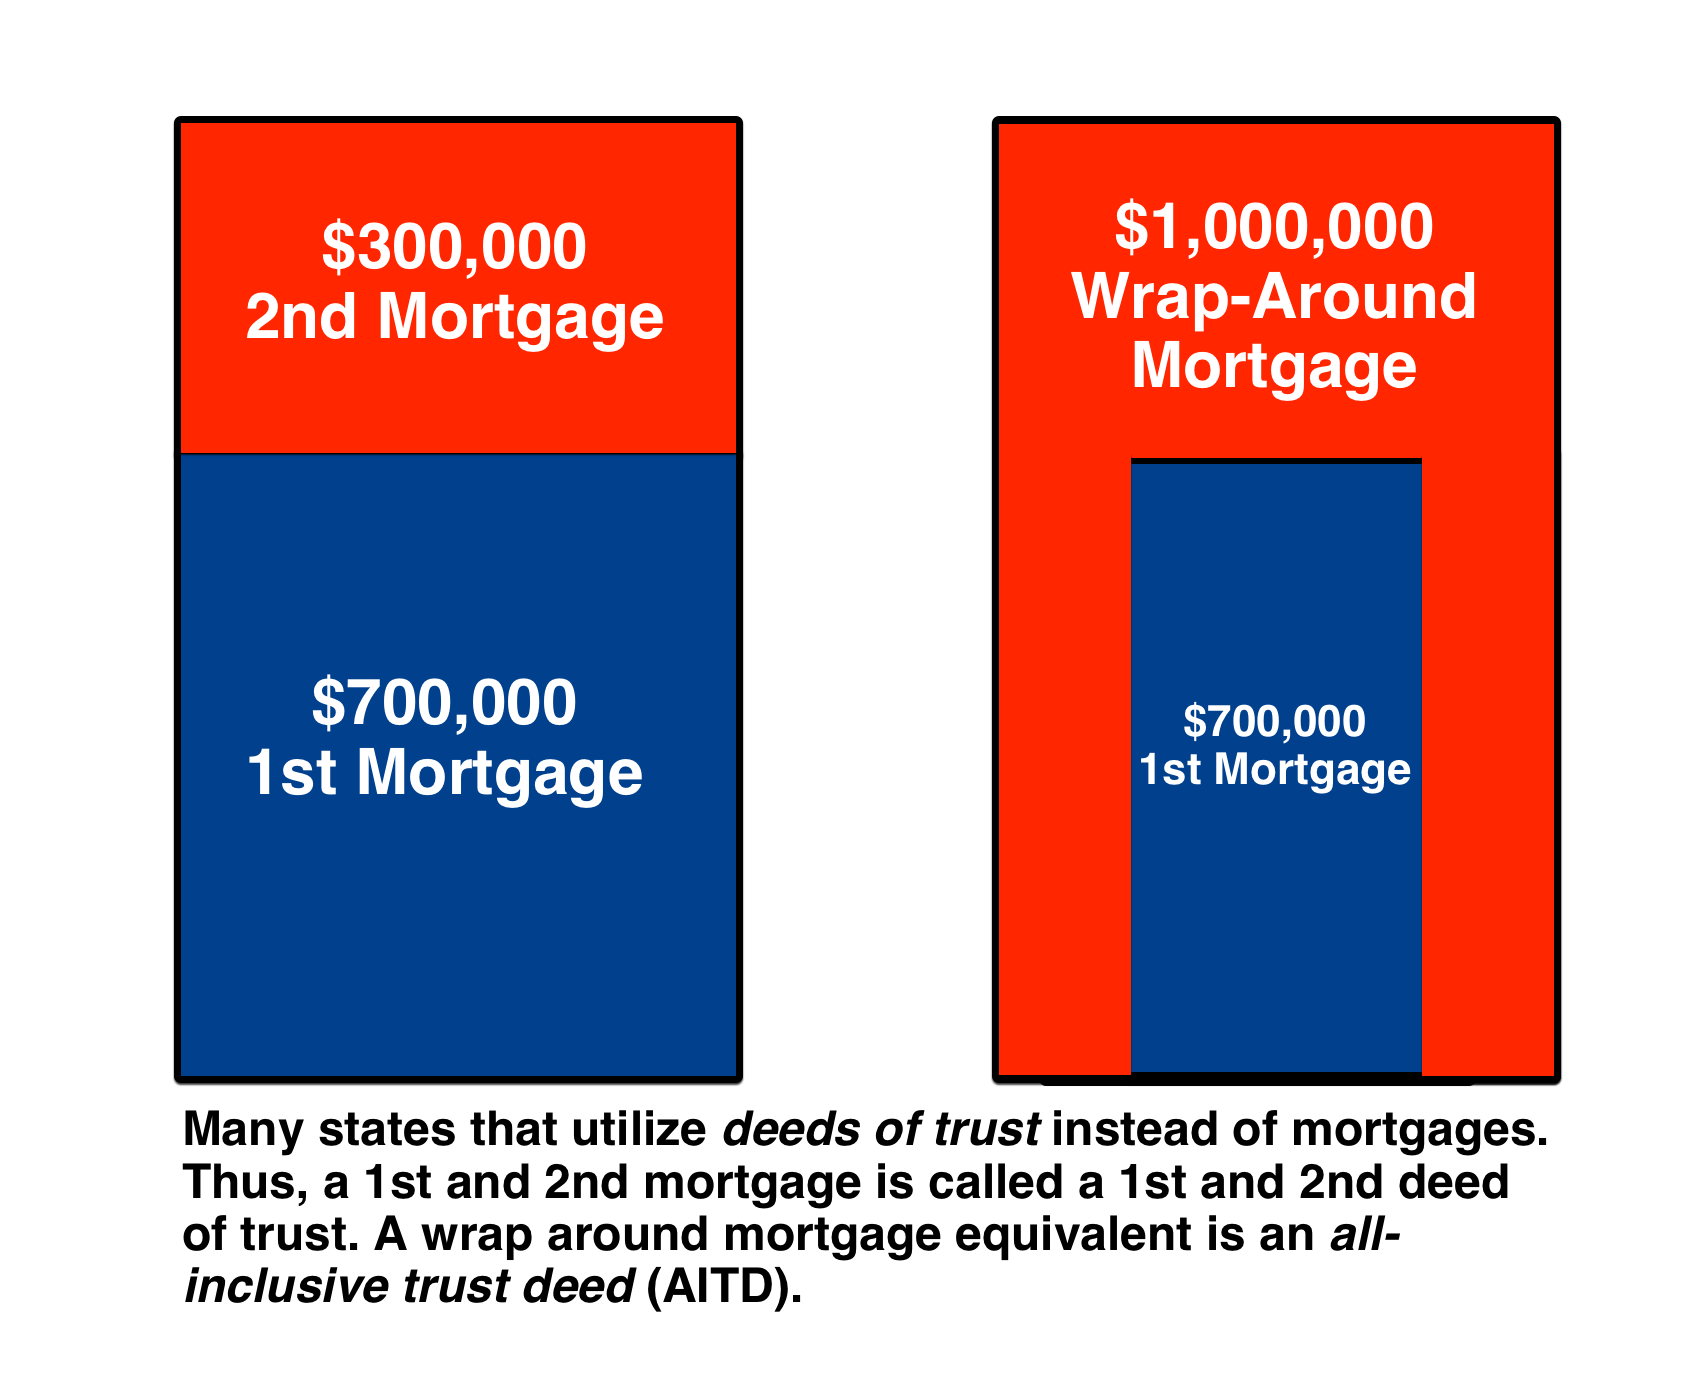
A wrap-around mortgage loan is a type of secondary financing where a new loan is made to a borrower, using the existing mortgage as the underlying lien. The new lender "wraps around" the existing mortgage, hence the name. The new loan pays off the existing mortgage, and the borrower then makes payments to the new lender, who in turn pays the original lender.
How Does a Wrap-Around Mortgage Loan Work?
To understand the mechanics of a wrap-around mortgage, let's break down the process:

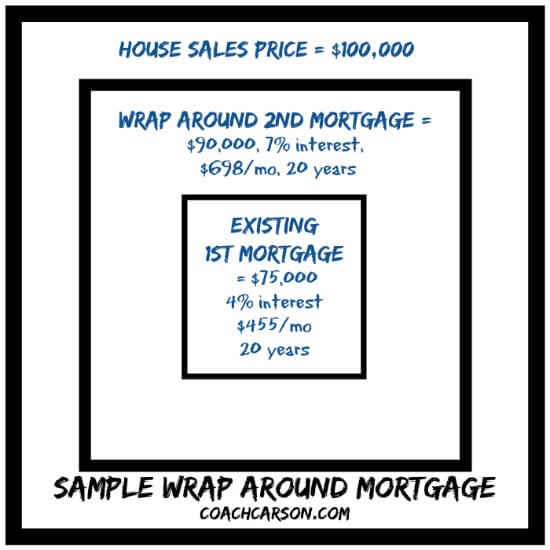
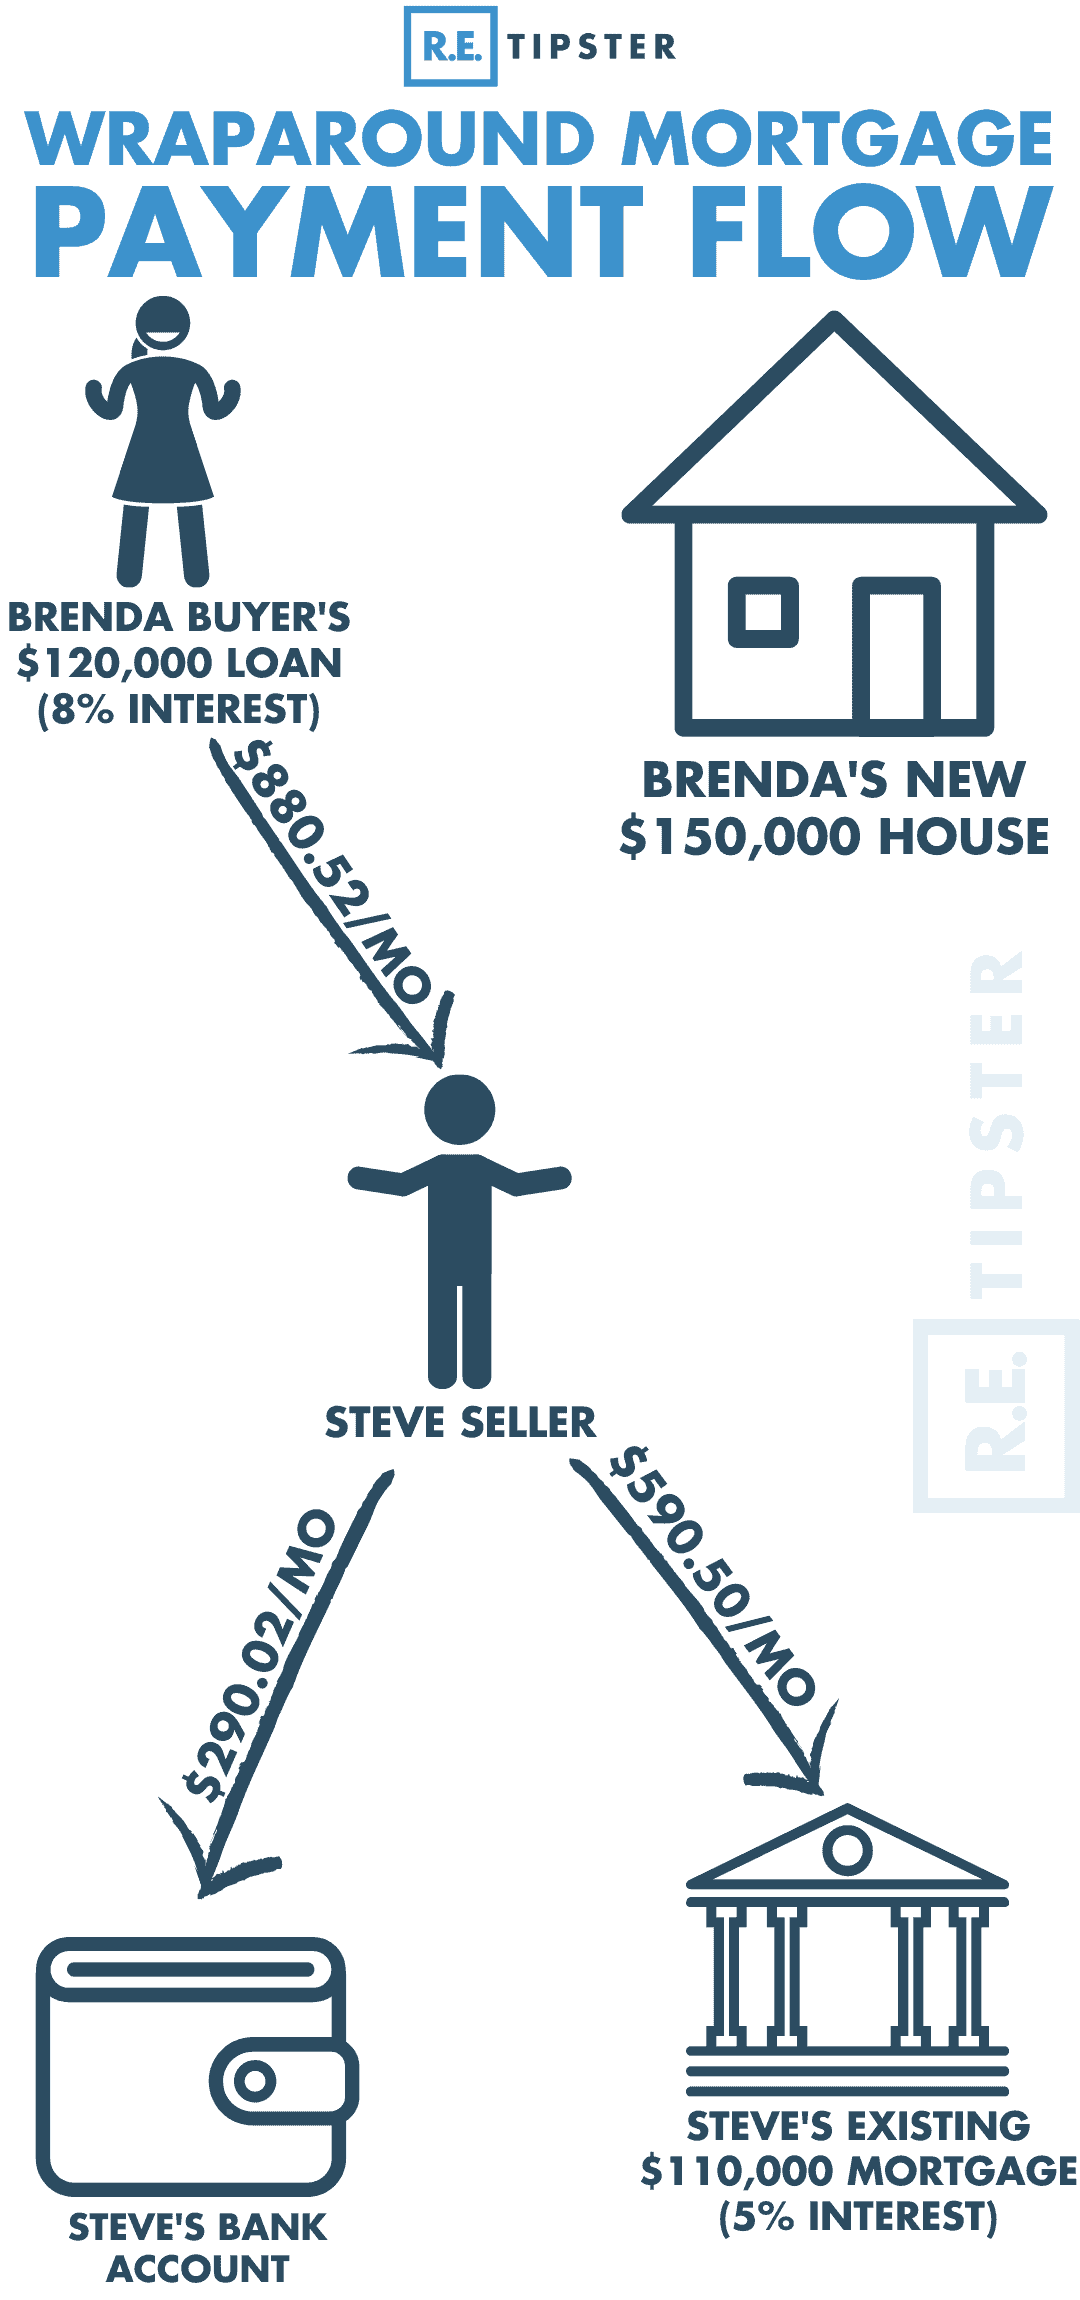
- Existing Mortgage: Assume you have an existing mortgage with a balance of $100,000, and your monthly payment is $500.
- Wrap-Around Mortgage: You secure a new loan for $150,000 (including the $100,000 to pay off your existing mortgage). Your new monthly payment is $800.
- Payment Structure: You pay $800 to the new lender each month. The new lender then pays $500 to the original lender and keeps the difference ($300) as interest.
Benefits of Wrap-Around Mortgage Loans
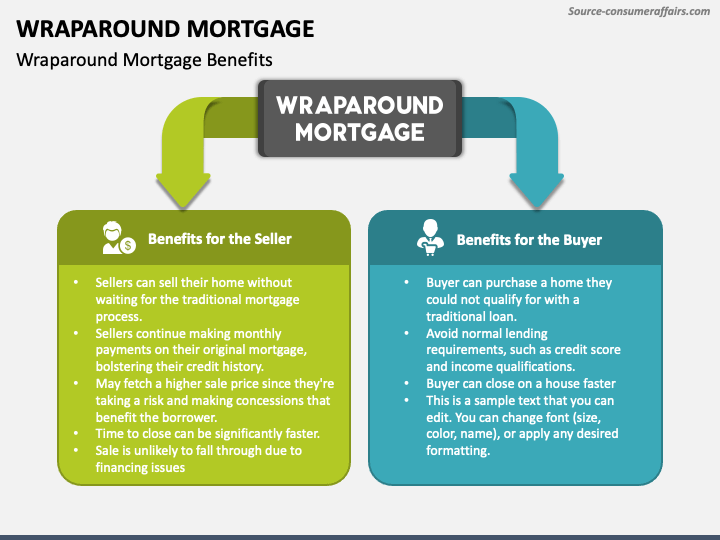
Wrap-around mortgages offer several advantages, particularly for investors and homeowners looking to leverage their property's equity:
- **Access to Cash:** Wrap-around mortgages allow homeowners to tap into their home's equity without selling the property.
- **Flexible Terms:** Since wrap-around mortgages are typically private loans, they can offer more flexible terms than traditional mortgages.
- **Creative Financing:** For real estate investors, wrap-around mortgages can be a tool for creative financing, enabling them to purchase properties with little or no money down.
Drawbacks and Risks of Wrap-Around Mortgage Loans
While wrap-around mortgages offer unique benefits, they also come with potential drawbacks and risks:
- **Higher Interest Rates:** Wrap-around mortgages often come with higher interest rates than traditional mortgages, as they carry more risk for the lender.
- **Complexity:** The structure of wrap-around mortgages can be complex, making them difficult to understand and manage.
- **Risk of Foreclosure:** If the borrower defaults on the new loan, both the original mortgage and the wrap-around loan could go into foreclosure.
Table: Wrap-Around Mortgage Loan Example
| Existing Mortgage | Wrap-Around Mortgage | Borrower's Payment | New Lender's Payment |
|---|---|---|---|
| $100,000 | $150,000 | $800 | $500 |
In this example, the borrower accesses $50,000 in cash while increasing their monthly payment by $300.
Conclusion: Wrap-Around Mortgages as a Strategic Financing Tool
Wrap-around mortgage loans offer a creative and flexible financing option for homeowners and investors looking to leverage their property's equity. However, their complexity and risks necessitate careful consideration and thorough understanding. Before pursuing a wrap-around mortgage, consult with a financial advisor or real estate professional to determine if it's the right fit for your financial goals and risk tolerance.