"What is the Source Document for a Credit Sale?"
When running a business that extends credit to customers, proper documentation is essential—not just for internal tracking, but for legal protection, tax compliance, and financial reporting. One foundational element in this process is the source document for a credit sale. Understanding what it is, why it matters, and how it integrates into your accounting workflow can save your business from costly errors and audits.
What Is a Credit Sale?

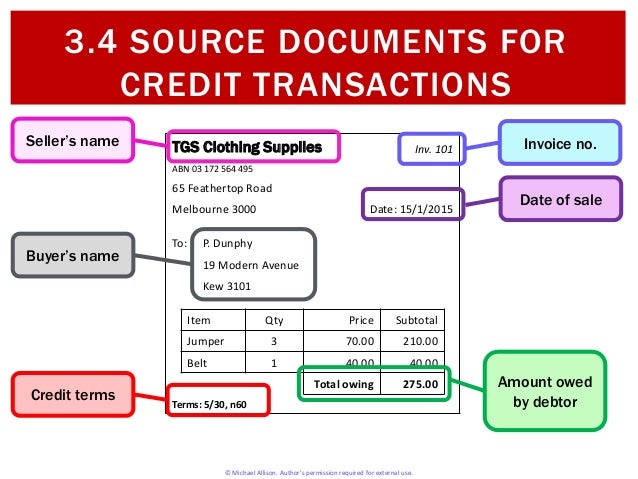
A credit sale occurs when goods or services are delivered to a client before payment is made. Instead of receiving cash immediately, the seller records an accounts receivable entry while the buyer agrees to pay at a later date. This transaction requires more than a handshake or verbal agreement—it requires a formal record that captures all relevant details.
Purpose of the Source Document

The source document for a credit sale serves as the initial record of the transaction. It is the first point of entry in the accounting system and provides evidence that a sale has occurred under specific terms and conditions. This document includes details such as the date, customer name, item descriptions, amounts, and payment terms. Without it, any subsequent journal entries or invoices would lack verifiable proof.
Key Components of a Source Document for a Credit Sale

To ensure accuracy and compliance, the source document must contain:
- Date of the transaction
- Name and contact information of the customer
- Description of goods or services provided
- Agreed-upon unit price and total amount
- Payment terms (e.g., net 30 days, due upon receipt)
- Authorization signatures or digital approvals
Types of Source Documents Used in Credit Sales

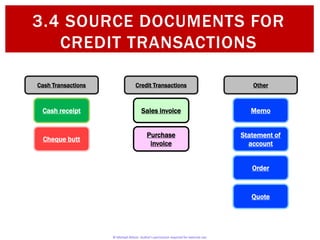
Depending on the business size and industry, different types of documents can serve as the source for a credit sale. Here are the most common ones:
| Document Type | Description |
|---|---|
| Invoice | The most common source; itemizes services or goods and sets payment expectations. |
| Sales Order | Confirms the buyer’s intent to purchase and includes pricing and delivery details. |
| Purchase Order | Used when the buyer initiates and provides reference for follow-up invoicing. |
| Delivery Note / Receipt | Confirms that goods have been received by the buyer. |
Why Accuracy in Source Documents Matters

Errors or omissions in the source document can propagate through your entire financial reporting chain. Incorrect amounts, missing dates, or incomplete customer information can lead to disputes, delayed payments, and even legal issues. Proper documentation ensures that entries into your accounting software are accurate and auditable.
Source Document vs. Journal Entry






It’s important not to confuse the source document with journal entries made in your ledger or accounting software. The source document initiates the transaction. The journal entry records it post-review. This separation creates a clear audit trail: auditors and accountants can trace any ledger entry back to its original document.
Best Practices for Managing Source Documents
To maintain compliance and operational efficiency, follow these practices:
- Issue a document for every credit sale immediately upon agreement.
- Use consistent templates with required fields filled.
- Store documents securely—digitally, with backups and access controls.
- Review entries against source documents regularly.
- Train staff on proper documentation procedures.
Accounting Impact of Credit Sale Documentation
The source document for a credit sale directly affects your financial statements. When the sale is made:
- Debit Accounts Receivable
- Credit Revenue (or Sales)
Upon receipt of payment later:
- Debit Cash or Bank
- Credit Accounts Receivable
This two-step process reflects the value of goods/services inflow and, eventually, the cash settlement.
Role in Audits and Compliance
During audits, internal or external reviewers rely heavily on original source documents. Discrepancies between ledgers and documents can trigger further investigation. Compliance frameworks, tax authorities, and legal teams all expect clean, verifiable source records.
Conclusion
Understanding and maintaining proper source documents for credit sales is more than a bookkeeping step—it’s a critical component of financial integrity, operational reliability, and legal safeguarding for any business involved in credit transactions.