Financing a tiny house requires a shift in perspective from traditional home buying. Unlike a standard residential property, these compact dwellings often fall into a financial gray area that challenges conventional lending institutions. Because of their size and mobility, they are frequently classified as personal property or recreational vehicles rather than real estate, which means standard 30-year mortgages may not apply. Understanding this fundamental distinction is the first step in navigating the unique financial landscape required to make tiny house ownership a reality.
To secure funding, you must first determine exactly what type of tiny house you intend to build or purchase. The classification of your dwelling dictates the type of financing available to you. If the structure is built on a permanent foundation and connected to municipal utilities, it may qualify for a traditional mortgage depending on zoning laws and bank policies. Conversely, if the house is on wheels, you will likely be looking at an RV loan, a personal loan, or a specialized lender that deals with alternative housing. Clarifying this upfront saves time and prevents disappointment during the application process.
Traditional Financing: Challenging but Possible
While difficult, securing traditional financing is not impossible, but it hinges on treating the tiny house as real estate rather than a vehicle. This typically requires placing the house on a permanent foundation and ensuring the land and structure are appraised separately. Some banks, particularly smaller community institutions or credit unions, may consider a standard mortgage if the project meets their criteria for property permanence. However, you will likely face higher interest rates and larger down payments, as these loans are often viewed as non-standard by major banking institutions.

The Role of the Foundation
The foundation is the single most critical factor in determining financing eligibility. A temporary foundation, such as skids or a trailer, will reclassify the project as a mobile unit, immediately disqualifying it from standard mortgage options. A proper foundation involves concrete piers or a slab that anchors the structure permanently to the land. Banks need this security to validate the asset as real property, which justifies the risk associated with the loan. Without this permanence, you limit your options to lenders who specialize in chattel or recreational loans.
Alternative Financing: RV and Personal Loans
For those embracing the mobile lifestyle, financing usually comes in the form of an RV loan or a personal loan. RV loans are offered by banks, credit unions, and specialized recreational vehicle lenders, and they function similarly to car loans. The tiny house on wheels acts as collateral, and the loan term is typically shorter than a standard mortgage, often ranging from 5 to 20 years. Interest rates vary significantly based on credit score, the age of the unit, and the loan-to-value ratio.
- RV Loans: Ideal for mobile units; secured by the asset; terms vary.
- Personal Loans: Unsecured debt; higher interest rates; faster approval.
- Home Equity Lines of Credit (HELOC): Requires existing home equity; offers flexible borrowing.
- Seller Financing: Negotiating directly with the builder or seller; potential for flexible terms.
Creative and Community-Based Solutions
When traditional financial institutions fall short, many successful tiny house projects rely on creative alternative strategies. One of the most effective methods involves leveraging a "house hack," where you finance a primary residence that generates rental income (such as a duplex) and use that cash flow to fund the construction of your tiny house on the property. Another popular route is community lending circles or crowdfunding, where friends, family, and supporters contribute small amounts of capital in exchange for equity, rent, or simply the satisfaction of backing a sustainable project.

Budgeting and Savings Strategies
Regardless of the financing method chosen, rigorous budgeting remains the most powerful tool in a tiny house journey. Because the structure itself is often significantly cheaper than a traditional home, the goal should be to minimize debt and maximize cash reserves. Aim to save 20% to 50% of the total project cost as a down payment to avoid private mortgage insurance (PMI) or to secure better loan terms. Additionally, allocating funds for off-grid utilities such as solar panels, water tanks, and septic systems is essential, as these are rarely included in base construction quotes and impact long-term affordability.
| Financing Type | Best For | Typical Interest Rate Range | Down Payment |
|---|---|---|---|
| Traditional Mortgage | Fixed, permanent foundation homes | 6% – 8% | 20% – 30% |
| RV Loan | Wheeled, mobile units | 7% – 12% | 10% – 20% |
| Personal Loan | Small builds or used units | 10% – 36% | 0% – 10% |
| Home Equity Loan | Existing homeowners with equity | 5% – 8% | 0% |
The Long-Term Financial Perspective
Finally, viewing a tiny house as a long-term investment rather than a short-term trend is crucial for sustainable financing. The goal of minimizing housing costs is to redirect capital toward savings, travel, or entrepreneurial ventures. When evaluating lenders, look beyond the monthly payment and consider the total cost of ownership, which includes insurance, maintenance, and potential land rental fees if you are not purchasing a lot. By treating the tiny house as a tool for financial freedom rather than a status symbol, you position yourself to make choices that align with your long-term economic health.
24.11.2023 ... Find a local tiny builder that offers tiny home financing. The interest rates are usually a bit higher but they are doing 25 year loans on Tinys ...
How To Finance A Tiny House | Tiny house plans, Building a tiny house ...
29.07.2025 ... Looking to buy a tiny home? Discover the best tiny-house loan options, including personal loans, RV loans, and builder financing.
How to finance a tiny home on wheels – Artofit
Online lenders offer personal loans that can finance all or part of a tiny house purchase. Loan repayment terms are shorter than mortgages — usually two to ...

How To Finance A Tiny House | Tiny house, Buy a tiny house, Pre fab ...
21.10.2025 ... How to finance a tiny home · ADU-specific loan: Some communities, especially those battling housing shortages, offer grants or other aid ...

How to Finance a Tiny Home
Resource List To Finance A Tiny House · HAC Lending For Affordable Tiny House Developers · Liberty Bank Of Utah · Monevo Lending Platform · Wells Fargo Personal ...

Can You Finance a Tiny House? Exploring Your Options
How to afford a tiny home? There can be several ways to finance a tiny home, including possibly a mortgage loan, home equity loan, HELOC, builder loan, RV loan, ...

How to Finance a Tiny Home (Even If It’s Your First Home) | Mint Tiny ...
Ready to own your dream tiny home? Our comprehensive guide covers everything you need to know — from financing tips to the buying process — so you can ...

Tiny Living, Big Savings: The Financial Considerations of Building a ...
03.12.2024 ... We've financed tiny homes through over a dozen different lenders as RVs, manufactured homes, or personal assets. Finding the best lender for you depends on ...

Can You Finance a Tiny House? Exploring Your Options
18.02.2021 ... How to finance a tiny house is such a common question that people grapple with. Since tiny houses are mostly built on wheels and fall into a ...

What Are the Best Ways to Finance a Tiny House in Canada? - how shine home
06.12.2016 ... While traditional lending options for tiny houses were scarce in the past, Cardinal Financial now offers Conventional financing for tiny homes, ...

Can You Finance a Tiny House? Exploring Your Options
18.02.2021 ... How to finance a tiny house is such a common question that people grapple with. Since tiny houses are mostly built on wheels and fall into a ...

Finance a Tiny House | Kiwi Tiny Homes
06.12.2016 ... While traditional lending options for tiny houses were scarce in the past, Cardinal Financial now offers Conventional financing for tiny homes, ...

Tiny House Finance | Finding finance solutions for Tiny House ...
Jodie is living and breathing his own financial wellbeing movement by embracing the tiny house movement. Why pay a mortgage for decades when you can still ...

How To Finance A Tiny House? (Complete & Easy Answer)
Ready to own your dream tiny home? Our comprehensive guide covers everything you need to know — from financing tips to the buying process — so you can ...

How to Finance A Tiny House - YouTube
What are the interest rates? Interest rates range between 9.95%pa to 15.95%pa based on your credit history, stability in employment & residence, asset backing, ...
How To Finance A Tiny Home in 2025 | Loan Pronto
16.09.2025 ... You can finance a tiny home with a personal loan, RV loan, home equity loan, HELOC or builder loan. Home equity loans and HELOCs use your ...
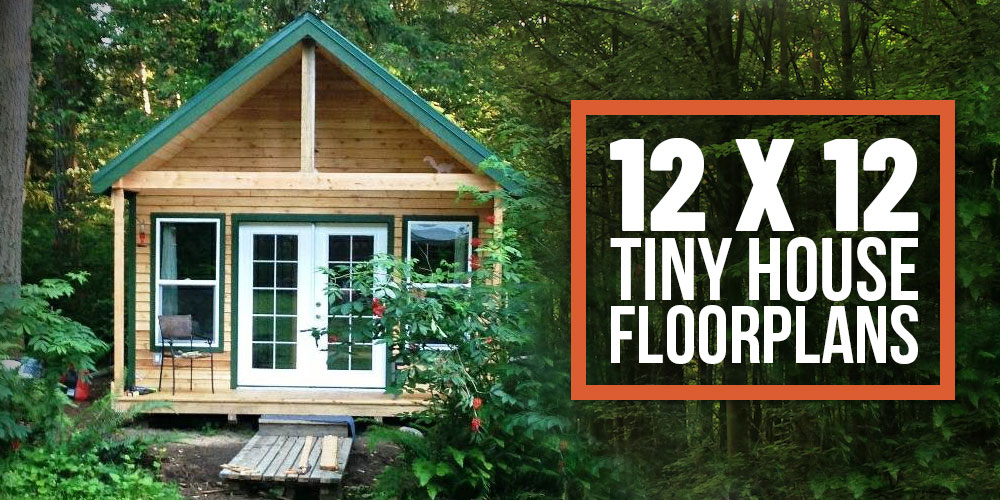
Total Cost To Build Tiny House at Jean Tunstall blog
09.07.2024 ... Personal loans, RV loans, and construction loans are common options for financing a tiny home on wheels.Some organizations and government ...
Tiny Home Financing: Find out if it’s worth it!
With the backing of a major bank or credit union, you can finance your tiny home for up to 20 years for the promise of smaller monthly payments. Comparatively, ...

Three ways to finance a tiny house - CSMonitor.com
Finance a tiny home with a LightStream loan. Low fixed rates for those with good to excellent credit. Loan amounts from $5000 to $100000. Learn more.

How do you finance a tiny house? - CSMonitor.com
Financing a Tiny Home is straightforward with the right guidance! We partner with trusted lenders who specialize in Tiny Homes to help you find terms that fit ...

How To Finance A Tiny House | Tiny house, Tiny, Finance