Understanding New York State Taxation on 401(k) Withdrawals
When planning for retirement, it's crucial to understand how your state taxes 401(k) withdrawals. New York State, like many others, has its own rules regarding the taxation of these retirement savings. Let's delve into the specifics of New York State's taxation policy on 401(k) withdrawals.
New York State Income Tax on 401(k) Withdrawals
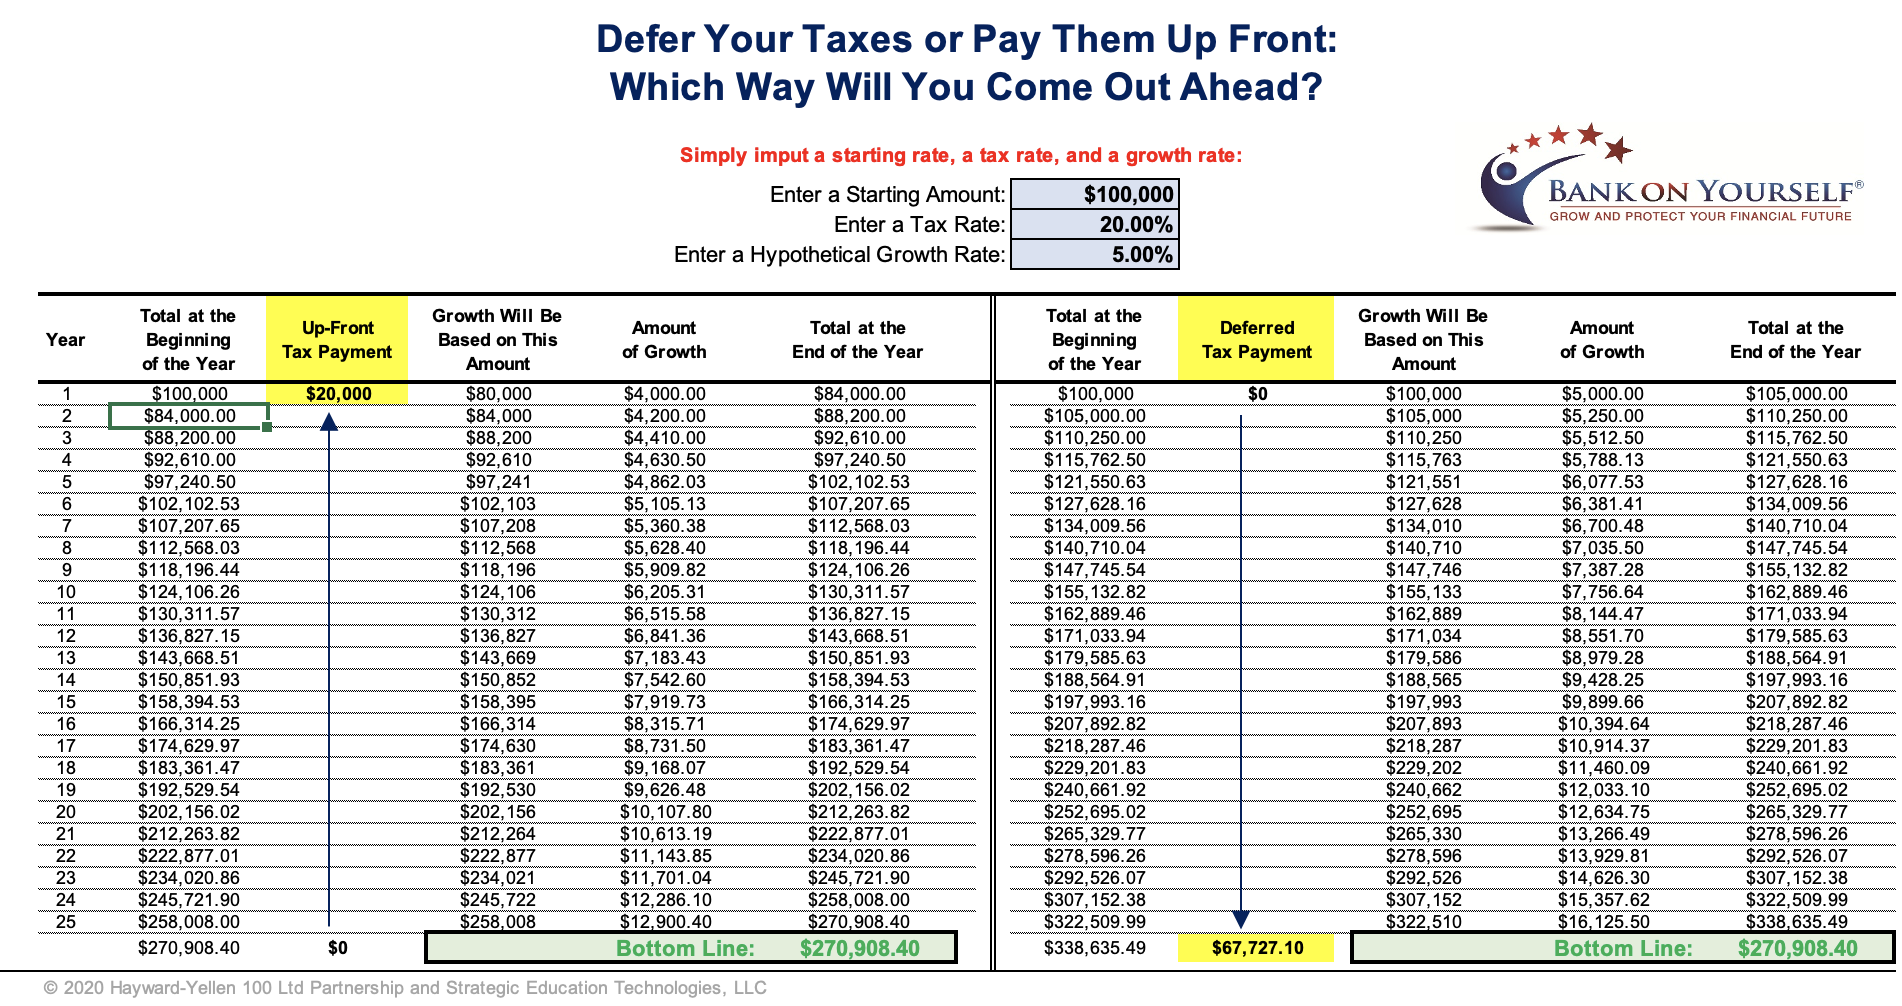
In New York State, 401(k) withdrawals are generally treated as ordinary income and are subject to state income tax. The tax rate applied depends on your taxable income, which includes your 401(k) withdrawals, minus any applicable deductions and exemptions.
New York State Income Tax Brackets (2021)
| Taxable Income | Tax Rate |
|---|---|
| $0 - $8,599 | 4% |
| $8,600 - $11,700 | 4.5% |
| $11,701 - $13,900 | 5.25% |
| $13,901 - $21,550 | 5.97% |
| $21,551 - $34,270 | 6.85% |
| $34,271 - $51,870 | 8.82% |
| $51,871 - $159,620 | 9.65% |
| $159,621 and above | 10.9% |
Taxation of 401(k) Withdrawals Before Age 59.5
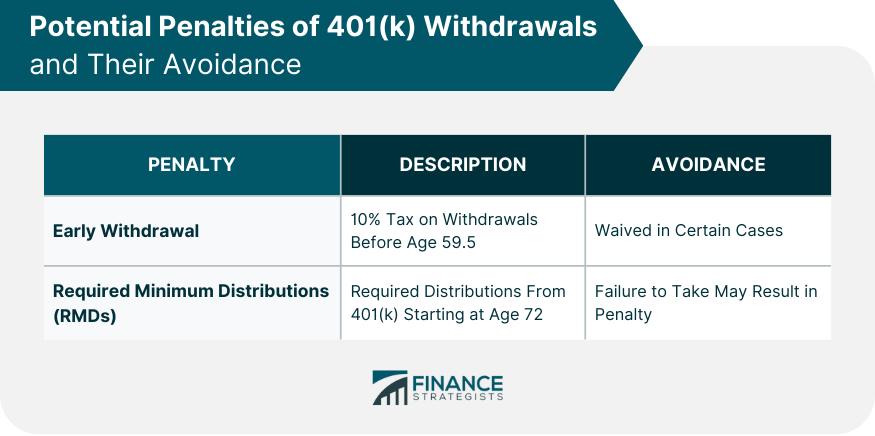
If you withdraw money from your 401(k) before reaching the age of 59.5, the withdrawal is subject to a 10% federal early withdrawal penalty, in addition to New York State income tax. However, there are some exceptions to this rule, such as withdrawals made for certain medical expenses or for the purchase of a first home.
Roth 401(k) Withdrawals in New York State
Roth 401(k) withdrawals are taxed differently than traditional 401(k) withdrawals. Qualified withdrawals from a Roth 401(k), meaning those made after the account has been open for at least five years and you're either 59.5, disabled, or using the funds for a first-time home purchase (up to $10,000), are tax-free at the federal and state levels.
New York State Tax Deductions and Credits
While 401(k) contributions are not deductible on your New York State tax return (as they are on your federal return), there are other deductions and credits you may be eligible for that could lower your taxable income and thus your state income tax liability. These include the New York State standard deduction, certain itemized deductions, and various tax credits.
Consult a Professional for Personalized Advice
Given the complexity of state and federal tax laws, it's always a good idea to consult with a tax professional or financial advisor when planning your retirement strategy. They can provide personalized advice based on your unique financial situation and help you make the most of your 401(k) savings.