Social Security Benefits for 2020: A Comprehensive Guide
The Social Security Administration (SSA) recently announced the changes to the Social Security amounts for 2020. These annual adjustments, known as cost-of-living adjustments (COLA), ensure that benefits keep pace with inflation. Here's a detailed look at the key changes and what they mean for beneficiaries.
Understanding the 2020 Cost-of-Living Adjustment
The 2020 COLA is 1.6%, the largest increase since 2012. This means that the average retired worker will see an increase of about $24 per month in their Social Security benefits. However, it's important to note that not all beneficiaries will see the same increase. The actual amount will depend on the specific benefit rate.
Maximum Social Security Benefits in 2020
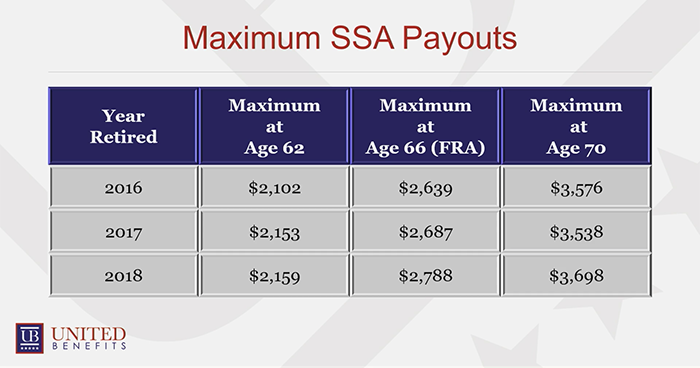
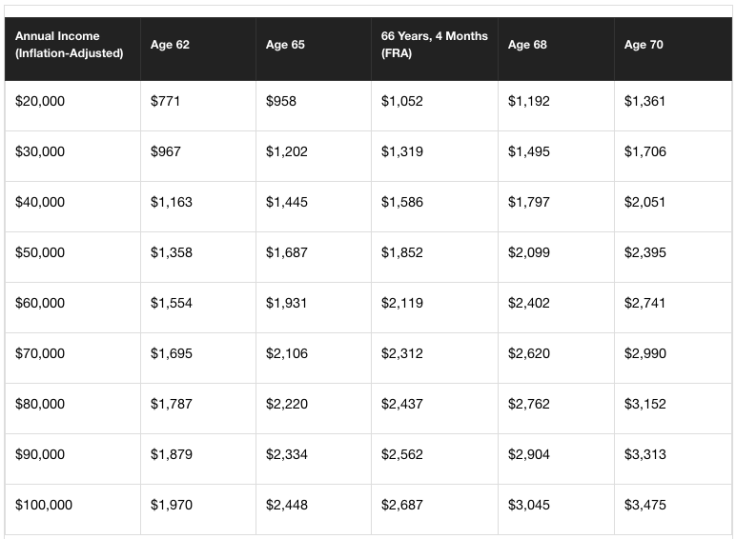
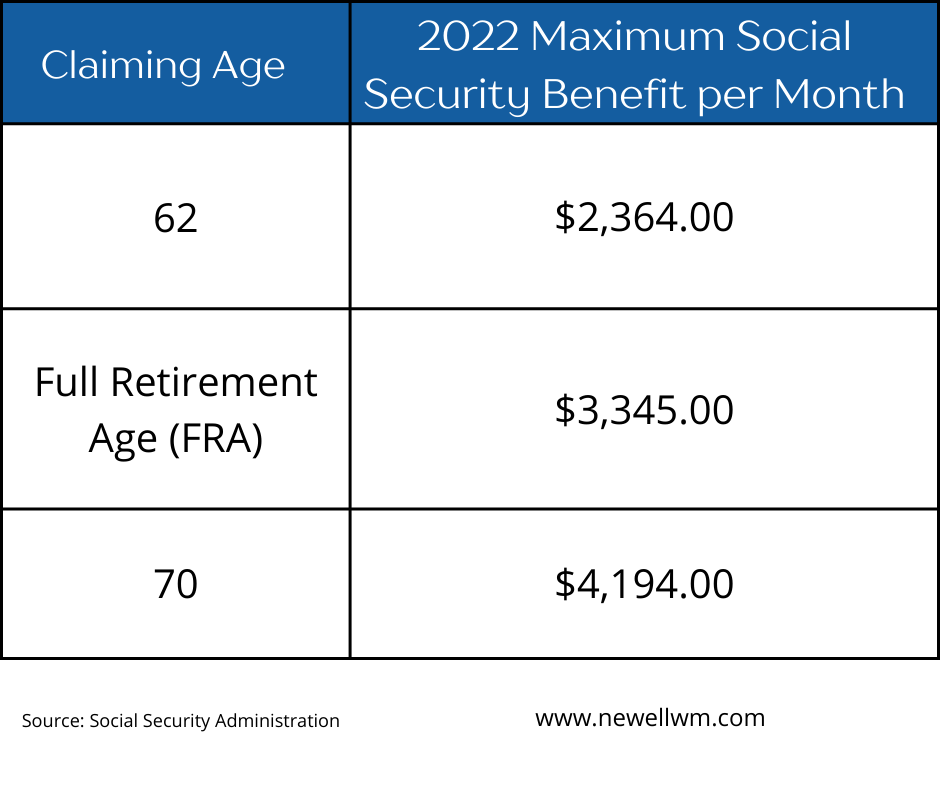
For retirees, the maximum possible Social Security benefit at full retirement age (FRA) in 2020 is $3,011 per month. This is up from $2,861 in 2019. The maximum benefit for those who claim benefits at age 70 is $3,790, up from $3,721 in 2019.
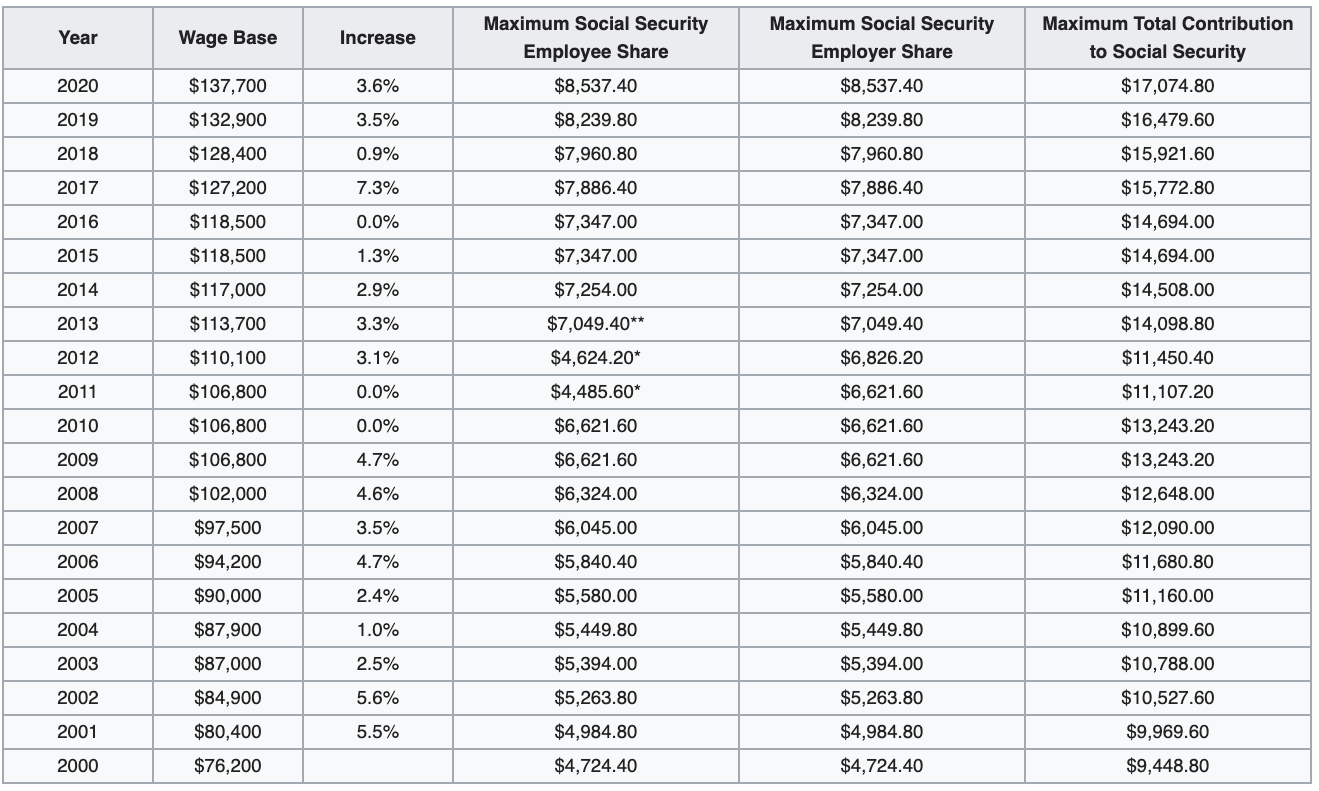
For disabled workers, the maximum benefit at FRA in 2020 is $2,265, up from $2,209 in 2019. The maximum benefit for those who claim benefits at age 70 is $3,148, up from $3,088 in 2019.
Other Changes to Social Security Amounts in 2020
- Earnings Limit: The earnings limit for workers who are younger than FRA will increase to $18,240 in 2020, up from $17,640 in 2019. This means that for every $2 earned above this limit, $1 will be deducted from their benefits.
- Full Retirement Age: The FRA for people born in 1960 is 67, and it will remain the same in 2020. However, for those born in 1961, the FRA will increase to 67 years and 2 months.
- Retirement Earnings Test Exemption Amounts: The limit on earnings subject to the retirement earnings test will increase to $18,240 in 2020, up from $17,640 in 2019. The limit on earnings for people who have reached FRA will increase to $48,600 in 2020, up from $46,920 in 2019.
How the 2020 Changes Affect Beneficiaries
The 2020 COLA is a welcome increase for Social Security beneficiaries, but it's important to remember that it only partially offsets the increased cost of living. According to The Senior Citizens League, a nonpartisan senior citizens advocacy group, the buying power of Social Security benefits has declined by about 30% since 2000 due to inflation.
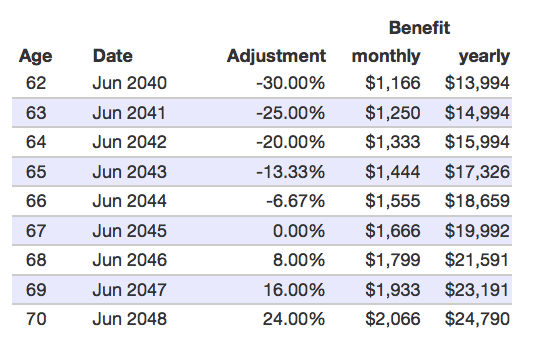
Moreover, the 2020 changes do not address the ongoing solvency issues of the Social Security program. The SSA estimates that the trust funds will be depleted by 2035, at which point benefits could be reduced by up to 21% for all beneficiaries.

Given these challenges, it's more important than ever for beneficiaries to understand their benefits and plan for their financial future. The SSA provides a wealth of resources to help beneficiaries understand their benefits and plan for retirement. It's also a good idea to consult with a financial advisor to ensure that your retirement plan is on track.