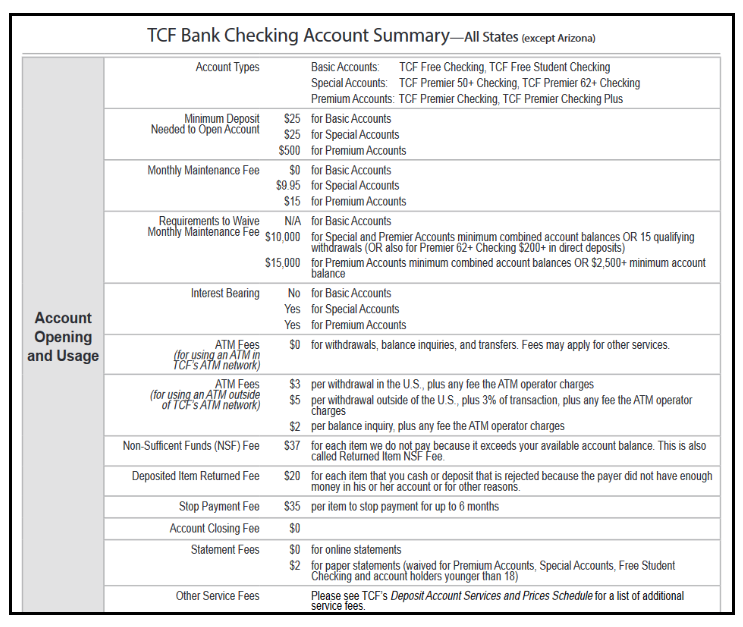
Signing up for a checking account may seem straightforward—fill out an application, make a deposit, and start writing checks or using your debit card. However, buried within the paperwork you likely skimmed over is a critical document: the checking account agreement. This legal contract outlines the terms, fees, and responsibilities both you and the bank banking institution agree to. Often overlooked, understanding the "fine print" is essential to avoiding unexpected charges and managing your finances effectively. This guide will walk you through the key components of a typical checking account agreement and explain why knowing the "fine print answer key" matters more than most people realize.
What Is a Checking Account Agreement?
A checking account agreement, sometimes called a deposit account contract or terms and conditions, is the official document provided by your bank when you open an account. It's a legally binding contract that specifies the rules governing your banking relationship. While everyone knows about interest rates, the agreement details much more—it covers overdraft policies, fee schedules, your liability in case of fraud, and how disputes are handled.
Most customers receive this agreement digitally or in a packet of papers. Regardless, it's crucial to read it carefully. Key elements typically include:

- Account Fees: Lists all charges for maintenance, ATM usage, and overdrafts.
- Overdraft Policies: Explains what happens if you spend more than your available balance.
- Electronic Transactions: Details on debits, credits, and holds.
- Dispute Resolution: Outlines arbitration or court procedures.
Overdraft Fees and Opt-In Rules
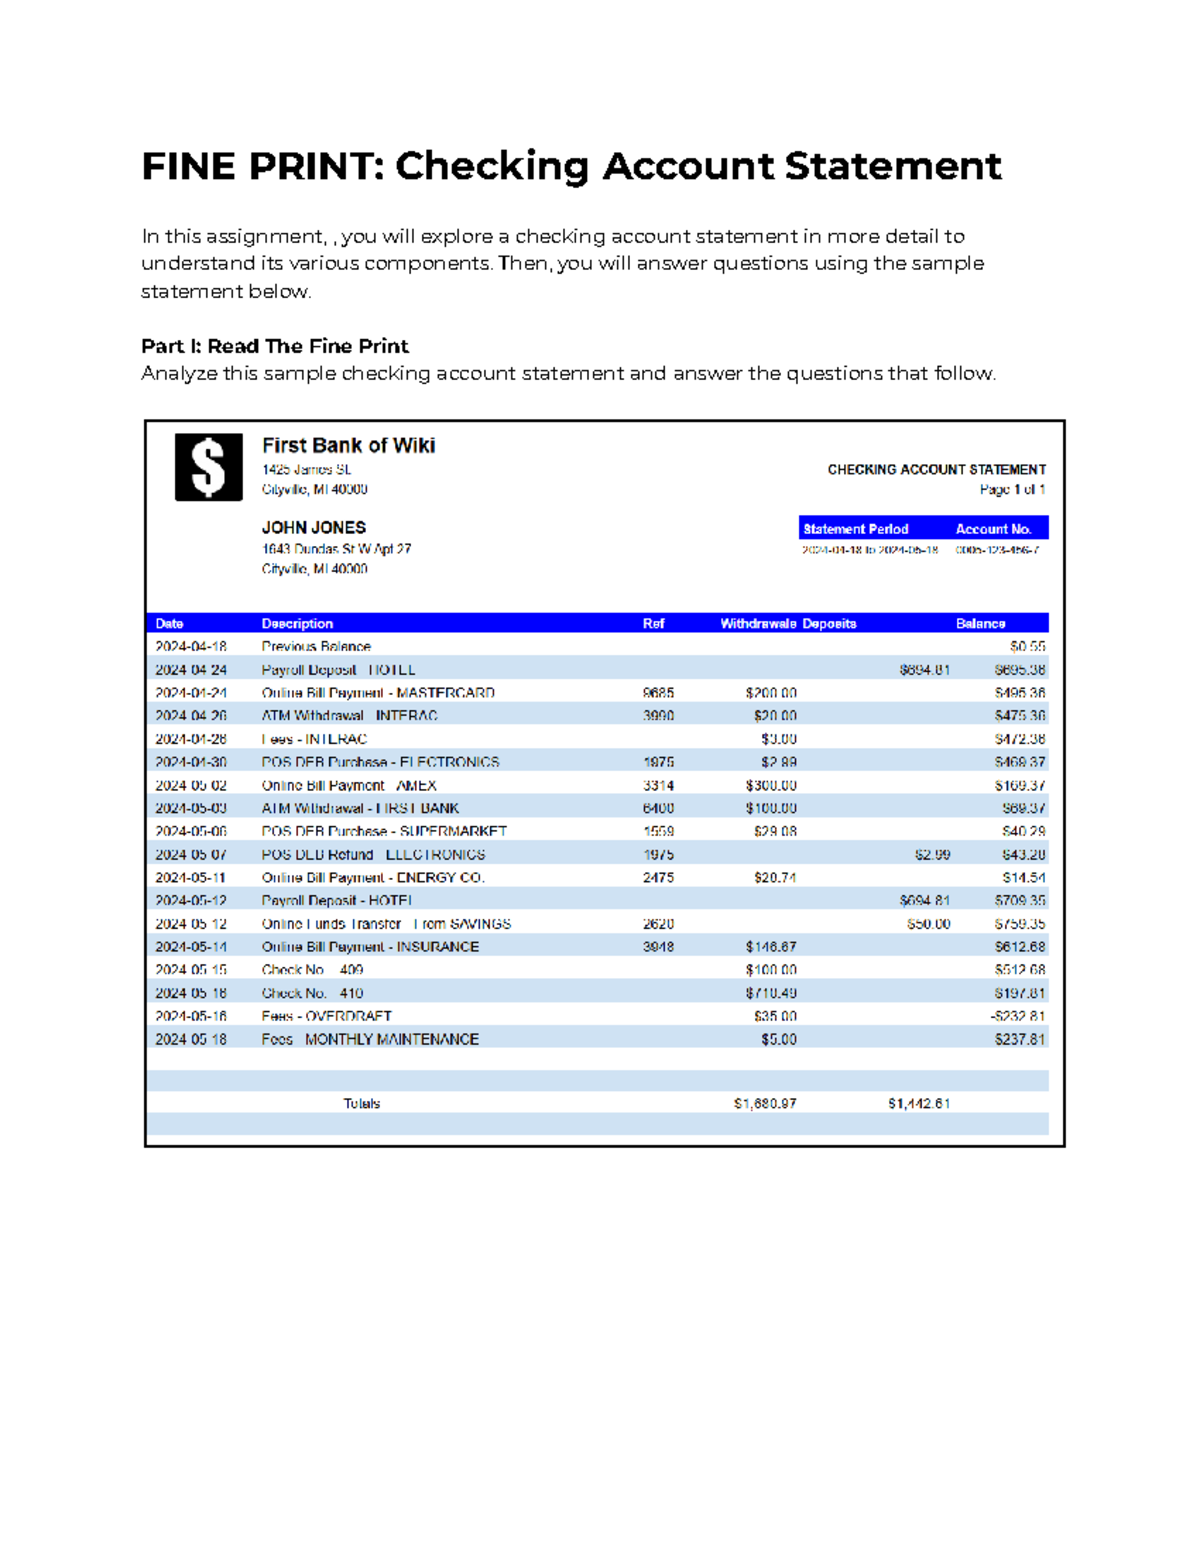
One of the most costly areas in the fine print involves overdrafts. Historically, banks would automatically enroll you in overdraft protection, which allowed transactions to go through even if you didn't have enough money—often at a steep cost. The Federal Reserve's Regulation E now requires you to opt-in for certain overdraft services. The agreement will detail:
- The fee per overdraft item (often $35 or more).
- Daily limits on overdraft charges.
- The right to revoke your opt-in at any time.
Understanding this section alone could save you hundreds of dollars annually in unexpected fees.
Electronic Fund Transfers and Holds
Your agreement also governs how electronic payments and deposits are handled. For instance, when you deposit a check, the funds aren't always available immediately. Sections regarding the Expedited Funds Availability Act explain the bank's policy on holds. Normally:
- First $200 of a deposit may be available immediately, with the rest subject to hold periods.
- Electronic transfers (like mobile deposits) may have different timelines than in-branch deposits.
Knowing these rules ensures you aren't caught off guard when making large purchases or transferring funds. The agreement also discusses liability for unauthorized transactions under the Electronic Fund Transfer Act—generally, timely reporting minimizes your losses.
Dispute Resolution and Arbitration
The agreement will state how conflicts between you and the bank are resolved. While some agreements allow lawsuits in local courts, many banks include an arbitration clause. Under this provision, disputes must go through a private arbitrator instead of public courts. Arbitration clauses often include a class action waiver, meaning you cannot join a group lawsuit if many customers face the same issue. This is a critical distinction, as individual arbitration is typically faster but may limit legal options.
Additionally, the contract specifies the governing law—for a national bank, this is often the state where the bank is headquartered, which may differ from your home state.
Account Closure and Dormancy
Closing a checking account may seem simple: take out your funds and inform the bank. But the fine print often includes provisions for dormant accounts. Once inactive for a period (commonly 12–24 months), banks may:
- Reduce your interest rate or increase fees.
- Turn over funds to the state via escheatment.
- Permanently freeze your account.
Understanding these rules helps ensure your money remains accessible and you avoid unwelcome surprises.
Staying Informed: Regulatory Protections
Federal regulations provide additional consumer protections beyond the bank's agreement. The Consumer Financial Protection Bureau (CFPB) offers resources on account agreements, common complaints, and your rights under federal law. By staying informed, you ensure the terms align with current regulations and avoid exploitative practices.
Being aware of your checking account agreement's details empowers you to make sound financial decisions. Take the time to revisit your contract at least annually or when major life changes occur—marriage, career shifts, or moving to a new state. Knowledge of the fine print isn't just about avoiding penalties; it's about maximizing your financial control and security.