Endorsing a check is a fundamental step in ensuring that funds are correctly transferred from the payer to the payee. Whether you are cashing a paycheck, depositing a client payment, or handling a refund, the signature line on the back of the check is the security mechanism that authorizes your financial institution to process the transaction. A poorly executed endorsement can lead to delays, bounced deposits, or even fraud, making it essential to understand the precise methodology.
Understanding the Anatomy of Check Endorsement
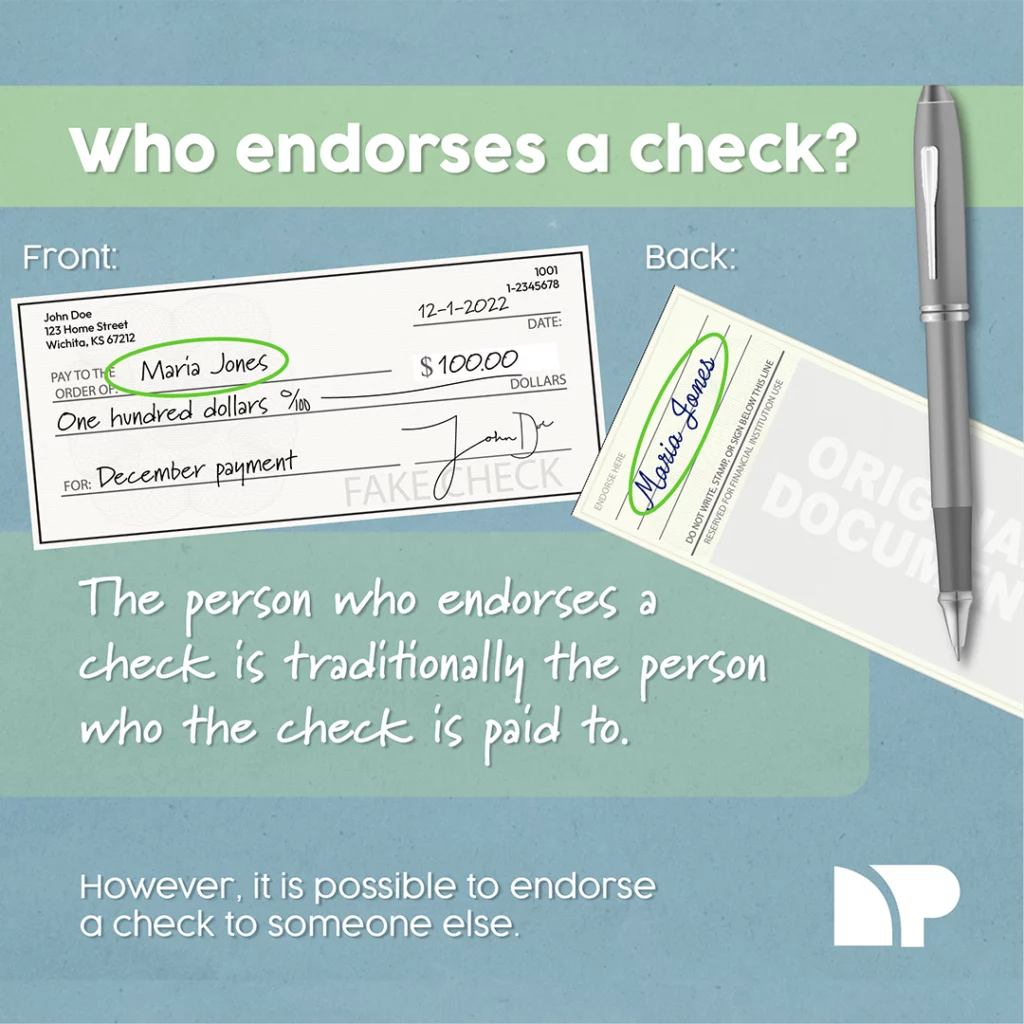
The back of a check features a series of thin lines and a signature box specifically designated for your endorsement. This area is not merely a formality; it is a legal contract between you and your bank. When you sign your name exactly as it appears on the front of the check, you are providing constructive notice to the financial institution that you are the rightful recipient of the funds. Banks are trained to look for specific criteria during endorsement verification, and any deviation from these standards can trigger holds or rejections.
Standard Endorsement: The Basic Method
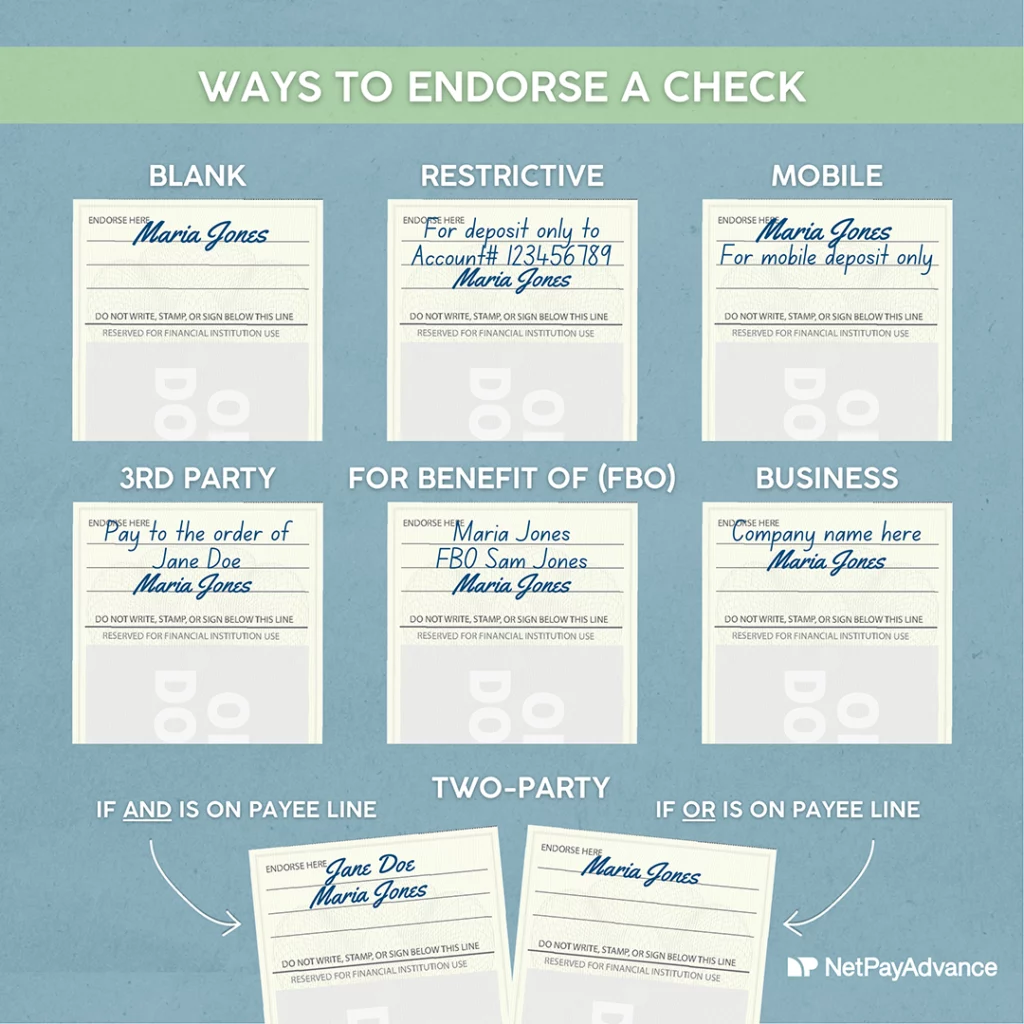
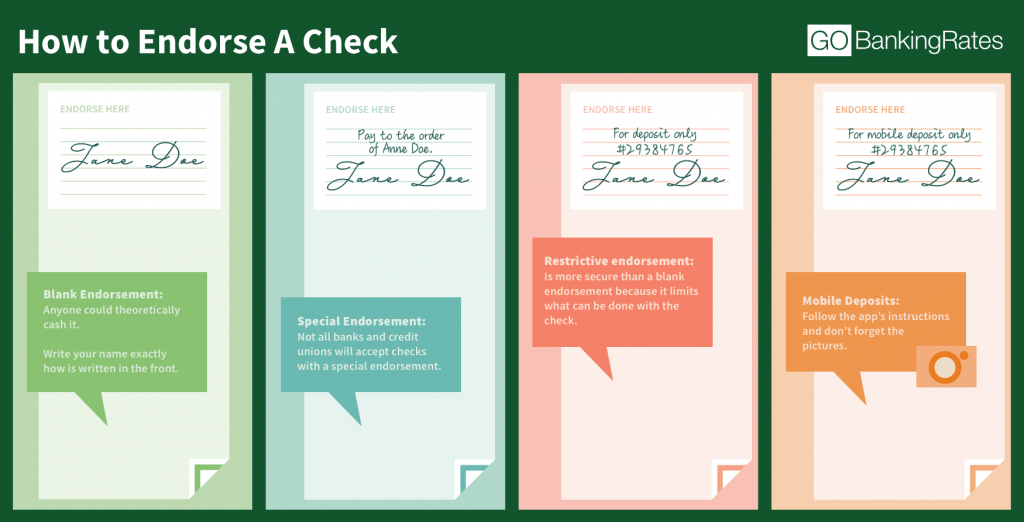
The most common form of endorsement involves signing your name exactly as it appears on the "Payable To" line of the check. This is known as a blank endorsement because it does not specify any restrictions on how the funds can be used. To execute this, you should:

- Sign your name in the top portion of the endorsement area.
- Use black or blue ink to ensure clarity and compatibility with scanning equipment.
- Avoid drawing lines or writing unrelated notes, which can confuse automated processing systems.
Once signed, the check can be cashed immediately at a bank or retail location, or it can be presented for deposit into your account.
Restrictive Endorsements for Security and Specificity2
While a standard endorsement offers convenience, a restrictive endorsement provides a layer of security that is highly recommended for electronic deposits. This method involves adding instructions above your signature that limit how the check can be processed. The most common type is the "For Deposit Only" endorsement, which prevents the check from being cashed by a third party if it is lost or stolen.
To create a restrictive endorsement, you should sign your name as usual, but include the text "For Deposit Only" beneath the signature. Below that, write the account number where the funds should be deposited. This ensures that even if the check is misplaced, it can only be credited to the intended account, significantly reducing the risk of fraud.

Depositing vs. Cashing: Strategic Endorsement Choices
The action you intend to take with the check should dictate how you endorse it. If you plan to deposit the check via mobile banking, a restrictive endorsement is ideal. The banking app’s imaging software will recognize the account number you typed, streamlining the digital deposit process.
If you are cashing the check immediately, a blank endorsement is necessary. However, financial institutions often recommend that you sign the check just before you enter the bank lobby or the ATM. This reduces the window of opportunity for the document to be lost or stolen, ensuring that the physical endorsement matches the moment of transaction.
Troubleshooting Common Endorsement Errors
Even the most careful individuals can make mistakes when endorsing a check. One of the most frequent errors is signing the check too early; if you sign the back before reaching the teller or ATM, the check becomes vulnerable. Another common issue is attempting to correct a mistake with correction fluid or tape, as this often triggers fraud alerts and leads to rejection.
If you make an error, the safe protocol is to write "VOID" in large letters across the front of the check, dispose of it securely, and request a new one from the issuer. Banks are generally unable to process checks with altered endorsements, so prevention is always the better strategy than correction.
Special Considerations for Business and Third-Party Checks
Business checks and third-party endorsements involve additional complexity that requires specific attention. For a business check, the endorsement typically requires two signatures: one from a signer on the company signature card and another from a witness or second authorized officer. This dual-signature requirement is a security measure to prevent embezzlement.
When dealing with a third-party check—where the original payee signs the check over to a different person—both parties should be present. The original payee should endorse the check with a restrictive endorsement that includes the phrase "Pay to the order of [New Payee Name]," followed by the new payee signing beneath that. Always verify the specific policies of your bank regarding third-party checks, as many institutions have stringent rules regarding this practice.
The Evolving Landscape: Mobile Deposit and Digital Wallets
Modern banking has changed the etiquette of endorsements, particularly with the rise of mobile deposit. While the physical rules remain the same, the application has evolved. When using a mobile app, banks often require a signature that is darker and more prominent to ensure the Optical Character Recognition (OCR) software can read the endorsement accurately.
Digital wallets like Apple Pay or Google Pay have further reduced the need for physical check handling. These platforms use image recognition and encrypted data to replicate the endorsement process virtually. However, understanding the physical process remains crucial for situations that require in-person transactions or when dealing with institutions that do not offer digital deposit options.
How To Endorse Checks, Plus When and How To Sign
Expert Advice on How to Endorse a Check - wikiHow
How to Endorse a Check | Net Pay Advance

3 Ways to Endorse a Check - wikiHow

Expert Advice on How to Endorse a Check - wikiHow
How to Endorse a Check | Net Pay Advance

Expert Advice on How to Endorse a Check - wikiHow

Expert Advice on How to Endorse a Check - wikiHow

How to Endorse a Check | Check City Blog

Expert Advice on How to Endorse a Check - wikiHow

What Is A Qualified Endorsement at Vivian Donnelly blog
How to Endorse a Check Update 2022

3 Ways to Endorse a Check - wikiHow

Expert Advice on How to Endorse a Check - wikiHow

How to Endorse a Check

Master the Art of Endorsing Checks
Everything You Need to Know About Checks | Jefferson Bank

How to Endorse a Check: Step-by-Step Guidance

How to Endorse a Check | Check City Blog

How to Endorse a Check: Step-by-Step Guidance